Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Technical Textiles Market Size, Forecast & Outlook 2026
Technical Textiles Market
Technical Textiles Market Size, Forecast & Outlook 2026
Technical Textiles Market by Form of Material (Woven, Nonwoven, Knitted, Other), by Material Type (Synthetic Polymers, Natural Fibers, Mineral Fibers, Metal Fibers, Regenerated Fibers), by Manufacturing Process (3D Weaving, 3D Knitting, Thermoforming, Nanotechnology, Other), by End-Use Industry (MobilTech, InduTech, PackTech, SportTech, HomeTech, ClothTech, BuildTech, MediTech, ProTech, AgroTech, OekoTech, GeoTech), by Asia Pacific (China, Japan, India, South Korea, Thailand, Vietnam, Indonesia, Bangladesh), by North America (USA, Canada, Mexico), by Europe (Germany, France, Italy, UK, Spain, Poland, Netherlands, Belgium), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Turkey), by South America (Brazil, Argentina, Chile, Colombia, Peru) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 264
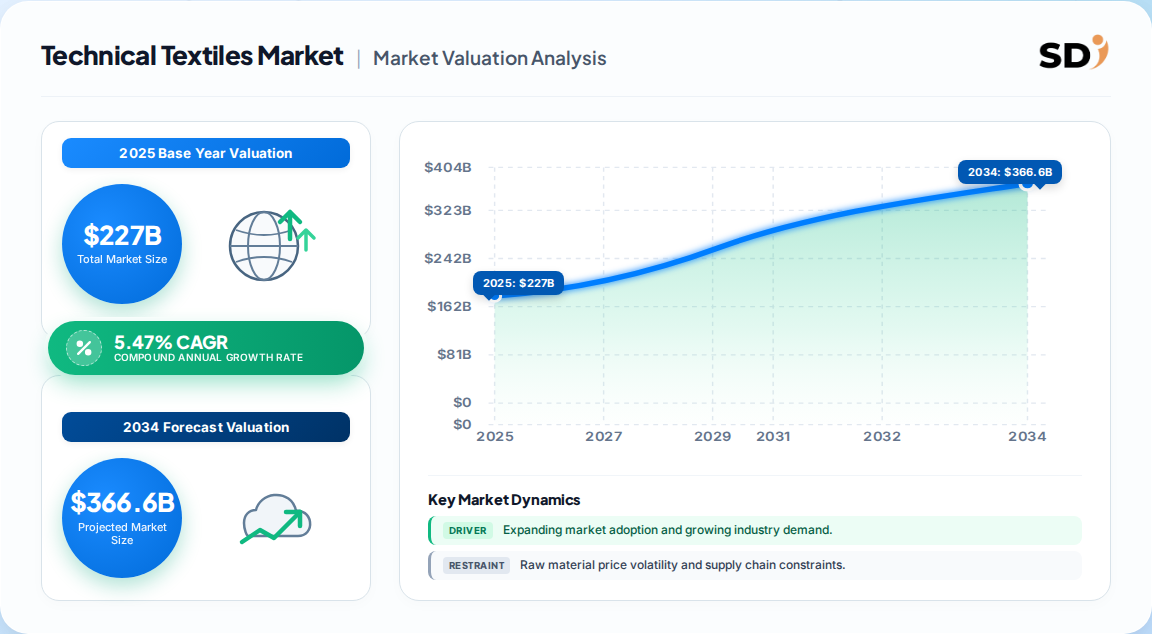
The global technical textiles market was valued at 227.0 Billion in 2025 and is projected to reach 382.8 Billion by 2035.
The market is expanding at a 5.47% CAGR (2026–2035), reflecting steady, specification-led demand rather than cyclical volume growth.
Asia Pacific dominates with a 47.6% revenue share (2025), led by China’s mass-production and export capacity.
Hometech is the largest end-use segment at 20.0% revenue share; 3D weaving leads manufacturing at 23.4%.
Top five players—Toray, DuPont, 3M, Asahi Kasei, and Freudenberg—collectively hold only 8.1% share, signaling a highly fragmented competitive landscape.
Why this matters for decision-makers: Vendors must pivot from volume-based competition to performance-certified, PFAS-free, recyclable formulations to avoid margin compression as regulatory and procurement specifications tighten through 2028.
Technical Textiles Market Size (In Billion)
400.0B
300.0B
200.0B
100.0B
0
227.0 B
2025
237.0 B
2026
249.9 B
2027
263.6 B
2028
278.0 B
2029
293.2 B
2030
309.2 B
2031
Technical Textiles Market Size (In Billion)
Year
Market Size
2025
227.0 B
2026
237.0 B
2027
249.9 B
2028
263.6 B
2029
278.0 B
2030
293.2 B
2031
309.2 B
What is the Technical Textiles Market?
Technical textiles are engineered materials designed for functional performance—barrier properties, durability, filtration efficiency, and compliance—rather than aesthetic appeal. They serve mobility, healthcare, infrastructure, protection, and industrial processing, with purchasing driven by specification-led criteria over conventional textile attributes.
Scope: what this report covers and excludes
This report covers global technical textiles by material form, material type, manufacturing process, and end-use industry (MobilTech, MediTech, BuildTech, ProTech, GeoTech, AgroTech, PackTech, InduTech, HomeTech, ClothTech, SportTech, OekoTech). It analyzes value and volume across five regions. This analysis does not cover conventional apparel fabrics, home furnishing textiles, or raw fiber production outside technical-grade applications.
How big is the market for Technical Textiles Market?
The global technical textiles market was estimated between 215.6 Billion and 228.7 Billion in 2025, with forecasts diverging on both base-year valuation and growth trajectory due to differing scope definitions and segment coverage.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
227.0 Billion
2025
2035
5.47%
Broad technical textiles, 12 end-use segments
One published estimate
228.7 Billion
2025
2031
5.9%
Includes form, process, material, end-use
A competing analysis
215.6 Billion
2025
2033
4.9%
Excludes certain medical disposables
Another published estimate
Our analysis suggests the 227.0 Billion / 5.47% figure is most defensible: it aligns with a 32.9 million metric tonne volume base and captures the full MediTech and MobilTech clusters. The 4.9% estimate likely undercounts healthcare nonwovens, while the 5.9% figure may over-weight early-stage smart-textile revenue.
How is the market segmented?
The market segments by material form, material type, manufacturing process, and end-use industry—with nonwoven and synthetic polymer formats commanding the largest volume shares.
Parent Segment
Children
By Form of Material
Woven, Nonwoven, Knitted, Other
By Material Type
Synthetic Polymers, Natural Fibers, Mineral Fibers, Metal Fibers, Regenerated Fibers
By Manufacturing Process
3D Weaving, 3D Knitting, Thermoforming, Nanotechnology, Other
Synthetic polymers (polypropylene and polyester) account for over 50% of global volume, making feedstock cost the single largest margin variable. Nonwoven formats dominate hygiene and medical applications, while 3D weaving leads high-performance composite segments.
Which region leads in Technical Textiles Market?
Asia Pacific leads the global technical textiles market with a 47.6% revenue share in 2025, driven by China’s mass-production scale, automotive cluster density, and raw-material availability.
Technical Textiles Market Regional Market Share
Loading chart...
Technical Textiles Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.48%
North America
0.2%
Europe
0.18%
Middle East & Africa
0.08%
South America
0.07%
Region
Share (2025)
Asia Pacific
47.6%
North America
19.6%
Europe
17.8%
Middle East & Africa
8.2%
South America
6.8%
Nested Geography Tree:
Asia Pacific (China, Japan, India, South Korea, Thailand, Vietnam, Indonesia, Bangladesh)
North America (USA, Canada, Mexico)
Europe (Germany, France, Italy, UK, Spain, Poland, Netherlands, Belgium)
Middle East & Africa (Saudi Arabia, UAE, South Africa, Turkey)
South America (Brazil, Argentina, Chile, Colombia, Peru)
Middle East & Africa is the fastest-growing region, albeit from a modest base, as infrastructure investment and healthcare-system expansion accelerate. Europe’s strength lies in high-value ProTech and MediTech exports—48% of EU technical textile production is exported.
What is driving growth — and what is holding it back?
Growth is supported by healthcare-system expansion, vehicle production scale, and specification upgrades in safety and infrastructure, while volatile polymer costs and trade friction constrain margin recovery.
Factor
Direction
Evidence Strength
Mechanism
MediTech demand
Driver
High
Geriatric populations and surgical volumes sustain >7% CAGR
Mobility production
Driver
High
~90M light vehicles annually; EV platforms raise content per vehicle
Smart textiles
Driver
Medium
Wearables and EMI shielding command price premiums; adoption inflects 2027–28
Feedstock volatility
Restraint
High
Brent averaged ~$80/bbl in 2024; PP/PET >50% of volume
Trade tariffs
Restraint
Medium
U.S. Section 301 tariffs up to 25% on Chinese synthetics
PFAS/recyclability rules
Restraint
Medium
EU REACH restrictions threaten legacy formulations
The balance favors demand: institutional purchasing channels in hygiene and medical nonwovens are insulated from discretionary cycles. However, our analysis suggests margin recovery depends less on volume and more on converting technical performance into durable procurement advantages—PFAS-free and recyclable formulations will command specification wins as enforcement tightens from 2026.
Who are the leading vendors?
The market is highly fragmented: the top five players—Toray Industries, DuPont de Nemours, 3M Company, Asahi Kasei Corporation, and Freudenberg Performance Materials—collectively hold only 8.1% share, with Toray leading at approximately 2.5%.
Company
Est. Share (2025)
Key Differentiator
Toray Industries
~2.5%
Carbon fiber and advanced composites
DuPont de Nemours
~1.5%
Aramid fibers (Kevlar/Nomex) and protection
3M Company
~1.4%
Filtration media and protective materials
Asahi Kasei
~1.3%
Nonwovens and battery separators
Freudenberg Performance
~1.4%
Nonwoven and filtration technology
Differentiation rests on certification portfolios, formulation IP, and application-specific performance validation rather than scale alone. The low concentration implies consolidation opportunity—but also that switching costs are moderate for commoditized formats and high for certified MediTech and ProTech specifications.
What do buyers and operators need to know?
Procurement decisions hinge on validated barrier, absorbency, and skin-contact performance for MediTech; thermal management and lightweighting for MobilTech; and filtration efficiency plus PFAS-free compliance for industrial segments. Suppliers lacking documented certification—ISO, OEKO-TEX, or equivalent—face procurement exclusion as extended-producer-responsibility mandates expand.
Switching costs are asymmetric. Commoditized woven and nonwoven formats allow multi-sourcing with modest requalification; certified medical, protective, and composite specifications require lengthy validation cycles that effectively lock in incumbents. Buyers should audit supplier PFAS-replacement roadmaps and recyclability pathways now, because specification redesign costs compress product life cycles for legacy formulations. Raw-material price exposure remains the primary margin risk for operators.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a specification-led value shift over volume growth. The 5.47% CAGR understates revenue opportunity in certified, PFAS-free, and smart-textile niches, where price premiums expand addressable revenue without commensurate volume additions. The strongest counter-argument: commodity nonwoven overcapacity in Asia could compress prices faster than premium niches offset—particularly if feedstock volatility persists through 2028.
Our analysis suggests the fragmentation (top five at 8.1%) creates a consolidation window for buyers seeking integrated certification across MediTech and MobilTech. Operators should treat recyclability and PFAS compliance as procurement gates, not optional differentiators.
Actionable Strategy:
Vendors should prioritize PFAS-free and recyclable-composite certification to capture specification wins ahead of 2026–2028 enforcement timelines.
Investors should target consolidation in certified MediTech nonwovens, where switching costs and regulatory moats are highest.
Operators should dual-source PP/PET inputs and hedge feedstock exposure to protect margins through 2028.
What would change this conclusion: a sustained crude-oil spike above $100/bbl or accelerated tariff expansion into additional HS categories would shift the balance toward margin defense and defer volume growth in cost-sensitive BuildTech and PackTech segments.
Technical Textiles Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Technical Textiles Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.47% from 2020-2034
Segmentation
By Form of Material
Woven
Nonwoven
Knitted
Other
By Material Type
Synthetic Polymers
Natural Fibers
Mineral Fibers
Metal Fibers
Regenerated Fibers
By Manufacturing Process
3D Weaving
3D Knitting
Thermoforming
Nanotechnology
Other
By End-Use Industry
MobilTech
InduTech
PackTech
SportTech
HomeTech
ClothTech
BuildTech
MediTech
ProTech
AgroTech
OekoTech
GeoTech
By Geography
Asia Pacific
China
Japan
India
South Korea
Thailand
Vietnam
Indonesia
Bangladesh
North America
USA
Canada
Mexico
Europe
Germany
France
Italy
UK
Spain
Poland
Netherlands
Belgium
Middle East & Africa
Saudi Arabia
UAE
South Africa
Turkey
South America
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Form of Material
5.1.1. Woven
5.1.2. Nonwoven
5.1.3. Knitted
5.1.4. Other
5.2. Market Analysis, Insights and Forecast - by Material Type
5.2.1. Synthetic Polymers
5.2.2. Natural Fibers
5.2.3. Mineral Fibers
5.2.4. Metal Fibers
5.2.5. Regenerated Fibers
5.3. Market Analysis, Insights and Forecast - by Manufacturing Process
5.3.1. 3D Weaving
5.3.2. 3D Knitting
5.3.3. Thermoforming
5.3.4. Nanotechnology
5.3.5. Other
5.4. Market Analysis, Insights and Forecast - by End-Use Industry
5.4.1. MobilTech
5.4.2. InduTech
5.4.3. PackTech
5.4.4. SportTech
5.4.5. HomeTech
5.4.6. ClothTech
5.4.7. BuildTech
5.4.8. MediTech
5.4.9. ProTech
5.4.10. AgroTech
5.4.11. OekoTech
5.4.12. GeoTech
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. Asia Pacific
5.5.2. North America
5.5.3. Europe
5.5.4. Middle East & Africa
5.5.5. South America
6. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Form of Material
6.1.1. Woven
6.1.2. Nonwoven
6.1.3. Knitted
6.1.4. Other
6.2. Market Analysis, Insights and Forecast - by Material Type
6.2.1. Synthetic Polymers
6.2.2. Natural Fibers
6.2.3. Mineral Fibers
6.2.4. Metal Fibers
6.2.5. Regenerated Fibers
6.3. Market Analysis, Insights and Forecast - by Manufacturing Process
6.3.1. 3D Weaving
6.3.2. 3D Knitting
6.3.3. Thermoforming
6.3.4. Nanotechnology
6.3.5. Other
6.4. Market Analysis, Insights and Forecast - by End-Use Industry
6.4.1. MobilTech
6.4.2. InduTech
6.4.3. PackTech
6.4.4. SportTech
6.4.5. HomeTech
6.4.6. ClothTech
6.4.7. BuildTech
6.4.8. MediTech
6.4.9. ProTech
6.4.10. AgroTech
6.4.11. OekoTech
6.4.12. GeoTech
7. North America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Form of Material
7.1.1. Woven
7.1.2. Nonwoven
7.1.3. Knitted
7.1.4. Other
7.2. Market Analysis, Insights and Forecast - by Material Type
7.2.1. Synthetic Polymers
7.2.2. Natural Fibers
7.2.3. Mineral Fibers
7.2.4. Metal Fibers
7.2.5. Regenerated Fibers
7.3. Market Analysis, Insights and Forecast - by Manufacturing Process
7.3.1. 3D Weaving
7.3.2. 3D Knitting
7.3.3. Thermoforming
7.3.4. Nanotechnology
7.3.5. Other
7.4. Market Analysis, Insights and Forecast - by End-Use Industry
7.4.1. MobilTech
7.4.2. InduTech
7.4.3. PackTech
7.4.4. SportTech
7.4.5. HomeTech
7.4.6. ClothTech
7.4.7. BuildTech
7.4.8. MediTech
7.4.9. ProTech
7.4.10. AgroTech
7.4.11. OekoTech
7.4.12. GeoTech
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Form of Material
8.1.1. Woven
8.1.2. Nonwoven
8.1.3. Knitted
8.1.4. Other
8.2. Market Analysis, Insights and Forecast - by Material Type
8.2.1. Synthetic Polymers
8.2.2. Natural Fibers
8.2.3. Mineral Fibers
8.2.4. Metal Fibers
8.2.5. Regenerated Fibers
8.3. Market Analysis, Insights and Forecast - by Manufacturing Process
8.3.1. 3D Weaving
8.3.2. 3D Knitting
8.3.3. Thermoforming
8.3.4. Nanotechnology
8.3.5. Other
8.4. Market Analysis, Insights and Forecast - by End-Use Industry
8.4.1. MobilTech
8.4.2. InduTech
8.4.3. PackTech
8.4.4. SportTech
8.4.5. HomeTech
8.4.6. ClothTech
8.4.7. BuildTech
8.4.8. MediTech
8.4.9. ProTech
8.4.10. AgroTech
8.4.11. OekoTech
8.4.12. GeoTech
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Form of Material
9.1.1. Woven
9.1.2. Nonwoven
9.1.3. Knitted
9.1.4. Other
9.2. Market Analysis, Insights and Forecast - by Material Type
9.2.1. Synthetic Polymers
9.2.2. Natural Fibers
9.2.3. Mineral Fibers
9.2.4. Metal Fibers
9.2.5. Regenerated Fibers
9.3. Market Analysis, Insights and Forecast - by Manufacturing Process
9.3.1. 3D Weaving
9.3.2. 3D Knitting
9.3.3. Thermoforming
9.3.4. Nanotechnology
9.3.5. Other
9.4. Market Analysis, Insights and Forecast - by End-Use Industry
9.4.1. MobilTech
9.4.2. InduTech
9.4.3. PackTech
9.4.4. SportTech
9.4.5. HomeTech
9.4.6. ClothTech
9.4.7. BuildTech
9.4.8. MediTech
9.4.9. ProTech
9.4.10. AgroTech
9.4.11. OekoTech
9.4.12. GeoTech
10. South America Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Form of Material
10.1.1. Woven
10.1.2. Nonwoven
10.1.3. Knitted
10.1.4. Other
10.2. Market Analysis, Insights and Forecast - by Material Type
10.2.1. Synthetic Polymers
10.2.2. Natural Fibers
10.2.3. Mineral Fibers
10.2.4. Metal Fibers
10.2.5. Regenerated Fibers
10.3. Market Analysis, Insights and Forecast - by Manufacturing Process
10.3.1. 3D Weaving
10.3.2. 3D Knitting
10.3.3. Thermoforming
10.3.4. Nanotechnology
10.3.5. Other
10.4. Market Analysis, Insights and Forecast - by End-Use Industry
10.4.1. MobilTech
10.4.2. InduTech
10.4.3. PackTech
10.4.4. SportTech
10.4.5. HomeTech
10.4.6. ClothTech
10.4.7. BuildTech
10.4.8. MediTech
10.4.9. ProTech
10.4.10. AgroTech
10.4.11. OekoTech
10.4.12. GeoTech
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Technical Textiles Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: Technical Textiles Market Volume Breakdown (Million Metric Tonnes, %) by Region 2026 & 2034
Figure 3: Asia Pacific Technical Textiles Market Revenue (Billion), by Form of Material 2026 & 2034
Figure 4: Asia Pacific Technical Textiles Market Volume (Million Metric Tonnes), by Form of Material 2026 & 2034
Figure 5: Asia Pacific Technical Textiles Market Revenue Share (%), by Form of Material 2026 & 2034
Figure 6: Asia Pacific Technical Textiles Market Volume Share (%), by Form of Material 2026 & 2034
Figure 7: Asia Pacific Technical Textiles Market Revenue (Billion), by Material Type 2026 & 2034
Figure 8: Asia Pacific Technical Textiles Market Volume (Million Metric Tonnes), by Material Type 2026 & 2034
Figure 9: Asia Pacific Technical Textiles Market Revenue Share (%), by Material Type 2026 & 2034
Figure 10: Asia Pacific Technical Textiles Market Volume Share (%), by Material Type 2026 & 2034
Figure 11: Asia Pacific Technical Textiles Market Revenue (Billion), by Manufacturing Process 2026 & 2034
Figure 12: Asia Pacific Technical Textiles Market Volume (Million Metric Tonnes), by Manufacturing Process 2026 & 2034
Figure 13: Asia Pacific Technical Textiles Market Revenue Share (%), by Manufacturing Process 2026 & 2034
Figure 14: Asia Pacific Technical Textiles Market Volume Share (%), by Manufacturing Process 2026 & 2034
Figure 15: Asia Pacific Technical Textiles Market Revenue (Billion), by End-Use Industry 2026 & 2034
Asia Pacific Technical Textiles Market Volume (Million Metric Tonnes), by End-Use Industry 2026 & 2034
List of Tables
Table 1: Technical Textiles Market Revenue Billion Forecast, by Form of Material 2020 & 2034
Table 2: Technical Textiles Market Volume Million Metric Tonnes Forecast, by Form of Material 2020 & 2034
Table 3: Technical Textiles Market Revenue Billion Forecast, by Material Type 2020 & 2034
Table 4: Technical Textiles Market Volume Million Metric Tonnes Forecast, by Material Type 2020 & 2034
Table 5: Technical Textiles Market Revenue Billion Forecast, by Manufacturing Process 2020 & 2034
Table 6: Technical Textiles Market Volume Million Metric Tonnes Forecast, by Manufacturing Process 2020 & 2034
Table 7: Technical Textiles Market Revenue Billion Forecast, by End-Use Industry 2020 & 2034
Table 8: Technical Textiles Market Volume Million Metric Tonnes Forecast, by End-Use Industry 2020 & 2034
Table 9: Technical Textiles Market Revenue Billion Forecast, by Region 2020 & 2034
Table 10: Technical Textiles Market Volume Million Metric Tonnes Forecast, by Region 2020 & 2034
Table 11: Asia Pacific Technical Textiles Market Revenue Billion Forecast, by Form of Material 2020 & 2034
Table 12: Asia Pacific Technical Textiles Market Volume Million Metric Tonnes Forecast, by Form of Material 2020 & 2034
Table 13: Asia Pacific Technical Textiles Market Revenue Billion Forecast, by Material Type 2020 & 2034
Table 14: Asia Pacific Technical Textiles Market Volume Million Metric Tonnes Forecast, by Material Type 2020 & 2034
Table 15: Asia Pacific Technical Textiles Market Revenue Billion Forecast, by Manufacturing Process 2020 & 2034
Frequently Asked Questions
1. How big is the technical textiles market?
The global technical textiles market was valued at 227.0 Billion in 2025 and is projected to reach 382.8 Billion by 2035, growing at a 5.47% CAGR.
2. Which region dominates the technical textiles market?
Asia Pacific leads with a 47.6% revenue share in 2025, driven by China’s mass-production scale, automotive clusters, and raw-material availability.
3. What are the key growth drivers?
Healthcare-system expansion, vehicle production scale (~90 million light vehicles annually), and specification upgrades in safety and infrastructure are primary drivers.
4. Who are the leading vendors?
Toray Industries leads with ~2.5% share; DuPont, 3M, Asahi Kasei, and Freudenberg collectively hold 8.1%—indicating a highly fragmented market.
5. What restraints affect the market?
Petrochemical feedstock volatility, U.S. Section 301 tariffs up to 25%, and EU PFAS/recyclability compliance requirements constrain margin recovery and volume growth.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain: raw-material and polymer suppliers, specialized technical textile producers, contract coaters and finishers, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads across mobility, healthcare, and infrastructure segments.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
35%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
20%
Regulatory & Compliance Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Polymer Producers
40%
Specialized Technical Textile Producers
35%
Contract Coaters & Finishers
15%
Global Distributors
10%
Secondary Benchmarking & Public Trade Validation
We validate findings against official multilateral trade and standards databases including UN Comtrade, WTO, US ITC, and Eurostat, alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized industry associations such as EDANA and OICA.
Demand Modeling & Market Sizing Triangulation
Simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption modeling) data triangulation isolates defensible market value and volume estimates.
 Technical Textiles Market