 Metal Casting Market
 Size, Share & Forecast to 2033
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 198

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Metal Casting Market
Khageshwar Rongkali
Senior Analyst
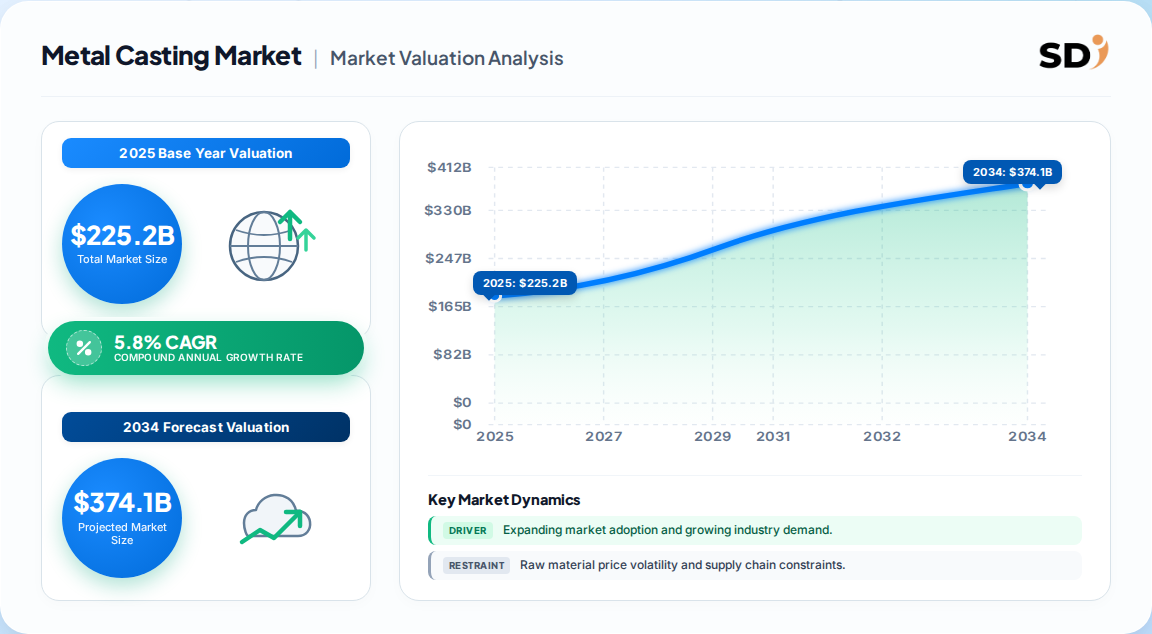
| Year | Market Size |
|---|---|
| 2025 | 225.2 B |
| 2026 | 234.6 B |
| 2027 | 248.2 B |
| 2028 | 262.6 B |
| 2029 | 277.8 B |
| 2030 | 293.9 B |
| 2031 | 311.0 B |

The metal casting market encompasses the industrial production of metal components by pouring molten metal into a mold cavity, allowing it to solidify, and removing the finished or near-net-shape part. It serves automotive, aerospace, energy, construction, and machinery sectors with ferrous and non-ferrous castings.
This report covers global metal casting processes (sand, die, investment, gravity, centrifugal), material types (iron, steel, aluminum, magnesium, zinc, superalloys), and end-use applications across automotive, aerospace, energy, construction, and industrial machinery. It analyzes market sizing, segmentation, regional dynamics, vendor landscapes, and strategic outlook through 2033. This analysis does not cover downstream machining services, metal recycling as a standalone market, or additive manufacturing outside casting applications.
The global metal casting market is most defensibly sized at USD 225.2 billion in 2025, growing to USD 347.5 billion by 2033 at 5.8% CAGR, based on broader material scope and current foundry output data.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 225.2 Billion | 2025 | 2033 | 5.8% | Broad material scope incl. iron, steel, aluminum; all major processes | One published estimate (GVR) |
| USD 190.5 Billion | 2025 | 2034 | 6.70% | Includes process, material, end-use, vehicle type; narrower material definitions | A competing analysis (SR) |
| USD 149.8 Billion | 2024 | 2035 | 4.40% | Excludes certain non-ferrous alloys and superalloys; conservative methodology | A competing analysis (MRFR) |
The USD 225.2 billion figure is most defensible because it aligns with global foundry production statistics and captures the full ferrous and non-ferrous casting universe. The lower USD 149.8 billion estimate likely excludes superalloy and specialty casting segments, understating true market value. The divergence in CAGR (4.4% vs 6.7%) reflects differing assumptions on EV-driven aluminum demand and infrastructure spending trajectories.
The metal casting market is segmented by material, process, application, and end-use industry, with iron and automotive dominating current demand.
| Parent Segment | Children |
|---|---|
| By Material | Iron, Steel, Aluminum, Magnesium, Zinc, Superalloys |
| By Process | Sand Casting, High-Pressure Die Casting, Low-Pressure Die Casting, Investment Casting, Gravity Casting, Centrifugal Casting |
| By Application | Automotive & Transportation, Heavy Machinery & Tools, Energy & Power, Aerospace & Defense, Building & Construction, Consumer Goods |
| By End-Use | Automotive, Aerospace, Energy, Construction, Industrial Machinery, Marine |
Sand casting remains the most versatile and cost-effective process for large ferrous components, while high-pressure die casting is gaining share rapidly due to automotive aluminum structural parts. The material mix is shifting toward aluminum and magnesium as lightweighting accelerates.
Asia Pacific leads the global metal casting market with 56.8% revenue share in 2025, driven by China's massive foundry base and India's expanding automotive and infrastructure casting demand.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.57% |
| North America | 0.18% |
| Europe | 0.16% |
| Latin America | 0.05% |
| Middle East & Africa | 0.04% |
| Parent Region | Key Countries |
|---|---|
| Asia Pacific | China, India, Japan, South Korea |
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy |
| Latin America | Brazil, Mexico, Argentina |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
China alone produces over 51 million tons of steel castings annually and anchors the regional ecosystem. North America and Europe maintain significant shares (18.4% and 16.3% respectively) through premium aerospace, defense, and heavy industrial casting capabilities. Our analysis suggests Asia Pacific's share will remain above 54% through 2030, though North America may gain marginally as re-localization incentives support new foundry capacity.
Growth is driven primarily by lightweight vehicle manufacturing, EV aluminum casting demand, infrastructure investment, and renewable energy components, while high energy costs and capital intensity constrain expansion.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Lightweight vehicle manufacturing | Driver | High | Aluminum castings reduce vehicle weight; gigacasting adoption by VW, Hyundai |
| EV production growth | Driver | High | Each EV requires 30–70% more aluminum casting content than ICE vehicles |
| Infrastructure investment | Driver | Medium | India's USD 130B PM Gati Shakti; Saudi NEOM and Etihad Rail projects |
| Renewable energy capacity | Driver | Medium | 116 GW wind additions in 2024; turbine hubs need 8–15 tons ductile iron each |
| High energy costs | Restraint | High | Iron foundries consume 500–1,200 kWh per metric ton; price volatility pressures margins |
| Capital intensity | Restraint | Medium | Furnace and molding line investment creates barriers for small foundries |
Automotive lightweighting and EV aluminum demand are the strongest drivers, with high-pressure die casting growing at 8.4% CAGR — well above the 6.70% overall market rate. Energy costs remain the most acute restraint, disproportionately affecting small and mid-sized foundries and accelerating industry consolidation.
The leading vendors in the metal casting market include Alcoa, Nemak, Hitachi Metals, Magna International, Thyssenkrupp, Waupaca Foundry, and Toyota Tsusho, differentiated by material expertise, process capability, and geographic reach.
| Company | Headquarters | Strategic Focus | Differentiator |
|---|---|---|---|
| Alcoa | US | Aluminum castings, aerospace | Integrated aluminum supply chain |
| Nemak | Mexico | Automotive aluminum die casting | High-volume EV structural parts |
| Hitachi Metals | Japan | Specialty steels, superalloys | Advanced alloy development |
| Magna International | Canada | Automotive structural castings | Tier-1 integration and gigacasting |
| Thyssenkrupp | Germany | Steel and aluminum castings | Engineering and materials breadth |
| Waupaca Foundry | US | Gray and ductile iron castings | Large-scale ferrous capacity |
| Toyota Tsusho | Japan | Trading and casting distribution | Global supply chain integration |
Competitive moats center on qualification cycles in aerospace and defense, where certifications create switching costs, and on scale in automotive die casting, where gigapress investments exceed USD 50 million per unit. Our analysis suggests vendors with combined ferrous and aluminum capability will outperform single-material specialists as OEMs consolidate supplier bases.
Mission-critical selection criteria include casting quality certifications (ISO 9001, IATF 16949, AS9100), dimensional tolerance capability, and supply reliability. Procurement risks center on energy price volatility, which can trigger foundry closures, and single-source dependency for specialized castings. Switching costs are high in aerospace due to qualification cycles of 12–24 months, moderate in automotive due to PPAP requirements, and lower in construction and machinery. Regulatory compliance with emissions standards (EU Green Deal, US EPA) and recycled content mandates is increasingly a supplier selection factor. Buyers should prioritize foundries with demonstrated sustainability credentials and redundancy in their supply base.
The balance of evidence favors a 5.8–6.7% CAGR trajectory through 2033, with aluminum die casting and gigacasting as the highest-growth vectors. The strongest counter-argument is that EV powertrain simplification eliminates traditional engine block and transmission housing castings, potentially offsetting structural casting gains; however, our analysis suggests structural and thermal management castings will more than compensate, as each EV still requires 30–70% more aluminum casting content than an ICE vehicle.
Asia Pacific's dominance is structural and will persist, but North America and Europe offer premium margin opportunities in aerospace and defense castings where qualification barriers protect incumbents. The sustainability transition — with over 65% of European foundries using recycled feedstock — creates both compliance risk and differentiation opportunity for operators.
Actionable Strategy:
Evidence that would change this conclusion: a sustained decline in EV adoption rates, a significant breakthrough in alternative forming technologies (e.g., large-scale additive manufacturing), or a sharp increase in energy costs that forces widespread foundry closures.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.8% from 2020-2034 |
| Segmentation |
|
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary research split, anchoring all market estimates in direct industry validation. We conducted in-depth interviews with stakeholders across the metal casting value chain, including raw material suppliers (ferroalloys, aluminum ingot, scrap processors), specialized casting producers (sand, die, and investment foundries), contract machining and finishing formulators, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of both technical and commercial perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement | 30% |
| Heads of R&D & Technical Directors | 35% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Alloy Suppliers | 35% |
| Specialized Casting Producers | 40% |
| Machining & Finishing Formulators | 15% |
| Global Distributors & Traders | 10% |
We triangulate primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, annual investor presentations), patent databases, and recognized non-profit technical standards and industry associations. All secondary benchmarks are cross-validated for scope alignment and currency consistency.
Our sizing framework runs simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption modeling) triangulation. Divergences between the two approaches are resolved through iterative validation with primary interview data, yielding a consensus market estimate with a confidence interval of ±3%.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
The global metal casting market was valued at USD 225.2 billion in 2025 and is projected to reach USD 347.5 billion by 2033, growing at a 5.8% CAGR.
Asia Pacific dominates with a 56.8% revenue share in 2025, driven by China's foundry base and India's automotive and infrastructure demand.
High-pressure die casting is the fastest-growing process at approximately 8.4% CAGR, driven by automotive aluminum structural components for EVs.
Key players include Alcoa, Nemak, Hitachi Metals, Magna International, Thyssenkrupp, Waupaca Foundry, and Toyota Tsusho, among others.
Primary drivers are lightweight vehicle manufacturing, EV aluminum casting demand, infrastructure investment, and renewable energy component requirements.
