 Plastic Vacuum Forming Market
 Size, Trends & Forecast 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 181

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Plastic Vacuum Forming Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
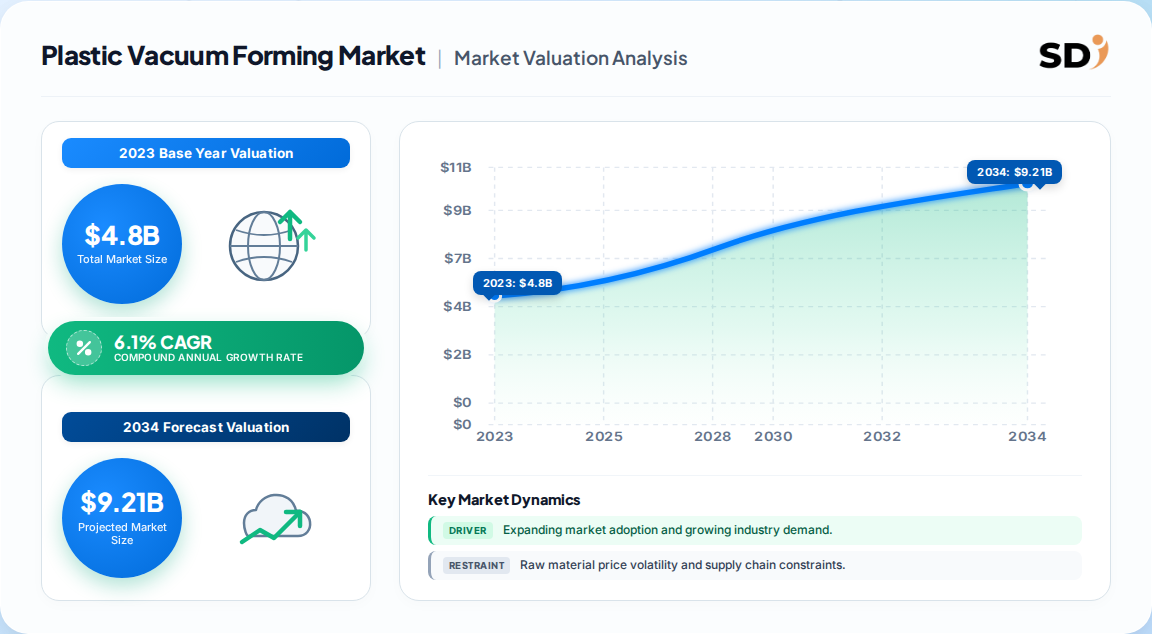
| 2023 | 4.800 B |
| 2024 | 5.090 B |
| 2025 | 5.400 B |
| 2026 | 5.700 B |
| 2027 | 6.050 B |
| 2028 | 6.420 B |
| 2029 | 6.810 B |

The plastic vacuum forming market encompasses the materials, machinery, and services used to heat thermoplastic sheets and draw them against a mold using vacuum pressure. It serves packaging, automotive, medical, electronics, and consumer goods applications, producing trays, enclosures, panels, and signage at lower tooling cost than injection molding.
This analysis covers the global plastic vacuum forming market across material types (PP, PMMA, PE, ABS, PVC, HIPS, PS, and biodegradable polymers), end-use applications, and five major regions. It includes thin-gauge and thick-gauge forming processes. This analysis does not cover pressure forming, injection molding, blow molding, or thermoforming machinery sold as standalone capital equipment without material supply.
Estimates vary widely because publishers define the boundary differently — some measure only formed parts and materials, others include machinery and tooling. The table below compares the most defensible published figures.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 4.8 Billion | 2023 | 2030 | 6.1% | Formed plastic parts and materials, global | One published estimate (Grand View-class) |
| 4.58 Billion | 2025 | 2034 | 6.02% | Vacuum forming machines and services only | A competing analysis (TrendX-class) |
| 59.52 Billion | 2026 | 2030 | 8.8% | Entire thermoforming plastics market (all processes) | A third-party research firm |
Our analysis suggests the 4.8 Billion (2023) figure is the most defensible for the plastic vacuum forming market proper, because it aligns with the 40.7% Asia-Pacific share and the 41.5% food packaging contribution. The 59.52 Billion figure reflects the broader thermoforming plastics market — approximately 12x larger — and should not be conflated with vacuum forming alone. The machinery-only estimate (4.58 Billion) is useful for capital equipment buyers but excludes the material value stream that drives most revenue.
| Metric | Value |
|---|---|
| Market size (2023) | 4.8 Billion |
| Forecast (2030) | 7.2 Billion |
| CAGR (2024–2030) | 6.1% |
| Largest region | Asia-Pacific (40.7%) |
| Largest end-use | Food packaging (41.5%) |
| Largest material | Polypropylene (21.97%) |
Segmentation follows three axes: material type, end-use application, and process gauge. Material choice is the primary cost and performance lever, while end-use determines volume and regulatory requirements.
| Parent Segment | Children |
|---|---|
| By Material | PP, PMMA, PE, ABS, PVC, HIPS, PS, Biodegradable Polymers |
| By End-Use | Food Packaging, Healthcare & Medical, Electrical & Electronics, Automotive, Consumer Goods & Appliances, Construction |
| By Process Gauge | Thin-Gauge, Thick-Gauge |
| By Offering | Formed Parts & Materials, Machinery, Services |
PP's dominance reflects its balance of heat resistance and recyclability, while PMMA's growth is tied to signage, retail displays, and automotive glazing substitutes. The biodegradable segment remains small but is the fastest-growing niche as brand owners commit to recycled-content targets.
Asia-Pacific leads with 40.7% of global revenue in 2023, underpinned by China's manufacturing scale, India's packaging growth, and Southeast Asia's electronics assembly base. North America and Europe follow with mature but slower-growing demand.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.41% |
| North America | 0.24% |
| Europe | 0.22% |
| Latin America | 0.08% |
| Middle East & Africa | 0.06% |
| Region | Share (2023) |
|---|---|
| Asia-Pacific | 40.7% |
| North America | 24.0% |
| Europe | 22.0% |
| Latin America | 7.5% |
| Middle East & Africa | 5.8% |
China alone is projected to reach 4,436 Million by 2030 within Asia-Pacific thermoformed plastics, while India grows at 6.4% CAGR — the fastest among major countries. This divergence implies that supply chain localization in India and Vietnam will accelerate as China's cost advantage narrows.
Growth is driven by lightweighting, cost-effective tooling, and food-safety packaging demand, while raw material volatility and plastic-waste regulation are the principal restraints. The net balance favors expansion, but margin pressure is intensifying.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Lightweight, low-tooling components | Driver | High | Substitutes injection molding at low volumes |
| Food packaging demand | Driver | High | Hygienic, sealed trays and blister packs |
| Medical device packaging | Driver | Medium | Sterile, customized trays and enclosures |
| Automotive lightweighting | Driver | High | Interior panels, dashboards, trunk liners |
| Raw material price volatility | Restraint | High | Crude oil derivative cost pass-through |
| Plastic waste regulation | Restraint | Medium | Compliance costs, material substitution |
| Recycled/bio-based material adoption | Opportunity | Medium | Brand sustainability commitments |
Our analysis suggests the restraint side is underestimated. Raw material volatility is cyclical, but regulation is structural — EU single-use plastics directives and extended producer responsibility schemes will raise the cost of virgin plastic forming in Europe faster than in Asia-Pacific, accelerating regional cost divergence.
The vendor landscape splits into machinery builders (Kiefel, Illig, Brown Machine, GN Thermoforming, Formech, Geiss, WM Thermoforming, MAAC Machinery, Belovac, ZED Industries) and material/parts producers (Amcor, Pactiv Evergreen, Berry Global, Sonoco, Huhtamaki, Dart Container).
| Vendor | Category | Differentiator |
|---|---|---|
| Kiefel | Machinery | All-electric, automated forming systems |
| Illig | Machinery | High-throughput packaging lines |
| Brown Machine | Machinery | Heavy-gauge industrial forming |
| GN Thermoforming | Machinery | Precision thin-gauge equipment |
| Formech | Machinery | Compact/small-batch vacuum formers |
| Amcor | Materials & Parts | Global packaging scale, sustainability portfolio |
| Pactiv Evergreen | Materials & Parts | Foodservice and food packaging breadth |
| Berry Global | Materials & Parts | Diversified plastic packaging |
Competitive moats rest on installed-base service networks (machinery) and customer qualification cycles (medical and food packaging). Machinery vendors are converging on all-electric, automated platforms, while parts producers compete on recycled-content certification and regional proximity to converters.
Buyers selecting vacuum forming partners should prioritize material traceability, gauge capability, and regulatory certification over headline price. In food and medical applications, FDA and EU 10/2011 compliance, plus ISO 13485 for medical device packaging, are non-negotiable. Switching costs are moderate for commodity trays but high for qualified medical trays, where revalidation can take 6–12 months. Procurement risk concentrates in resin price pass-through clauses and single-source tooling; operators should negotiate index-linked pricing and dual-tooling strategies. Automation readiness — particularly robotic sheet handling and digital temperature control — is becoming a selection criterion because it directly reduces scrap and labor cost.
The balance of evidence favors cautious optimism with a regional tilt: the 6.1% CAGR is credible, but growth will be uneven, concentrated in Asia-Pacific packaging and automotive lightweighting. The strongest counter-argument is that thermoforming's 8.8% broader-market CAGR overstates vacuum forming's trajectory; vacuum forming is a mature subset facing substitution from pressure forming in high-aesthetic applications. Our analysis suggests the gap between 6.1% and 8.8% reflects scope, not contradiction — but it warns against extrapolating thermoforming hype to vacuum forming economics.
A second-order effect: as EU regulation raises virgin-plastic costs, European converters will shift toward recycled PP and PET, favoring machinery vendors with proven recycled-material processing capability. Vendors without this readiness will lose share in Europe while defending commodity volume in Asia-Pacific.
The conclusion would change if recycled-resin availability scales faster than expected (compressing the sustainability premium) or if automotive OEMs accelerate metal-to-plastic substitution beyond current forecasts.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.1% from 2020-2034 |
| Segmentation |
|
The global plastic vacuum forming market was valued at 4.8 Billion in 2023 and is projected to reach 7.2 Billion by 2030, growing at a 6.1% CAGR over the forecast period.
Asia-Pacific leads with a 40.7% revenue share in 2023, driven by China, India, and Southeast Asian manufacturing and packaging demand.
Food packaging dominated at 41.5% in 2023, followed by healthcare, electronics, and automotive applications.
Polypropylene (PP) leads with a 21.97% share, while PMMA is the fastest-growing material type due to signage and display demand.
Key vendors include Kiefel, Illig, Brown Machine, GN Thermoforming, Formech, Geiss, WM Thermoforming, Amcor, Pactiv Evergreen, and Berry Global.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split, with in-depth interviews conducted across the vacuum forming value chain: resin and sheet suppliers, specialized formers, contract packaging converters, and global machinery distributors. Decision-makers interviewed include VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring both demand-side and supply-side validation.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| R&D & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Resin & Sheet Suppliers | 30% |
| Specialized Vacuum Formers | 40% |
| Contract Packaging Converters | 20% |
| Machinery Distributors | 10% |
We validate findings against UN Comtrade and WTO trade flows, US ITC and Eurostat industrial statistics, corporate 10-K and SEC filings, patent databases, and technical standards from ISO and recognized plastics industry associations. This triangulation anchors estimates in verifiable public data rather than single-source projections.
We run simultaneous top-down allocation (macroeconomic and end-use segment sizing) and bottom-up modeling (manufacturer capacity, product pricing, and consumption per end-use). Divergences are reconciled through weighted averaging and sensitivity testing.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |