 High Performance Ceramic Coatings Market
 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 183

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 High Performance Ceramic Coatings Market
Khageshwar Rongkali
Senior Analyst

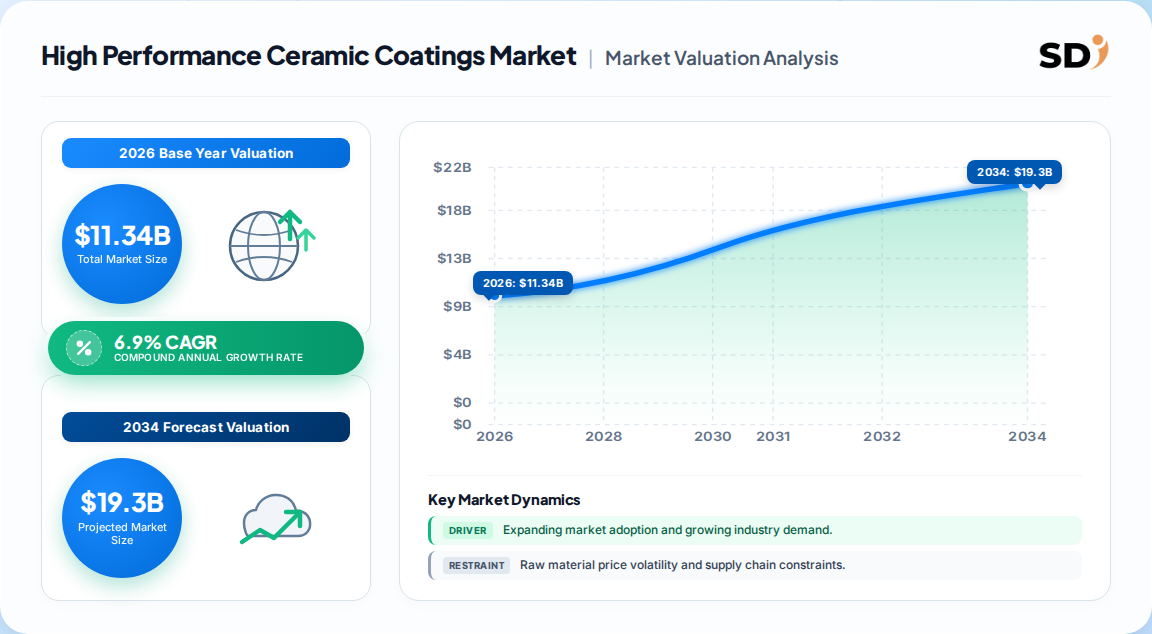
| Year | Market Size |
|---|---|
| 2025 | 10.65 B |
| 2026 | 11.34 B |
| 2027 | 12.12 B |
| 2028 | 12.96 B |
| 2029 | 13.85 B |
| 2030 | 14.78 B |

High performance ceramic coatings are thin ceramic layers — oxides, carbides or nitrides — deposited on metal, composite or plastic substrates via thermal spray, PVD or CVD to deliver superior resistance to high temperature, wear and corrosion. The market covers coating materials, application services and technology licensing across automotive, aviation, chemical, healthcare and energy end uses.
This analysis covers oxide, carbide and nitride coating products applied through thermal spray, physical vapor deposition, chemical vapor deposition and related technologies, sold to automotive, aviation, chemical equipment, healthcare, energy and industrial goods end users. Revenue includes coating materials and application services at the point of sale. It excludes decorative automotive detailing coatings, paints and primers, refractory bricks, and monolithic advanced ceramics. Powder metallurgy components and standalone thermal barrier design engineering are also outside the boundary. This analysis does not cover the broader ceramic coatings market used in consumer car-care or architectural glass protection.
The market is most defensibly sized at 11.34 Billion in 2026, reaching 14.78 Billion by 2030 at 6.9% CAGR — the mid-point of published estimates once the automotive-detailing segment is stripped out.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 10.65 → 14.78 Billion | 2025 | 2030 | 6.9% | Coatings materials + application services, all end uses | One published industry estimate |
| 10.5 → 13.9 Billion | 2024 | 2029 | 5.8% | Product, technology, channel, end use | A competing analysis |
| 11.44 → 23.42 Billion | 2023 | 2033 | 7.43% | Broad ceramic coatings incl. adjacent industrial | A competing analysis |
| 12.27 → 23.91 Billion | 2026 | 2036 | 6.9% | Product, application, technology | A competing analysis |
| 2.61 → 5.41 Billion | 2024 | 2035 | 6.86% | Narrow automotive-detailing-weighted scope | A competing analysis |
The 2.61 Billion figure is an outlier because it captures mainly consumer and detailing-grade coatings, not industrial HPCC. Our analysis suggests the 2025–2030 series is the most defensible planning basis: it aligns with the 5.8% conservative and 6.9% central cases while the 7.43% and 8.3% figures implicitly fold in adjacent industrial ceramics. The divergence implies buyers should anchor procurement and capex models on a 6.5–7.0% band, not the higher headline rates.
Segmentation runs on three axes — product chemistry, deposition technology and end-use vertical — with chemistry and technology jointly determining price and qualification burden.
| Parent segment | Children |
|---|---|
| By Product Type | Oxide Coatings (Alumina, Zirconia, Titania); Carbide Coatings (Tungsten Carbide, Titanium Carbide, Silicon Carbide); Nitride Coatings (Titanium Nitride, Silicon Nitride, Aluminum Nitride) |
| By Technology | Thermal Spray; Physical Vapor Deposition; Chemical Vapor Deposition; Other Technologies (sol-gel, anodizing) |
| By End-User | Automotive; Aviation (Aerospace & Defense); Chemical Equipment; Healthcare; Energy & Power; Other End Users |
| By Distribution Channel | OEM; Aftermarket |
Oxide coatings hold the largest share because alumina and zirconia deliver acceptable corrosion and thermal performance at materially lower cost than carbides. Carbide and nitride coatings grow faster in percentage terms but from a smaller base, constrained by raw-material cost and plasma-spray capital intensity. Our analysis suggests thermal spray's ~75% technology share is durable through 2030, but PVD and CVD gain share in semiconductor, medical and precision aerospace niches where sub-micron thickness control matters more than deposition rate.
Asia Pacific leads with roughly 41% of global revenue, driven by concentrated automotive and aerospace manufacturing in China, Japan, India and South Korea, while North America remains the technology and service hub.
| Region | Market Share (%) |
|---|---|
| North America | 0.27% |
| Europe | 0.22% |
| Asia-Pacific | 0.41% |
| South America | 0.04% |
| Middle East & Africa | 0.06% |
| Region | 2026 share | Growth posture |
|---|---|---|
| Asia Pacific | 41% | Largest and fastest-growing |
| North America | 27% | Stable mid-single-digit CAGR |
| Europe | 22% | Moderate, regulation-led |
| Middle East & Africa | 6% | Energy and industrial capex driven |
| South America | 4% | Emerging, automotive-led |
The regional dispersion implies a structural split: demand volume sits in Asia Pacific, but premium-priced, specification-heavy work still clears in North America and Europe. Vendors must therefore plan dual footprints — low-cost capacity near Asian OEMs and certified application labs near Western aerospace and medical customers.
EV component protection, aerospace thermal management and equipment lifecycle extension are the dominant growth engines, while high deposition cost and raw-material availability cap near-term adoption in price-sensitive segments.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| EV component and battery enclosure protection | Driver | High | Thermal barrier and corrosion coatings on lightweight substrates extend pack life |
| Aerospace thermal barrier demand | Driver | High | Turbine and engine coatings required for efficiency and safety certification |
| Equipment lifecycle extension in energy and chemicals | Driver | Medium-High | Coatings cut maintenance downtime and replacement spend |
| Plasma spray and CVD capital intensity | Restraint | High | High equipment cost limits adoption among mid-tier coaters |
| Zirconia, alumina and SiC raw-material availability | Restraint | Medium | Supply concentration creates price volatility |
| Environmental emissions from coating processes | Restraint | Medium | VOC and energy use invite tighter permitting |
The balance favors growth: three independent demand-side drivers pull simultaneously from automotive, aerospace and energy, while the restraints are cost and supply frictions rather than demand destruction. Our analysis suggests the binding constraint through 2028 is qualified application capacity, not coating material supply — meaning coater capacity announcements are the leading indicator to watch.
The competitive field splits into diversified industrial coaters, specialty ceramic formulators and application-service specialists, with moats built on certification and process know-how rather than raw material control.
| Company | Primary position | Differentiation |
|---|---|---|
| Bodycote plc | Thermal processing and coating services | Global plant network, aerospace qualifications |
| Oerlikon Metco AG | Thermal spray equipment and materials | Integrated equipment-plus-powder offer |
| Saint-Gobain S.A. | Ceramic materials and coatings | Materials science depth, scale |
| Aremco Products Inc. | Specialty ceramic adhesives and coatings | High-temperature niche formulations |
| APS Materials Inc. | Thermal spray coating services | Medical and aerospace implant coatings |
| Keronite Group | Plasma electrolytic oxidation | Light-metal surface engineering |
| Zircotec Ltd. | Thermal barrier coatings | EV and motorsport thermal management |
| A&A Coatings | Contract thermal spray | Regional service breadth |
Differentiation rests on three moats: OEM qualification status, which creates multi-year switching costs; application engineering capability, which converts a commodity powder into a specified process; and substrate breadth, which lets a coater serve metal, composite and plastic programs. Our analysis suggests consolidation pressure will build among sub-scale contract coaters as EV and aerospace buyers demand single-source qualification.
Buyers should select on qualified process capability, not coating chemistry alone. The same alumina formulation performs very differently across plasma spray, HVOF and sol-gel routes, so specification must be tied to a validated deposition process and coupon-tested against the actual service environment.
Procurement risk concentrates in three areas: single-source qualification, where a coater failure halts a production line; thickness and porosity tolerance, which drives scrap and rework cost; and regulatory exposure from process emissions and restricted substances. Switching costs are high — requalification for aerospace and medical programs typically runs six to eighteen months — which argues for early dual-sourcing on critical part families. Operators should also verify that coating suppliers can document thermal cycling and corrosion test data traceable to recognized standards, and should build raw-material price pass-through clauses into multi-year agreements given zirconia and SiC volatility.
The balance of evidence favors a 6.5–7.0% CAGR through 2030, with the High Performance Ceramic Coatings market reaching roughly 14.8 Billion. The strongest counter-argument is that broad ceramic-coating estimates near 7.4–8.3% capture adjacent industrial and detailing demand; if those adjacencies convert into specification-grade HPCC volume faster than expected, the higher band becomes defensible. We weight that risk as moderate, not base case.
The decisive strategic shift is qualification-led value migration. Commodity oxide spray work will face price pressure as Asian capacity expands, while EV thermal barriers, battery enclosure coatings and aerospace TBCs command premium pricing backed by certification. Vendors that invest in test data, application engineering and OEM qualification will capture disproportionate margin; those that compete on deposition throughput alone will see compression.
Actionable strategy:
Evidence that would change this conclusion: a sustained acceleration in carbide and nitride adoption in mainstream automotive, or a step-change decline in plasma spray capital cost that unlocks mid-tier coater capacity faster than projected.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.9% from 2020-2034 |
| Segmentation |
|
The global market is valued at approximately 11.34 Billion in 2026, growing from 10.65 Billion in 2025 and projected to reach 14.78 Billion by 2030 at a 6.9% compound annual growth rate.
Asia Pacific leads with roughly 41% of global revenue, supported by concentrated automotive and aerospace manufacturing in China, Japan, India and South Korea. North America remains the technology and service hub for specification-grade work.
Carbide and nitride coatings grow fastest in percentage terms, and aerospace & defense is the fastest-growing end-use vertical. EV component and battery enclosure protection is the fastest-growing application pocket within automotive.
Major players include Bodycote, Oerlikon Metco, Saint-Gobain, Aremco Products, APS Materials, Keronite Group, Zircotec and A&A Coatings, alongside regional contract thermal spray specialists.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with raw material and ceramic powder suppliers, specialized coating producers, contract formulators and application houses, and global industrial distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring demand-side and supply-side perspectives are captured in equal measure.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Ceramic Powder & Raw Material Suppliers | 40% |
| Specialized Coating Producers & Application Houses | 35% |
| Industrial Distributors & Traders | 25% |
Findings were benchmarked against official multilateral trade and standards databases including UN Comtrade, WTO tariff schedules, US ITC trade data and Eurostat chemical and advanced-materials flows. Corporate annual filings (10-K and investor presentations), patent databases and recognized technical standards bodies were used to validate capacity, pricing and technology adoption assumptions.
Top-down macroeconomic and industry-segment allocation was run simultaneously with bottom-up manufacturer capacity, product pricing and end-use consumption modeling. Divergences between the two approaches were reconciled at the segment and regional level before finalizing the base-year value and forecast path.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |