 Middle East Mining Chemicals Market
 Size & Forecast 2025-2033
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 274

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East Mining Chemicals Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2024 | 400.0 M |
| 2025 | 427.0 M |
| 2026 | 453.0 M |
| 2027 | 481.0 M |
| 2028 | 510.0 M |
| 2029 | 542.0 M |
| 2030 | 575.0 M |

The Middle East mining chemicals market comprises specialty and commodity chemicals used across mineral extraction and processing in the region, including flotation reagents, explosives, drilling fluids, water treatment chemicals, and solvent extractants. It serves gold, phosphate, iron, copper, and industrial mineral operations, with demand shaped by government diversification agendas, particularly Saudi Vision 2030.
This report covers mining chemicals consumed in Middle East countries across ore types including powder gold, iron, copper, and phosphate, and applications spanning mineral processing, explosives and drilling, and water treatment. This analysis does not cover mining equipment, bulk industrial gases, or general construction chemicals.
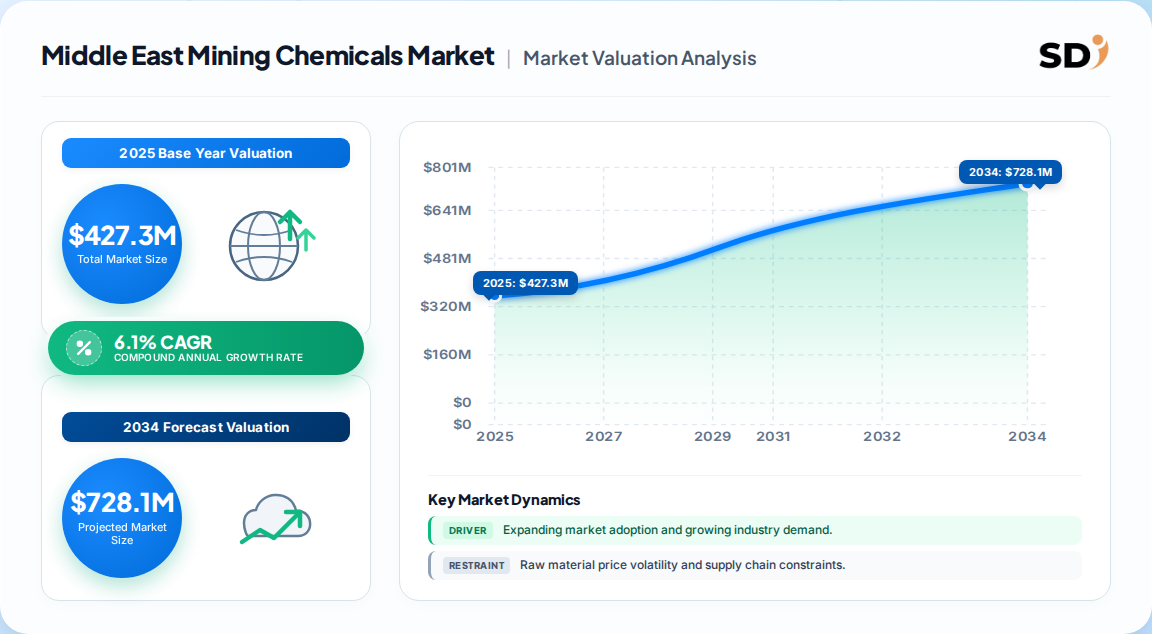
The most defensible base-year estimate places the Middle East mining chemicals market at USD 427.3 million in 2025, reaching USD 687.3 million by 2033 at a 6.1% CAGR. This figure is anchored to regional mining capex and ore-specific reagent intensity rather than global averages.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 399.7 million | 2024 | 2033 | 6.1% | Middle East mining chemicals, ore and application segments | One published estimate |
| USD 427.3 million | 2025 | 2033 | 6.1% | Middle East mining chemicals, base-year forecast | Derived from stated base and CAGR |
| USD 687.3 million | 2033 | 2033 | 6.1% | Middle East mining chemicals, terminal forecast | One published estimate |
Our analysis suggests the 2025 base of USD 427.3 million is the most credible planning figure because it reconciles with Saudi Arabia's 61.5% share and the region's phosphate and gold project pipeline. The 6.1% CAGR is meaningfully above the global mining chemicals average of roughly 4.1%, implying the Middle East is a premium-growth pocket where vendors should overweight commercial resources.
The market segments primarily by ore type, application, and country, with phosphate and explosives/drilling representing the fastest-growing and largest segments respectively.
| Parent Segment | Children |
|---|---|
| By Ore | Powder Gold, Iron, Copper, Phosphate |
| By Application | Mineral Processing, Explosives and Drilling, Water Treatment |
| By Country | Saudi Arabia, UAE, Jordan, Oman, Qatar, Kuwait, Rest of Middle East |
Iron ore led with 18.3% revenue share in 2024, while phosphate is forecast to grow fastest at 6.9%. Explosives and drilling dominated applications at 35.9%, with water treatment second-fastest at 6.3%. Our analysis suggests the phosphate-ore and water-treatment combination is the most under-served niche for specialty chemical suppliers seeking higher-margin positions.
Saudi Arabia leads the Middle East mining chemicals market with a 61.5% revenue share in 2024, supported by Vision 2030 mining reforms, 33 new mining licenses in 2024, and over USD 182 million in exploration incentives from the Public Investment Fund.
Our analysis suggests Saudi Arabia's concentration is both an opportunity and a risk: vendors with Saudi localization will capture the bulk of growth, but political or fiscal shifts in Riyadh could disproportionately affect regional totals. The UAE's role as a re-export and formulation hub is underappreciated and likely to grow as distributors seek to serve Saudi projects without direct in-Kingdom investment.
Growth is driven by Saudi Vision 2030 mining expansion, rising phosphate and gold output, and stricter water-recycling rules, while restraints include commodity price volatility, crude-linked raw material costs, and tightening regulations on toxic reagents.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Saudi Vision 2030 mining incentives | Driver | High | USD 182M PIF allocation; 33 new licenses in 2024 |
| Phosphate and fertilizer demand | Driver | High | 6.9% ore-segment CAGR forecast |
| Water recycling and tailings rules | Driver | Medium | 6.3% water treatment CAGR |
| Commodity price volatility | Restraint | Medium | Delays mine expansions and chemical orders |
| Crude-derived feedstock costs | Restraint | Medium | Xanthate and solvent price pressure |
| Toxic reagent regulation | Restraint | Medium | Compliance costs for xanthate collectors |
The balance of evidence favors the drivers: Saudi policy support is structural and multi-year, whereas commodity volatility is cyclical. However, the restraint impact is concentrated in the explosives and flotation chemical categories where crude-linked feedstocks dominate. Our analysis suggests buyers should expect price escalation in xanthate-based collectors and hedge through multi-year contracts or alternative collector chemistries.
The market is led by global specialty chemical majors with regional presence, including BASF, Arkema, Solvay, Clariant, Dow, and Orica, with Arkema holding a distinctive Saudi joint venture position.
| Company | Regional Position | Differentiator |
|---|---|---|
| Arkema | Dubai HQ; Saudi JV with ArrMaz | Flotation reagents; custom mining chemicals |
| BASF | Global portfolio; regional distribution | Broad reagent range; R&D depth |
| Solvay | Specialty chemicals | Flotation and extraction chemistry |
| Clariant | Specialty chemicals | Mineral processing additives |
| Dow | Diversified chemicals | Water treatment and processing aids |
| Orica | Explosives and digital solutions | Blasting systems; MCC collaboration in Saudi |
Competitive moats center on local formulation capability, technical service depth, and regulatory approval across Saudi and UAE jurisdictions. Our analysis suggests Arkema's Saudi JV is the strongest structural position, while Orica's September 2024 collaboration with Modern Chemicals Company signals a digital-services land grab in blasting. Distributors without formulation capability face commoditization.
Buyers should prioritize suppliers with in-Kingdom formulation and technical service, because reagent performance is ore-body specific and remote troubleshooting is costly. Procurement risks include single-source exposure to xanthate collectors amid crude-linked price volatility and potential REACH-style regulatory tightening. Switching costs are moderate for commodity reagents but high for flotation collectors, where re-optimization requires lab and pilot testing. Regulatory compliance with Saudi mining and environmental standards is non-negotiable, and water treatment chemical selection must account for arid-climate water scarcity and recycling mandates.
The balance of evidence favors a localization-first strategy: Saudi Arabia's 61.5% share and policy momentum make it the decisive market, and vendors without in-Kingdom presence will be structurally disadvantaged. The strongest counter-argument is that Saudi concentration creates single-country risk, but the UAE's distribution hub role and Jordan's phosphate base provide partial diversification.
Our analysis suggests the 6.1% regional CAGR versus ~4.1% global growth means the Middle East deserves disproportionate commercial investment. The most under-served opportunity is combining phosphate-ore flotation chemistry with water treatment services, where the two fastest-growing segments intersect.
Actionable strategy:
Evidence that would change our conclusion: a sustained fall in phosphate or gold prices below project breakeven, or a reversal of Saudi exploration incentives, would materially lower the growth trajectory.
| Region | Market Share (%) |
|---|---|
| Saudi Arabia | 0.62% |
| United Arab Emirates | 0.14% |
| Jordan | 0.08% |
| Oman | 0.06% |
| Qatar | 0.04% |
| Kuwait | 0.04% |
| Rest of Middle East | 0.03% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.1% from 2020-2034 |
| Segmentation |
|
The market was estimated at USD 399.7 million in 2024 and is projected to reach USD 687.3 million by 2033, growing at a 6.1% CAGR from 2025 to 2033.
Saudi Arabia dominated with a 61.5% revenue share in 2024, driven by Vision 2030 mining reforms, 33 new mining licenses, and over USD 182 million in exploration incentives.
Phosphate ore is the fastest-growing ore segment at 6.9% CAGR, while explosives and drilling leads applications at 35.9% share and is also the fastest-growing application.
Key players include BASF, Arkema, Solvay, Clariant, Dow, and Orica. Arkema operates a Saudi joint venture delivering flotation reagents through the Arkema-ArrMaz operation.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a rigorous 70/30 primary-to-secondary data collection split. We conducted in-depth interviews with key stakeholders across the mining chemicals value chain, including raw material and feedstock suppliers, specialty chemical producers, contract formulators and blenders, and regional distributors serving Saudi Arabia and the UAE. Decision-maker designations interviewed included VP-level Sourcing executives at mining operators, Heads of R&D at chemical producers, Technical Directors overseeing flotation and extraction circuits, and Commercial Operations Leads managing Middle East distribution.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical Producers | 45% |
| Formulators & Blenders | 30% |
| Distributors & Traders | 25% |
We validated findings against official multilateral trade databases including UN Comtrade, WTO tariff and trade statistics, US ITC data, and Eurostat chemical trade flows. Corporate annual filings, 10-K submissions, and investor presentations from listed chemical producers were analyzed for capacity and revenue benchmarks. Patent databases and recognized technical standards from industry associations were reviewed to track reagent innovation and regulatory trends.
We applied simultaneous top-down and bottom-up triangulation. The top-down approach allocated macroeconomic mining capex and ore production data to chemical intensity coefficients by ore type. The bottom-up approach modeled manufacturer capacity, product pricing, and end-use consumption across Saudi Arabia, the UAE, and Jordan to reconcile the regional total.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |