 Poland Fiber Laser Cutting Machines Market
 2026 Overview
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 181

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Poland Fiber Laser Cutting Machines Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 28.00 M |
| 2026 | 29.00 M |
| 2027 | 31.00 M |
| 2028 | 33.00 M |
| 2029 | 35.00 M |
| 2030 | 37.00 M |
| 2031 | 39.00 M |

The Poland fiber laser cutting machines market comprises the sale, deployment, and servicing of fiber laser-based cutting systems used in metal fabrication across automotive, aerospace, medical device, and electronics manufacturing. It covers 2D flatbed and 3D five-axis configurations, measured by vendor revenue in USD.
This report covers fiber laser cutting machines sold into Poland across 2D and 3D types and end-use segments including automotive, medical devices, aerospace and defense, and electrical and electronic components. It includes hardware, embedded control software, and basic installation services. This analysis does not cover CO₂ laser systems, plasma or waterjet cutting, laser welding or marking equipment, or aftermarket consumables and spare parts.
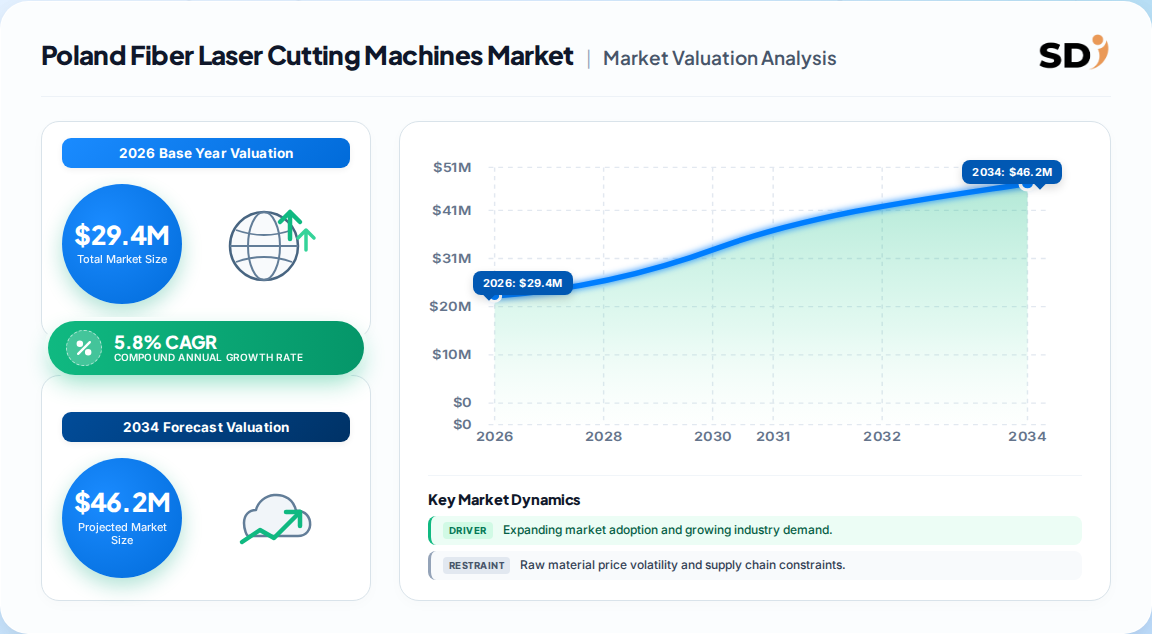
The most defensible estimate places the Poland market at $27.8 million in 2025, rising to $29.4 million in 2026 and $43.7 million by 2033 at a 5.8% CAGR, based on a country-specific bottom-up model.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| $27.8M → $43.7M | 2025 | 2026–2033 | 5.8% | Poland-only, fiber laser cutting machines, vendor revenue | One published country-specific estimate |
| $6.8B → $16.9B (global) | 2025 | 2026–2035 | 9.6% | Global laser cutting machines, all technologies | A competing global analysis |
| ~$577.6M (Germany, 2029) | 2022 | 2023–2029 | 4.8% (Europe) | Europe laser cutting machines, all technologies | A regional market study |
The Poland-specific figure is the most defensible for this scope because it isolates fiber laser cutting machines sold into Poland rather than blending technologies or geographies. However, the 5.8% CAGR sits below the global 9.6% laser cutting forecast, implying Poland's market is maturing faster than emerging regions. Our analysis suggests this divergence reflects Poland's already-high manufacturing automation base rather than weak demand.
The market segments primarily by machine type (2D vs. 3D) and by end-use industry, with 2D flatbed systems dominating revenue while 3D systems serve complex aerospace and automotive geometries.
| Parent Segment | Children |
|---|---|
| By Type | 2D Fiber Laser Cutting Machines, 3D Fiber Laser Cutting Machines |
| By End Use | Automotive, Medical Devices, Aerospace & Defense, Electrical & Electronic Components |
2D machines held approximately 78.0% of 2025 revenue due to their lower cost, ease of operation, and suitability for high-volume sheet metal cutting. The 3D segment, while smaller, is expected to advance at the fastest CAGR through 2033 as Polish manufacturers invest in five-axis systems for complex part geometries and waste reduction.
The automotive segment accounted for the largest revenue share in 2025, driven by Poland's role as one of Europe's largest vehicle and electric bus manufacturing hubs.
Poland's automotive industry — a major exporter of electric buses, vehicle parts, and battery components — generates sustained demand for high-precision, high-throughput cutting systems. Aerospace and defense is the second-most-valuable segment, benefiting from Poland's growing defense budget and aerospace supply chain. Medical devices and electrical/electronic components represent smaller but higher-margin opportunities where precision and traceability matter more than volume. Our analysis suggests the automotive segment will remain dominant through 2033, but the 3D machine segment's faster growth signals rising demand for complex-geometry cutting in aerospace and EV battery enclosure production.
Automation and Industry 4.0 adoption are the primary growth drivers, while high capital costs and skilled-labor shortages are the principal restraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Automation & Industry 4.0 adoption | Driver | High | Smart factory integration increases demand for connected cutting cells |
| High-precision fabrication demand | Driver | High | Automotive and aerospace require tighter tolerances and narrower kerf |
| Energy-efficient fiber vs. CO₂ shift | Driver | Medium | 30–40% wall-plug efficiency vs. 8–12% for CO₂ lowers operating costs |
| Customization and personalization trend | Driver | Medium | Precise, intricate cutting enables bespoke product manufacturing |
| High initial equipment and integration costs | Restraint | High | Limits adoption among SMEs with variable job mixes |
| Skilled operator shortage | Restraint | Medium | Increases training and service dependency |
The balance of evidence favors continued growth, but the restraint impact is asymmetric: large automotive and aerospace suppliers will absorb capital costs, while SMEs may defer purchases. This implies vendors offering modular, scalable automation and financing options will capture disproportionate share of the SME segment.
The Poland market is served by global leaders — Trumpf, Bystronic, Amada, Mazak, Han's Laser, and IPG Photonics — alongside regional specialists such as Seron and EAGLE Group.
| Company | Specialization | Notable Innovation | Estimated Revenue |
|---|---|---|---|
| Trumpf | High-power 2D and 3D cutting | BrightLine ultra-high-brightness fiber lasers | ~€5.4B (group) |
| Bystronic | Automated sheet metal fabrication | AI-driven nesting software | ~CHF 1B |
| Amada | Integrated fiber laser + turret punch | High-production press-brake systems | ~$400M (est.) |
| Mazak | Multi-tasking cutting and milling | Integrated turning centers | ~$3.5B (group) |
| Han's Laser | Cost-efficient high-power systems | Compact fiber lasers with integrated chiller | ~$1.2B (est.) |
| IPG Photonics | Fiber laser sources and complete systems | Multi-kW single-mode lasers | ~$1.4B |
Differentiation rests on automation integration, service network depth, and total cost of ownership rather than laser wattage alone. Trumpf and Bystronic lead on high-power automated systems, while Han's Laser competes aggressively on price-performance. Regional players like Seron and EAGLE Group leverage trade-show presence (STOM-LASER, STOM-BLECH & CUTTING Expo) and local service to defend share.
Buyers should prioritize automation compatibility, service coverage, and part-level operating economics over nominal laser power. The installed cost extends well beyond the machine frame: automation modules, extraction, compressed gases, nesting software, and operator training can materially increase capital commitment. Procurement risk is highest for SMEs with variable job mixes, where utilization may not justify highly automated cells. Switching costs are significant because fiber laser platforms integrate with upstream nesting software and downstream bending and inspection; a machine that cannot interoperate constrains automation ROI. Regulatory compliance — CE marking, laser safety classifications, and energy-efficiency standards — is non-negotiable for EU deployment. Our analysis suggests buyers should demand part-level energy, throughput, and maintenance comparisons from vendors rather than comparing wattage alone.
The balance of evidence favors a cautiously optimistic outlook: Poland's fiber laser cutting machines market will grow at a steady 5.8% CAGR through 2033, underpaced by the global laser cutting market but underpinned by durable automotive and aerospace demand. The strongest counter-argument is that SME financing constraints and skilled-labor shortages could suppress adoption below forecast, particularly if EU industrial subsidies tighten. However, the structural shift from CO₂ to fiber — driven by 30–40% wall-plug efficiency and lower maintenance — provides a replacement-demand floor that limits downside.
Our analysis suggests the most attractive opportunities lie in modular automation for SMEs and 3D systems for aerospace and EV battery applications. Vendors competing on laser wattage alone will face margin compression as Chinese entrants such as Han's Laser drive price competition. Service network depth and application engineering will become the primary moats.
Actionable Strategy:
What evidence would change this conclusion: a sustained decline in Polish automotive production, a sharp rise in EU energy costs that undermines fiber's efficiency advantage, or accelerated Chinese price competition that compresses vendor margins below sustainable levels.
| Region | Market Share (%) |
|---|---|
| 2D Fiber Laser Cutting Machines | 0.78% |
| 3D Fiber Laser Cutting Machines | 0.22% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.8% from 2020-2034 |
| Segmentation |
|
The market was valued at $27.8 million in 2025 and is projected to reach $43.7 million by 2033, growing at a 5.8% CAGR from 2026 to 2033.
2D fiber laser cutting machines held approximately 78% of 2025 revenue, driven by their cost-effectiveness and suitability for high-volume sheet metal cutting.
Key vendors include Trumpf, Bystronic, Amada, Mazak, Han's Laser, IPG Photonics, and regional specialists such as Seron and EAGLE Group.
Growth is driven by industrial automation, Industry 4.0 adoption, high-precision fabrication demand in automotive and aerospace, and the shift toward energy-efficient fiber lasers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employed a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the fiber laser cutting value chain: laser source and component suppliers, machine OEMs, system integrators, and industrial distributors operating in Poland. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads at Polish fabricators and OEMs.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Machine OEMs & System Integrators | 45% |
| Laser Source & Component Suppliers | 30% |
| Industrial Distributors & Service Providers | 25% |
We validated findings against official multilateral trade databases (UN Comtrade, Eurostat), corporate annual filings and investor presentations (10-K, annual reports), patent databases, and recognized technical standards bodies including ISO and CEN. Trade flow data for laser cutting machinery (HS code 8456) was cross-referenced with Polish customs statistics and Eurostat industrial production indices.
Market sizing was triangulated using simultaneous top-down and bottom-up approaches. Top-down modeling allocated Polish manufacturing GDP and metal fabrication output to fiber laser cutting equipment. Bottom-up modeling aggregated manufacturer capacity, product pricing, and end-use consumption across automotive, aerospace, medical, and electronics segments.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |