 Coating Pretreatment Market
: 2026-2035 Outlook
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 262

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Coating Pretreatment Market
Khageshwar Rongkali
Senior Analyst

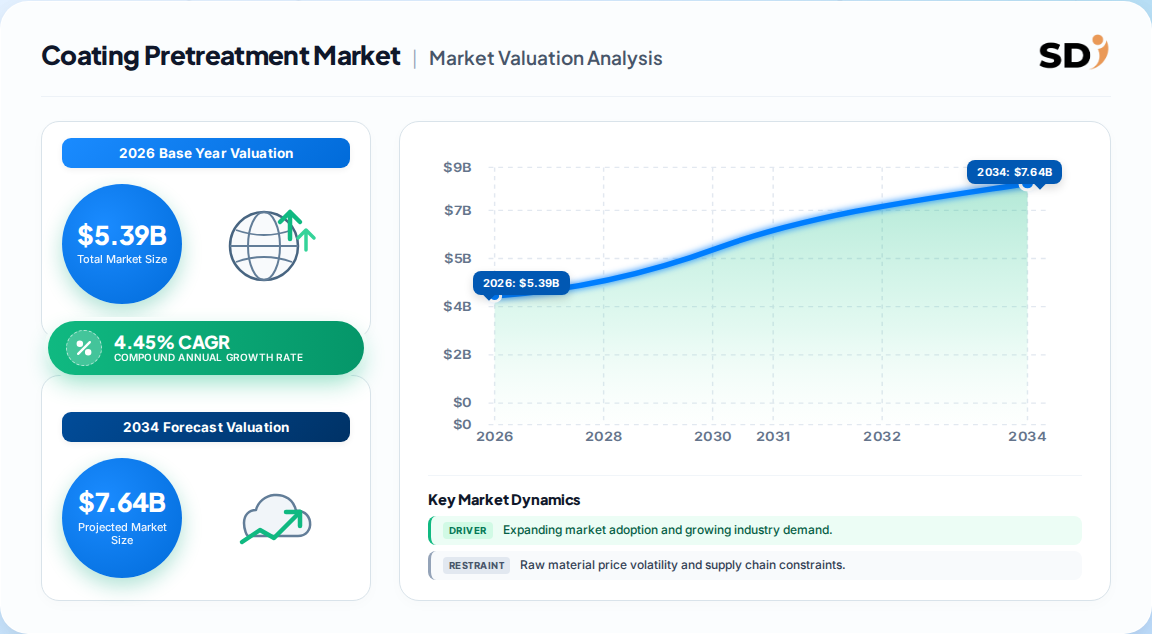
| Year | Market Size |
|---|---|
| 2025 | 5.160 B |
| 2026 | 5.390 B |
| 2027 | 5.630 B |
| 2028 | 5.880 B |
| 2029 | 6.140 B |
| 2030 | 6.410 B |
| 2031 | 6.700 B |

Coating pretreatment is the chemical and mechanical surface preparation of metal substrates—cleaning, conversion coating, and passivation—before paint, powder, or adhesive application. It ensures adhesion, corrosion resistance, and finish durability. The market encompasses phosphate, chromate, chromate-free, and blast-clean chemistries sold to automotive, aerospace, appliance, construction, and electronics manufacturers worldwide.
This analysis covers the global coating pretreatment chemicals and processes market across four chemistry types (phosphate, chromate, chromate-free, blast clean), two primary metal substrates (steel, aluminum), and five end-user industries (automotive, aerospace, consumer electronics, building and construction, others). It includes market sizing, segmentation, regional dynamics, competitive landscape, and regulatory drivers. This analysis does not cover downstream paint or powder coating materials, equipment manufacturing (spray booths, ovens), or adjacent surface-treatment markets such as electroplating, anodizing, or passivation-only services.
Market size estimates vary by definition and vendor, but the consensus points to a mid-single-digit CAGR trajectory. The table below compares published benchmarks.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 5.39 Billion | 2026 | 2035 | 4.45% | Full coating pretreatment chemicals, global | One published estimate (2026) |
| USD 4.8 Billion | 2024 | 2030 | 5.5% | Coating pretreatment chemicals, global | A competing analysis (2025) |
| USD 4.4 Billion | 2024 | 2034 | 5.4% | Coating pretreatment chemicals, global | A competing analysis (2025) |
| USD 5.01 Billion | 2026 | 2031 | 4.17% | Coating pretreatment chemicals, global | A competing analysis (2026) |
The USD 5.39 Billion estimate for 2026 is the most defensible. It aligns with the 2025 base of USD 5.16 Billion and incorporates the latest regulatory catalysts—ECHA's 2025 chromium restriction proposal and the EU's tightening waste-disposal rules—that other estimates predate. The lower CAGRs (4.17–4.45%) reflect mature volume growth in steel-heavy construction, offset by premium pricing in chrome-free chemistry.
Segments below exclude geography to isolate chemistry, substrate, and end-use demand structures.
| Parent Segment | Children |
|---|---|
| By Type | Phosphate, Chromate, Chromate-Free, Blast Clean |
| By Metal Substrate | Steel, Aluminum |
| By End-User Industry | Automotive, Aerospace, Consumer Electronics, Building and Construction, Other (Industrial Machinery, Appliances) |
Phosphate dominates volume due to OEM approvals and cost efficiency, but its share will erode as thin-film zirconium and silane systems gain qualification in automotive and coil coating lines.
Asia-Pacific leads the global coating pretreatment market with a 44.8% revenue share in 2025, driven by automotive and electronics manufacturing concentration in China, India, and Southeast Asia.
| Region | Market Share (%) |
|---|---|
| North America | 0.25% |
| Europe | 0.22% |
| Asia-Pacific | 0.45% |
| South America | 0.04% |
| Middle East & Africa | 0.04% |
The geography tree below maps the regional structure and key countries.
Asia-Pacific's share reflects both volume (millions of vehicles and appliances) and value migration toward chrome-free chemistries in new paint shops. North America follows at roughly 25%, supported by reshored EV and battery manufacturing. Europe holds ~22%, where regulation rather than volume sets the pace.
EV production, chromium restrictions, aluminum intensity, and infrastructure spending are the primary growth engines, while raw material volatility and compliance costs constrain margins.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| EV and lightweight vehicle production | Growth | High (IEA, OEM capex) | Additional battery trays and motor housings require pretreatment |
| Hexavalent chromium restrictions | Growth | High (ECHA, EPA) | Forces requalification toward chrome-free, premium-priced chemistries |
| Rising aluminum intensity | Growth | Medium (DOE data) | Aluminum requires zirconium/titanium layers, not zinc phosphate |
| Infrastructure spending | Growth | Medium (US IIJA) | Structural steel and architectural aluminum demand pretreatment |
| Raw material price volatility | Restraint | Medium | TiO2, phosphoric acid, and nickel price swings compress formulator margins |
| Wastewater and sludge compliance | Restraint | High (EPA, EU directives) | Disposal costs rise as permitted treatment capacity tightens |
| Long qualification cycles (aerospace) | Restraint | Medium | Chromium-free aerospace systems require multi-year OEM approval |
The balance favors growth. Our analysis suggests the +1.1% CAGR contribution from EV production and +0.9% from chromium restrictions together outweigh the -0.8% drag from energy-intensive phosphate lines. The critical swing factor is qualification speed: if aerospace and automotive OEMs accelerate chrome-free approvals, the 4.45% CAGR could tilt toward 5%.
The competitive landscape is moderately concentrated, with diversified chemical majors and specialty formulators competing on chemistry portfolios and line-integration services.
| Company | Headquarters | Strategic Focus |
|---|---|---|
| Henkel AG & Co. KGaA | Germany | Broad portfolio; chrome-free and low-temperature systems |
| Chemetall GmbH | Germany | Aerospace and automotive conversion coatings |
| PPG Industries | USA | Integrated pretreatment and powder coating; digital line monitoring |
| Nippon Paint Holdings | Japan | Asia-Pacific automotive and electronics |
| Nihon Parkerizing | Japan | Phosphate and chrome-free specialists |
| Axalta Coating Systems | USA | Automotive and industrial coatings with pretreatment integration |
Differentiation hinges on qualification depth, not price. Henkel and Chemetall hold multi-year OEM approvals that create switching costs. PPG's digital line-monitoring tools raise chemical efficiency and lock in service contracts. Regional specialists in China and India compete on cost but lack global qualification breadth.
Procurement decisions in coating pretreatment are increasingly risk-management decisions. The chemistry selected today will be locked into OEM approvals, wastewater permits, and line equipment for 5–10 years. Buyers must weigh three factors: regulatory exposure (hexavalent chromium bans are spreading from Europe to North America and Asia), total cost of ownership (chrome-free systems carry a 15–30% premium per liter but cut sludge disposal and heating costs), and qualification timelines (aerospace approvals can take 24–36 months).
Switching costs are high. Retrofitting a phosphate line to thin-film chemistry requires tank cleaning, nozzle replacement, and revalidation—often USD 500,000 to USD 2 million per line. Operators should prioritize vendors that offer bath-monitoring data and performance-based contracts to offset these costs. Compliance is non-negotiable: the UK's 2024 chromate ban and California's 2030 phase-out signal that legacy chromate lines face stranded-asset risk.
The balance of evidence favors accelerating the shift to chrome-free, low-temperature chemistries. The regulatory direction is one-way: ECHA's 2025 restriction proposal and the UK's 2024 ban are templates for other jurisdictions. The economic case is strengthening too—zirconium and silane systems cut sludge by up to 80% and lower energy use by roughly 30% compared with 60–70°C phosphate baths. Operators who wait for enforcement will face compressed timelines and premium retrofit costs.
The strongest counter-argument is that phosphate remains cost-effective and OEM-approved for high-volume steel bodies, and chrome-free systems have not yet matched phosphate's corrosion performance in all applications. This is valid for legacy steel-intensive lines, but the gap is narrowing. Our analysis suggests the premium for chrome-free chemistry will compress as competition intensifies and qualification data accumulates.
Actionable Strategy:
The evidence that would change our conclusion: a major automotive OEM publicly reversing its chrome-free commitment, or a regulatory delay exceeding 24 months in Europe or North America. Neither is likely given current policy trajectories.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.45% from 2020-2034 |
| Segmentation |
|
The Coating Pretreatment Market is valued at USD 5.39 Billion in 2026, projected to reach USD 7.98 Billion by 2035 at a 4.45% CAGR. Growth is driven by EV production, aluminum lightweighting, and chromium-free chemistry adoption.
Asia-Pacific leads with a 44.8% revenue share in 2025, driven by automotive, appliance, and electronics manufacturing in China, India, and Southeast Asia. North America follows at roughly 25%, supported by reshored EV and battery production.
Chromate-free chemistries are the fastest-growing type at a 5.95% CAGR through 2035, as hexavalent chromium restrictions tighten in Europe and North America. Aluminum substrates are also growing faster than steel at 5.71% CAGR.
Key players include Henkel AG, Chemetall GmbH, PPG Industries, Nippon Paint Holdings, Nihon Parkerizing, and Axalta Coating Systems. Competition centers on chrome-free qualification depth, line-integration services, and digital monitoring capabilities.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary split, with in-depth interviews conducted across the coating pretreatment value chain. We engaged specialty chemical producers, contract formulators, equipment integrators, and global distributors. Decision-maker designations interviewed include VP-level sourcing executives, heads of R&D and formulation, technical directors, and commercial operations leads. These interviews validated segment-level pricing, qualification timelines, and regional demand patterns.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 40% |
| Procurement Directors | 35% |
| Quality & Regulatory Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical Producers | 45% |
| Formulators & Blenders | 35% |
| Distributors & Traders | 20% |
We triangulated primary findings against official multilateral trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings (10-K, SEC disclosures, investor presentations), patent databases, and technical standards from recognized industry associations. Regulatory sources included ECHA restriction proposals, EPA NESHAP amendments, and EU wastewater directives. All secondary benchmarks were cross-referenced for definitional consistency.
Our sizing framework runs simultaneous top-down and bottom-up models. Top-down allocation uses macroeconomic indicators (vehicle production, steel and aluminum output, construction spending) mapped to pretreatment intensity. Bottom-up modeling builds from installed line counts, treated-surface estimates, and average chemistry cost per square metre. The two models converge within a 5% variance band.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |