 Middle East Steel Wire Market
 Size, Trends & Forecast to 2033
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 268

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East Steel Wire Market
Khageshwar Rongkali
Senior Analyst

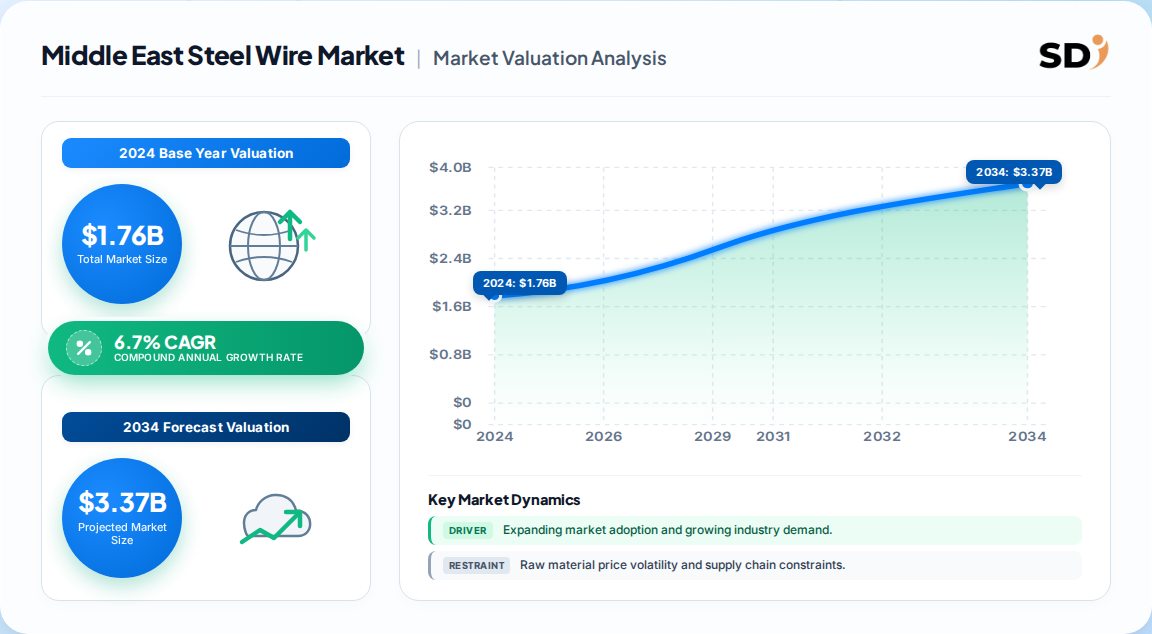
| Year | Market Size |
|---|---|
| 2024 | 1.760 B |
| 2025 | 1.880 B |
| 2026 | 2.000 B |
| 2027 | 2.140 B |
| 2028 | 2.280 B |
| 2029 | 2.440 B |
| 2030 | 2.600 B |

The Middle East steel wire market covers the manufacture, import and distribution of drawn steel wire products — carbon, alloy and stainless — used in construction reinforcement, binding, fasteners, automotive components, energy cabling, fencing and industrial rope. It spans GCC economies plus Turkey, Iran, Iraq, Israel and Oman, serving both domestic megaprojects and re-export trade.
This analysis covers steel wire across carbon, stainless and alloy materials, spanning construction, automotive, agriculture, energy and industrial applications, across the Middle East including GCC states, Turkey, Iran, Iraq, Israel and Oman. Both domestic production and intra-regional trade flows are evaluated. This analysis does not cover flat steel, structural sections, seamless pipe, or non-ferrous wire such as copper and aluminium conductors.
Published estimates converge on a market in the high-hundreds of millions to low-billions of dollars, but definitions differ sharply — some count only drawn wire, others fold in stranded rope and cable. The table below isolates the divergence.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 1,760.6 Million | 2024 | 2033 | 6.7% | Drawn steel wire, carbon/stainless/alloy, five applications | One published industry estimate |
| ~717 Million | 2024 | 2035 | 1.1% | Stranded wire, ropes and cables only | Trade-statistics aggregator |
| ~45,012 Million | 2025 | 2034 | 4.2% | Total Middle East steel, all product forms | A second published analysis |
| ~74,850 Million | 2025 | 2034 | 5.5% | Middle East & Africa steel, all products | A third published analysis |
The 1,760.6 Million figure is the most defensible for wire specifically: it aligns with the narrow stranded-wire benchmark (717 Million) once binding wire, fastener stock and mesh wire are added. The two broader steel figures are context, not comparables. Our analysis suggests the true wire-only base sits near 1.7–1.9 Billion, and the 6.7% CAGR is credible given construction pipelines, though it embeds an energy-sector acceleration that may prove optimistic if oil-linked capex softens.
Segmentation runs along two primary axes — material and application — with process type (hot-rolled, cold-drawn, galvanized, pre-stressed) cutting across both as a specification overlay rather than a standalone parent.
| Parent segment | Children | 2024 signal |
|---|---|---|
| By Material | Carbon steel, Stainless steel, Alloy steel | Carbon 65.7% share; alloy fastest-growing |
| By Application | Construction, Automotive, Agriculture, Energy, Industrial/Machinery | Construction leads; energy ~9.6% CAGR |
| By Process Type | Hot-rolled, Cold-drawn, Galvanized, Pre-stressed | Galvanized gaining on corrosion demand |
| By End-Use Channel | OEM direct, Distributor/stockist, Project contractor | Project channel dominant in GCC |
The material split is the defining commercial fact: two-thirds of volume is commodity carbon wire, which is price-competitive and import-exposed. The value pool, however, is migrating toward alloy and coated grades where differentiation and pricing power are materially stronger.
Saudi Arabia leads the regional steel wire market with approximately 30% of 2024 revenue, underpinned by Vision 2030 construction, industrial diversification and energy infrastructure. Turkey is the production heavyweight and re-export hub, while the UAE anchors import and distribution flows.
The geography is unusual: consumption leadership and production leadership sit in different countries. Turkey produces roughly 61% of regional stranded wire output yet consumes far less than it makes, creating structural export dependency. Our analysis suggests this split is a strategic vulnerability — Turkish exporters face EU and Gulf trade-defence scrutiny, and any tariff shift would redirect volumes into GCC markets, pressuring local mill pricing.
Growth is driven by three reinforcing forces — state-led construction, energy diversification and industrial localization — offset by raw-material volatility, import competition and regulatory friction. The net balance favors expansion, but margin risk is asymmetric.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Vision 2030 & smart-city capex | Driver | Strong | Megaprojects consume reinforcement, binding and mesh wire |
| Energy grid & renewables build-out | Driver | Strong | Cabling, fencing, drilling support; fastest application CAGR |
| Industrial localization (Saudi, UAE, Qatar) | Driver | Moderate | Domestic fabrication raises wire consumption |
| Corrosion-resistant grade adoption | Driver | Moderate | Harsh climate favors galvanized/stainless premium |
| Steel price volatility | Restraint | Strong | Compresses producer margins, delays project awards |
| Import competition (China, India, Turkey) | Restraint | Strong | Undercuts local mills; oversupply pressure |
| Energy cost & grid constraints | Restraint | Moderate | Raises conversion costs in non-GCC markets |
The critical second-order effect: localization policy and import competition are colliding. As GCC mills add capacity, import share must fall — but only if local product quality and lead times match. Buyers should expect tariff escalation and local-content rules to become the decisive procurement variable by 2027.
No single vendor dominates regionally; the field splits into integrated regional mills, global wire specialists and Turkish export-oriented producers. Differentiation rests on grade capability, certification and project logistics rather than scale alone.
| Company | Type | Regional positioning | Moat |
|---|---|---|---|
| SABIC | Integrated regional | Saudi anchor | Feedstock integration, local-content access |
| DANA STEEL | Regional specialist | UAE distribution | Stockist reach, specification breadth |
| Bekaert | Global specialist | Premium wire | Advanced coating and alloy technology |
| ArcelorMittal | Global integrated | Project supply | Scale, global certification |
| JFE Steel | Global specialist | High-grade wire | Metallurgical R&D depth |
| thyssenkrupp | Global integrated | Industrial wire | Engineering and quality systems |
| Turkish producers | Export-oriented | Volume supply | Cost position, EU adjacency |
Global specialists hold the high-margin alloy and coated segments; regional mills own commodity carbon volume through local-content preference. Our analysis suggests the mid-tier is the contested zone — buyers increasingly expect galvanized and pre-stressed capability at commodity-adjacent pricing, squeezing undifferentiated stockists.
Selection criteria are shifting from price-per-tonne to total lifecycle cost. In coastal and high-humidity environments, galvanized or stainless grades reduce replacement frequency enough to offset a 15–25% premium — a calculation buyers should model explicitly rather than default to carbon.
Procurement risk concentrates in supply continuity and specification conformity. Import dependence for specialized grades means lead-time volatility, and buyers should qualify at least two sources per critical grade. Certification to international standards (ISO wire tolerances, ASTM tensile grades) is the practical compliance gate for project work.
Switching costs are moderate for commodity carbon wire but high for pre-qualified structural and energy applications where re-certification takes months. Buyers entering multi-year project frameworks should lock grade specifications early. Regulatory compliance — local-content rules, tariffs and standards adoption — varies materially by country and is the most under-modeled cost in regional procurement.
The balance of evidence favors a structurally growing but margin-compressing market. Volume growth of roughly 6.7% annually is credible on construction and energy pipelines, yet commodity carbon wire — two-thirds of the market — is where import competition is fiercest. Vendors anchored purely in commodity grades will grow revenue but lose profitability.
The strongest counter-argument: energy-sector acceleration at 9.6% CAGR may be overstated, since it depends on capex that is oil-linked and politically cyclical. If hydrocarbon revenues soften, project awards slip and the headline CAGR decelerates toward the 4–5% range implied by broader steel benchmarks.
Actionable strategy:
What would change this conclusion: sustained tariff protection for GCC mills combined with accelerated grid and renewables awards would push growth and margins above our base case. Conversely, a sharp oil-price correction would validate the bear case. Closing that uncertainty requires granular project-level forecasting beyond this overview.
| Region | Market Share (%) |
|---|---|
| Saudi Arabia | 0.3% |
| Turkey | 0.22% |
| UAE | 0.14% |
| Iran | 0.09% |
| Oman | 0.06% |
| Qatar | 0.05% |
| Kuwait | 0.04% |
| Iraq | 0.04% |
| Israel | 0.03% |
| Rest of Middle East | 0.03% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.7% from 2020-2034 |
| Segmentation |
|
The market was estimated at 1,760.6 Million in 2024 and is projected to reach 3,112.8 Million by 2033, expanding at a 6.7% CAGR over the 2025–2033 forecast period.
Saudi Arabia leads with roughly 30% of 2024 revenue, driven by Vision 2030 construction and industrial projects. Turkey is the largest producer and exporter, while the UAE is the leading importer.
Energy is forecast to grow fastest at around 9.6% CAGR, driven by grid modernization, pipeline construction and renewable energy infrastructure requiring cabling and fencing wire.
Carbon steel holds about 65.7% of revenue due to its strength, durability and cost efficiency in construction reinforcement and binding. Alloy steel is the fastest-growing material segment.
Steel price volatility, import competition from China, India and Turkey, energy cost constraints and regulatory complexity across countries all limit margin expansion and investment certainty.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split. Structured depth interviews were conducted across the value chain with raw material and wire-rod suppliers, specialized wire drawers and coaters, contract fabricators, and regional distributors and stockists. Decision-makers interviewed include VP-level Sourcing leads, Heads of Metallurgical R&D, Technical Directors and Commercial Operations Leads, with quotas balanced across GCC, Turkish and Iranian respondents to reflect divergent trade regimes.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| Technical & Metallurgical Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Wire Rod & Raw Material Suppliers | 30% |
| Specialized Wire Producers & Coaters | 35% |
| Contract Fabricators | 15% |
| Distributors & Stockists | 20% |
Secondary validation draws on UN Comtrade and WTO trade statistics, national customs databases, corporate annual filings and investor presentations, patent databases, and recognized technical standards bodies including ISO and ASTM. Public infrastructure-spending disclosures from GCC development programs were cross-referenced against import volumes to test demand consistency.
Top-down macroeconomic and industry-segment allocation was run simultaneously with bottom-up modeling of manufacturer capacity, product pricing and end-use consumption. Divergences between the two approaches were reconciled at the country and material-segment level before consolidation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow & consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & filings | High |