 Polyethylene Terephthalate Pet Compounding Market
 2026
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 214

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Polyethylene Terephthalate Pet Compounding Market
Khageshwar Rongkali
Senior Analyst

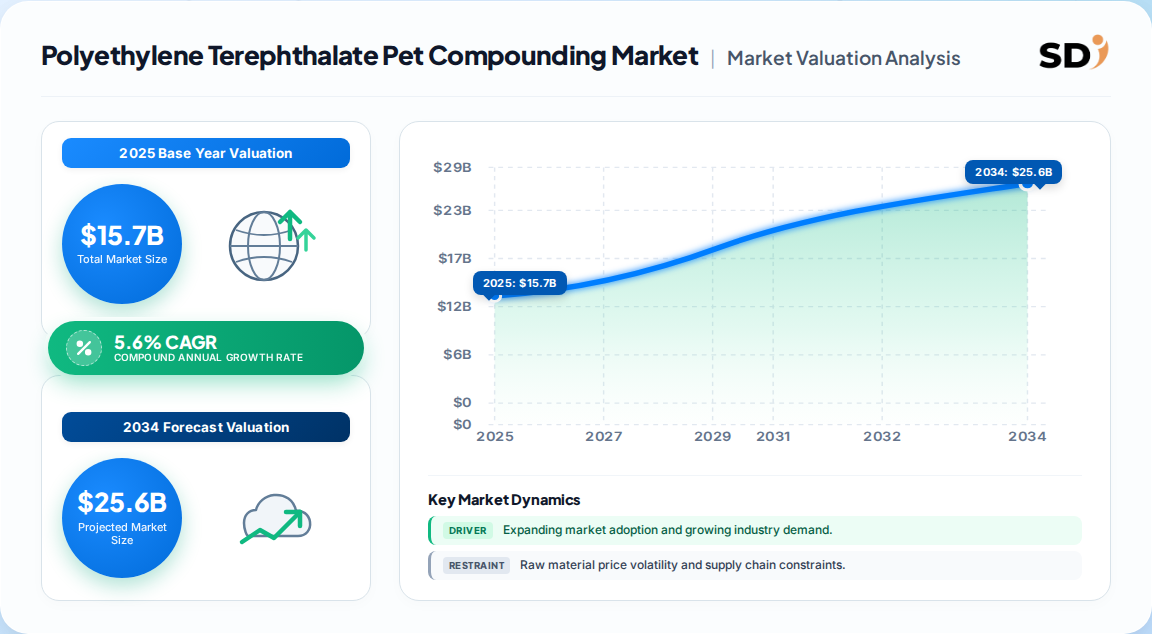
| Year | Market Size |
|---|---|
| 2025 | 15.70 B |
| 2026 | 16.60 B |
| 2027 | 17.50 B |
| 2028 | 18.50 B |
| 2029 | 19.50 B |
| 2030 | 20.60 B |
| 2031 | 21.80 B |

The Polyethylene Terephthalate PET compounding market covers the industrial blending of PET resin with additives, modifiers, fillers, and reinforcements to deliver tailored mechanical, thermal, barrier, and electrical properties. Compounded grades serve packaging, electronics, automotive, construction, and industrial machinery, using virgin or recycled PET feedstock.
This report covers compounded PET formulations — including glass-filled, flame-retardant, impact-modified, and recycled-content grades — across packaging, electrical and electronics, industrial machinery, automotive, construction, and material handling applications. It sizes global revenue and forecasts through 2033 by application and region.
This analysis does not cover upstream commodity PET resin polymerization, textile-grade polyester fiber, or bottle-to-bottle mechanical recycling economics as standalone markets. Those are treated only as input-cost and feedstock context.
The market is approximately 15.7 Billion in 2025, with a 5.6% CAGR to 2033 according to the most widely cited estimate. Competing estimates differ modestly on base year and horizon, reflecting scope differences in recycled content and application coverage.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 15.7 Billion to 24.3 Billion | 2025 | 2033 | 5.6% | Compounded PET grades, all applications, global | One published estimate (Grand View style) |
| 15.56 Billion to 25.83 Billion | 2025 | 2035 | 5.20% | Compounded PET, broader 10-year horizon | A competing analysis |
| ~4% CAGR, 2025-2030 | 2025 | 2030 | 4.0% | Compounded PET, end-user segmentation | A third published estimate |
| 42.9 Billion to 70.4 Billion (upstream PET resin) | 2025 | 2035 | 5.1% | Base PET resin, not compounded | Separate upstream benchmark |
The 5.6% CAGR and 24.3 Billion 2033 figure is the most defensible for compounded PET: it sits between the conservative 4% view (which may under-weight recycled-content premiumization) and the longer 2035 horizon. Our analysis suggests the 4% estimate likely reflects a narrower, pre-recycled-mandate demand base.
Segmentation runs primarily by application, with packaging dominant and electrical and electronics the fastest-rising secondary segment. Material grade and feedstock origin (virgin versus recycled) cut across every application.
| Parent segment | Children |
|---|---|
| Application | Packaging, Electrical & Electronics, Industrial Machinery, Automotive, Construction, Material Handling, Others |
| Grade type | Glass-filled, Flame-retardant, Impact-modified, Barrier, Conductive |
| Feedstock | Virgin PET, Recycled PET (rPET) |
Asia Pacific leads the global PET compounding market with a 44% revenue share in 2025 and the highest forecast CAGR, driven by packaging demand in China and India. North America and Europe follow as mature, regulation-sensitive markets.
| Region | Market Share (%) |
|---|---|
| North America | 0.23% |
| Europe | 0.22% |
| Asia-Pacific | 0.44% |
| South America | 0.06% |
| Middle East & Africa | 0.05% |
| Region | 2025 Share |
|---|---|
| Asia-Pacific | 44% |
| North America | 23% |
| Europe | 22% |
| South America | 6% |
| Middle East & Africa | 5% |
Growth is driven by packaging conversion from glass to PET, lightweighting in automotive, and recycled-content mandates, while overcapacity and trade defense measures restrain pricing and cross-border flows.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Packaging substitution from glass | Driver | High | Lightweight, unbreakable, resealable bottles and jars |
| Recycled-content mandates (EU 30% by 2030) | Driver | High | Pulls demand for rPET compounding and certified grades |
| E&E miniaturization and insulation needs | Driver | Medium | Higher-spec flame-retardant and dimensional-stable compounds |
| Global PET overcapacity | Restraint | High | Import pressure compresses compounder margins |
| EU safeguard investigation (Nov 2026) | Restraint | High | Trade uncertainty raises landed-cost volatility |
| Feedstock (PTA, MEG) price swings | Restraint | Medium | Erodes compounder margin stability |
Our analysis suggests the balance favors volume growth over price growth: demand drivers are structural, but overcapacity and trade measures cap realizations. Compounders with recycled certification and regional production footprints will out-earn commodity peers.
BASF, DuPont, SABIC, RTP Company, and Vikas Ecotech lead a consolidated PET compounding market, with differentiation built on formulation IP, application engineering, and recycling credentials.
| Company | Notable strength | Strategic posture |
|---|---|---|
| BASF SE | Broad additive and formulation portfolio | Global, application-led |
| DuPont | High-performance engineering compounds | Premium E&E and automotive |
| SABIC | Integrated petrochemical feedstock | Scale and cost leadership |
| RTP Company | Custom thermoplastic compounding | Specialty and small-batch agility |
| Vikas Ecotech | Regional compounding and additives | Emerging-market cost position |
Competitive moats rest on qualification cycles (especially food-contact and E&E), formulation libraries, and recycled-content traceability. Our analysis suggests recycling certification will become the single strongest differentiator by 2030.
Buyers should prioritize food-contact compliance, recycled-content traceability, and supply security over unit price alone. Qualification cycles are long and switching costs are high, so dual-sourcing and regional inventory buffers are prudent.
Procurement risk centers on feedstock volatility (PTA, MEG) and trade-defense measures. The EU safeguard investigation into PET resin chemicals, layered on existing anti-dumping duties on China and anti-subsidy duties on India, implies landed-cost volatility through 2027. Buyers with EU exposure should contract regional supply and stress-test import-dependent flows.
Operators should verify compounder certifications (food-contact, UL flame ratings) and rPET chain-of-custody. Switching compounders mid-qualification is costly, so selecting partners with multi-region capacity and recycling infrastructure reduces long-term risk.
The balance of evidence favors a volume-led, regionally fragmented expansion: packaging anchors demand, Asia Pacific anchors supply growth, and recycled-content regulation anchors pricing power. The strongest counter-argument is that overcapacity could compress margins faster than premiumization lifts them, particularly in commodity glass-filled grades. We judge premiumization will win, but only for certified compounders.
Actionable strategy for investors and operators:
Evidence that would change this conclusion: a formal EU safeguard imposing provisional duties above 10%, or a sustained PTA/MEG price spike above 2022 levels, would shift the recommendation toward defensive, short-cycle contracting.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.6% from 2020-2034 |
| Segmentation |
|
The global PET compounding market was valued at approximately 15.7 Billion in 2025 and is projected to reach 24.3 Billion by 2033, growing at a 5.6% CAGR from 2026 to 2033.
Asia Pacific leads with roughly 44% revenue share in 2025 and is also the fastest-growing region, driven by packaging demand in China and India.
Packaging dominates at about 54% of 2025 revenue, driven by food and beverage containers, bottled water, and the material's lightweight, unbreakable properties.
BASF SE, DuPont, SABIC, RTP Company, and Vikas Ecotech are among the leading players in a consolidated competitive landscape.
Growth is driven by packaging substitution from glass, lightweighting in automotive, electronics demand, and recycled-content mandates such as the EU's 30% rPET target by 2030.
Global PET overcapacity, import pressure, and trade-defense measures such as the EU safeguard investigation into PET resin chemicals are the primary restraints.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with raw material and feedstock suppliers, specialized PET compounders, contract formulators and blenders, and global distributors. Decision-maker designations interviewed include VP-level Sourcing leads, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, ensuring both demand-side and supply-side validation.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement Leads | 35% |
| R&D and Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Regulatory & Quality Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Feedstock Suppliers | 40% |
| Specialized PET Compounders | 35% |
| Contract Formulators & Blenders | 15% |
| Global Distributors | 10% |
We cross-reference official multilateral trade and standards databases including UN Comtrade, WTO trade statistics, US ITC, and Eurostat, alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations. This anchors our estimates in verifiable public benchmarks rather than single-publisher figures.
Our sizing applies simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption modeling) triangulation. Divergences between the two approaches are reconciled through primary interview validation and historical CAGR regression.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |