 Polymer Nanocomposite Market
 Outlook 2025
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 184

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Polymer Nanocomposite Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2024 | 12.60 B |
| 2025 | 14.60 B |
| 2026 | 16.90 B |
| 2027 | 19.60 B |
| 2028 | 22.70 B |
| 2029 | 26.30 B |
| 2030 | 30.50 B |

The polymer nanocomposite market comprises engineered materials in which nanoscale fillers — nanoclay, carbon nanotubes, graphene, nanofibers or metal oxides, with at least one dimension between 1 and 50 nm — are dispersed in a thermoplastic, thermoset or bio-based polymer matrix to deliver step-change gains in strength, thermal stability and barrier performance.
This analysis covers nanofiller-reinforced polymer systems across packaging, automotive, aerospace and defense, electronics and semiconductors, coatings, energy, and sports and healthcare applications, spanning all major regions. It assesses fillers, polymer matrices, end-use demand, pricing mechanics and vendor positioning.
This analysis does not cover conventional filled polymers above the nanoscale, neat engineering resins, carbon-fiber composite structures without a nanofiller phase, or metal-matrix and ceramic-matrix nanocomposites.
The market is genuinely large but inconsistently measured: 2024 base-year estimates cluster tightly near 12.6–12.7 Billion, yet 2034–2035 horizon values diverge by more than USD 30 billion — a definitional problem, not a demand problem.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 12.67 Billion → 89.91 Billion | 2024 | 2035 | 19.5% | Broad: all fillers, all applications, all regions | One published estimate |
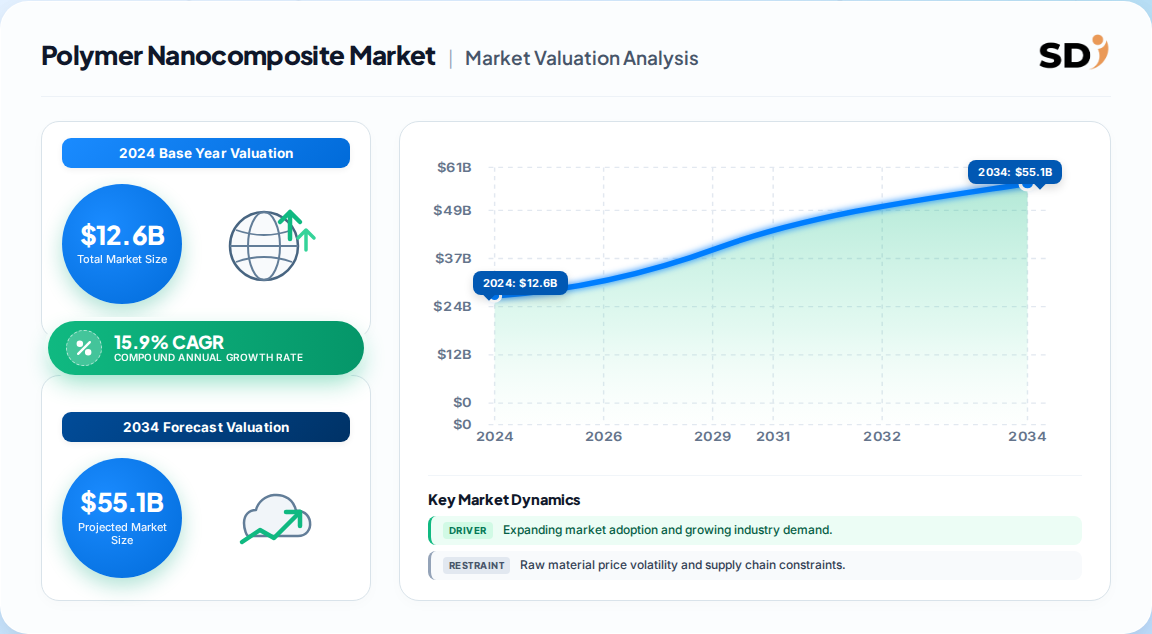
| 12.6 Billion → 56.4 Billion | 2024 | 2034 | 15.9% | Filler-led segmentation, polyamide and nanoclay weighted | A competing analysis |
| 15.3 Billion → 31.6 Billion | 2026 | 2031 | 15.62% | Narrower five-year window, filler and matrix split | A competing analysis |
| 8.87 Billion → 29.43 Billion | 2021 | 2028 | 18.46% | Historical baseline, pre-2024 pricing | A competing analysis |
Our analysis suggests the 15.9% trajectory is the most defensible planning anchor. The 19.5% case requires graphene and CNT costs to fall faster than current capacity build-out implies, and it compounds a decade of double-digit growth onto a base that has historically grown in the mid-teens. Note also that the 2026 figure of 15.3 Billion sits above the 2024 base of 12.6 Billion — consistent with roughly 10% realized growth in 2025 — implying the low-teens CAGR band, not high-teens, is where near-term volume actually lands.
Segmentation is best read along three axes — filler chemistry, polymer matrix and end-use industry — because filler choice drives cost, barrier performance and regulatory exposure simultaneously.
| Parent segment | Children | Largest / fastest |
|---|---|---|
| By Filler Type | Carbon nanotubes, Nanoclay, Graphene, Metal oxide, Nanofiber, Others (nanodiamond, expanded graphite) | Nanoclay largest (37.7%); graphene fastest (18.7%) |
| By Polymer Matrix | Thermoplastics (polyamide, polyethylene, polypropylene), Thermosets (epoxy), Bio-based polymers | Thermoplastics 53.7% share; thermosets fastest (17.6%) |
| By Application | Packaging, Automotive and aerospace, Electronics and semiconductor, Coatings, Energy, Others (sports, healthcare) | Automotive and aerospace 30.4% share and 17.2% CAGR |
Polyamide alone accounted for roughly 4.9 Billion in 2024, reflecting its dominance in under-the-hood and structural automotive parts. Nanoclay's lead is a cost story: low filler price plus mature film-extrusion know-how enables 5–7 µm downgauging in snack packaging without shelf-life loss. Graphene's upside is a performance story — thermal conductivity above 10 W/mK while remaining electrically insulating — which is why it commands premium pricing but limited current volume.
Asia-Pacific leads, accounting for roughly 40% of 2025 revenue and growing at about 18.1% CAGR — faster than any other region — driven by concentrated automotive and electronics manufacturing, shortening regional supply chains and rapid 5G infrastructure build-out.
| Region | Market Share (%) |
|---|---|
| North America | 0.27% |
| Europe | 0.22% |
| Asia-Pacific | 0.41% |
| South America | 0.05% |
| Middle East & Africa | 0.05% |
North America — ~27% share; anchored by R&D intensity, aerospace and defense programs, and strict carbon-footprint regulation. The U.S. alone was valued near 4.2 Billion in 2024.
Europe — ~22% share; the regulatory engine room, where REACH restrictions on brominated flame retardants and OEM 2030 weight-reduction targets (20–25%) drive halogen-free nanocomposite adoption.
Asia-Pacific — ~41% share; largest and fastest; China, Japan, India and South Korea supply both demand and nanofiller capacity.
South America — ~5% share; packaging-led, price-sensitive, slower conversion to functionalized fillers.
Middle East & Africa — ~5% share; construction and coatings demand, dependent on imported masterbatch.
Global
North America (USA, Canada, Mexico)
Europe (Germany, UK, France, Italy)
Asia-Pacific (China, Japan, India, South Korea)
South America (Brazil, Argentina)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
Two sources disagree on regional leadership: one names North America as the largest market, another places Asia-Pacific first at ~40%. Our analysis favors Asia-Pacific on volume and value, because production of the downstream applications — vehicles, electronics, packaging film — has already migrated there. North America's apparent lead likely reflects higher per-unit pricing and R&D spend rather than tonnage, a distinction that materially changes where a supplier should place capacity.
Demand growth is structural and regulatory, while restraint is almost entirely a cost-of-processing problem — dispersion economics, not material science, decide who wins.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| High-barrier food and pharma packaging | Driver | High (~3.2% CAGR impact) | Oxygen transmission below 0.1 cc/m²/day; up to 40% thinner film |
| Automotive lightweighting and EV battery housings | Driver | High (~2.8–4.0% combined) | 40% mass saving vs. steel; crash energy absorption |
| 5G and power-electronics thermal management | Driver | Medium (~1.9%) | >10 W/mK conductive, electrically insulating grades |
| Halogen-free flame-retardant regulation | Driver | Medium (~1.6%) | REACH restrictions; 40–60% lower additive loading, UL-94 V-0 |
| Compounding and dispersion cost | Restraint | High (~2.1%) | Twin-screw shear intensity adds 200–400% to processing cost |
| Nanotoxicity / EHS compliance uncertainty | Restraint | Medium (~1.4%) | Divergent protocols; REACH dossiers exceeding USD 1 million |
| Graphene and CNT scale-up limits | Restraint | Medium (~1.8%) | Supply inconsistency widens quality variance |
The balance favors expansion, but the margin structure is fragile. Because functionalization to prevent nanotube agglomeration introduces extra processing steps and licensing fees, cost pressure keeps nanocomposites out of price-sensitive packaging and consumer goods until scale economies arrive. In parallel, regulatory support is a genuine tailwind: governments favoring advanced materials that satisfy safety and environmental standards give compliant suppliers a tender-level advantage in automotive and construction.
The competitive field splits into diversified chemical majors with distribution reach and specialist nanomaterial producers with dispersion expertise — few players hold both.
| Company | Base | Positioning | Strategic strength |
|---|---|---|---|
| BASF SE | Germany | Diversified chemicals and engineering plastics | Formulation breadth, global channel |
| Evonik Industries AG | Germany | Specialty additives and polyamides | Fiber-reinforced SLS and PA613 grades |
| Arkema SA | France | Specialty materials, CNT and bio-based polyamides | Nanotube capacity plus matrix integration |
| DuPont de Nemours | USA | High-performance polymers | Aerospace and electronics qualification |
| SABIC | Saudi Arabia | Commodity-to-engineering resin scale | Cost position and volume reach |
| Nanocor Inc | USA | Nanoclay specialty | Filler purity and dispersion know-how |
| Nanoshel LLC | USA | Nanomaterial portfolio | Multi-filler flexibility |
| 3M / RTP Company | USA | Compounding and functional additives | Masterbatch economics |
| Mitsubishi Chemical / Tosoh | Japan | Precision materials | APAC supply proximity |
Competitive moats sit in dispersion know-how and qualification cycles, not in raw filler supply. Automotive and aerospace buyers require multi-year validation, so incumbency is sticky and switching costs are high. Our analysis suggests the medium-concentration structure will consolidate around players who can offer masterbatch-ready formulations, because that is precisely where downstream processors lack in-house capability and where margins are most defensible.
Selection should be driven by four factors, in order: dispersion consistency, total landed cost, regulatory dossier completeness, and matrix compatibility. Uniform distribution of high-aspect-ratio fillers is the single largest quality risk — poorly dispersed graphene behaves like a defect, not a reinforcement, and failures surface only after qualification.
Procurement risk concentrates in supply reliability rather than price. Graphene and CNT supply scale-up remains inconsistent, so dual-sourcing or masterbatch inventory buffering is prudent. Expect switching costs of two to four quarters for automotive and aerospace grades due to re-validation; packaging grades switch far faster and should be treated as the volume beachhead.
Regulatory compliance is a genuine gate. Divergent global test protocols mean identical materials require separate dossiers, and REACH data packages for carbon nanotubes can exceed USD 1 million — a cost that flows into supplier pricing and favors large, compliant vendors. Buyers should require documentation on nanomaterial handling and food-contact clearance before sampling, not after.
Finally, model total cost, not resin price. Because compounding adds 200–400% to processing versus standard polymers, a cheaper filler with poor dispersibility can destroy the business case. Request dispersion-validated masterbatch, not dry powder, where in-house extrusion capability is limited.
The balance of evidence favors a mid-teens growth market, not a high-teens one. Base-year values converge tightly near 12.6 Billion, but the 2035 horizon of 89.9 Billion assumes graphene and CNT economics improve faster than current capacity investment suggests. The 15.9% path is more consistent with the observed 2024-to-2026 trajectory and with established dispersion-cost constraints. Plan on 15–16.5%, and treat anything above 17% as upside to be earned, not budgeted.
The strongest counter-argument is that regulatory compulsion could break the cost ceiling. Halogen-free flame-retardant mandates and EV lightweighting targets are not price-elastic — they force substitution regardless of premium — and if early-stage graphene capacity comes online as projected, deflation could unlock packaging volumes that transform the demand curve. That is a real possibility, but it is a 2028+ story, not a 2025 planning assumption.
Actionable strategy:
What would change our conclusion: sustained graphene pricing below the USD threshold that closes the packaging economics gap, or a single major OEM specifying nanocomposite structural parts at platform scale. Either would justify the higher trajectory; until then, the conservative band governs.
While this overview establishes the planning band, precise sub-segment forecasting — filler-by-application revenue, regional pricing differentials and vendor share at grade level — requires the full dataset.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 15.9% from 2020-2034 |
| Segmentation |
|
The market was valued at approximately 12.6 Billion in 2024 and an estimated 13.2–15.1 Billion in 2025, depending on scope. Base-year figures from competing analyses cluster tightly, making the 2024 valuation the most reliable anchor point.
Forecasts range from 15.6% to 19.5% CAGR. Our analysis favors a planning band of 15.5–16.5%, as the higher estimates depend on graphene cost deflation that has not yet materialized at industrial scale.
Asia-Pacific leads with roughly 40% of 2025 revenue and about 18% CAGR, ahead of North America (~27%) and Europe (~22%). Automotive and electronics manufacturing concentration drives the regional advantage.
Nanoclay holds the largest share at approximately 37.7%, driven by low cost and mature film-extrusion processing. Graphene and nanodiamond are the fastest-growing fillers at around 18.7% CAGR.
Key players include BASF, Evonik, Arkema, DuPont, SABIC, Nanocor, Nanoshel, 3M, RTP Company and Mitsubishi Chemical. Competitive advantage rests on dispersion know-how and long automotive qualification cycles rather than raw filler supply.
Compounding and dispersion costs add 200–400% to standard polymer processing, and nanotoxicity compliance dossiers can exceed USD 1 million. These cost barriers keep nanocomposites out of price-sensitive packaging until scale economies improve.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted with stakeholders across the value chain: specialty nanofiller and chemical producers, masterbatch formulators and compounders, contract processing houses, equipment suppliers, and global industrial distributors. Respondent designations were restricted to decision-makers with direct influence over specification and procurement, including VP-level Sourcing leads, Heads of R&D and materials science, Technical Directors responsible for dispersion and compounding, and Commercial Operations Leads covering packaging, automotive and electronics verticals. Interviews probed qualification cycles, dispersion tolerances, price sensitivity and regulatory dossier burden.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Materials Science Heads | 38% |
| Procurement & Sourcing Directors | 34% |
| Technical & Quality Operations Leads | 28% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical & Nanofiller Producers | 42% |
| Formulators & Masterbatch Compounders | 33% |
| Distributors & Industrial Traders | 25% |
Secondary validation draws on UN Comtrade and WTO trade flows for nanoscale fillers and masterbatch, US ITC and Eurostat import-export data, corporate annual filings and 10-K statements from listed chemical producers, patent filings in nanofiller dispersion and functionalization, and technical standards published by ISO and ASTM committees covering nanomaterial characterization and food-contact safety. Regulatory dossiers under EU REACH and FDA guidance on nanomaterial risk assessment were reviewed for compliance-cost benchmarking.
Market sizing runs top-down and bottom-up simultaneously. The top-down track allocates macroeconomic output across automotive, packaging, electronics and aerospace, then applies nanocomposite penetration coefficients. The bottom-up track models manufacturer capacity, realized selling prices by filler grade, and end-use consumption tonnage. Divergences between tracks are reconciled against trade flow data before a base year is fixed.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |