 Specialty Fertilizers Market
 2026: Size, CAGR & Outlook
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 212

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Specialty Fertilizers Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 23.50 B |
| 2026 | 25.40 B |
| 2027 | 27.30 B |
| 2028 | 29.50 B |
| 2029 | 31.80 B |
| 2030 | 34.20 B |
| 2031 | 36.90 B |

The specialty fertilizers market covers engineered nutrient products—water-soluble, controlled-release, slow-release, inhibitor-based, micronutrient, and liquid formulations—designed around nutrient availability, application precision, or loss control rather than bulk nutrient supply. Demand depends on crop value, irrigation infrastructure, advisory capability, and the local cost of conventional fertilizer.
This analysis covers the global specialty fertilizers market across product technology (water-soluble, controlled-release, slow-release, inhibitor-based, micronutrient, and liquid fertilizers), crop type, and application mode (fertigation, foliar, soil). It spans commercial, protected, and open-field agriculture. This analysis does not cover conventional commodity fertilizers (bulk urea, MOP, DAP), standalone bio-stimulants, soil conditioners, or agricultural machinery.
Published estimates diverge materially because of definitional boundaries—whether specialty products are counted at manufacturer gate value or retail, and whether liquid UAN and commodity-adjacent products are included. The table below reconciles the principal benchmarks.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 23.5 billion | 2025 | 2026–2035 | 7.8% | Engineered specialty products, manufacturer value | One published estimate |
| USD 40.0 billion | 2025 | 2026–2033 | 5.7% | Broader definition incl. UAN and liquid fertilizers | A competing analysis |
| USD 5.59 billion | 2025 | 2026–2031 | 4.07% | Europe only, specialty products | Regional trade analysis |
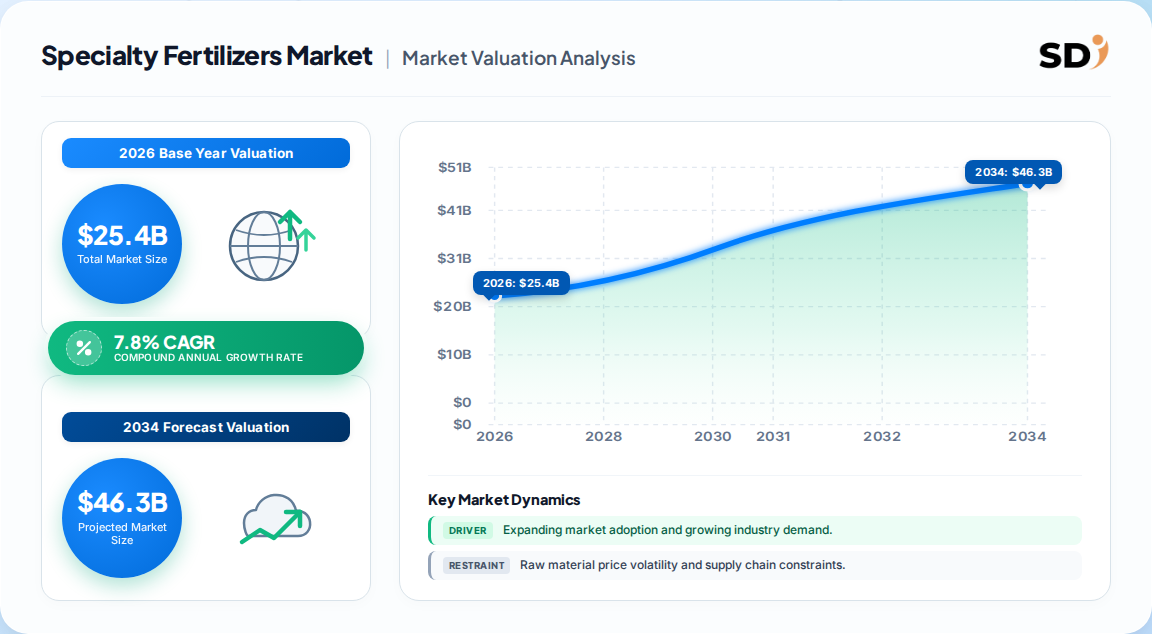
The USD 23.5 billion base is the most defensible for strategic planning. It excludes commodity-adjacent liquid nitrogen, isolating genuinely engineered formulations where pricing power and agronomic differentiation exist. Our analysis suggests the lower CAGR (7.8%) versus the broader definition's 5.7% is not contradictory—it reflects a narrower, higher-value base with faster growth in precision-driven segments. Buyers should anchor procurement and investment cases to the narrower definition to avoid overstating addressable specialty volumes.
Segmentation follows product technology, application mode, and crop type. The table below summarizes the principal non-geographic segments.
| Parent Segment | Children |
|---|---|
| By Technology | Water-soluble fertilizers, Controlled-release fertilizers, Slow-release fertilizers, Inhibitor-based fertilizers, Micronutrient fertilizers |
| By Application Mode | Fertigation, Foliar, Soil application |
| By Crop Type | Fruits & vegetables, Field crops, Horticultural crops, Turf & ornamentals |
| By Form | Liquid, Solid |
Water-soluble fertilizers held the largest technology share in 2025, while controlled-release fertilizers are projected to grow fastest at roughly 6.2% through 2031 in Europe. Fertigation dominates application, reflecting its compatibility with drip and pivot systems. Fruits and vegetables lead crop-type demand, particularly in export-oriented and protected cultivation.
Asia Pacific leads the global specialty fertilizers market with approximately 36% revenue share in 2025, driven by China's fertigation expansion, India's micro-irrigation programs, and intensive horticulture across Southeast Asia.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.36% |
| North America | 0.26% |
| Europe | 0.24% |
| South America | 0.08% |
| Middle East & Africa | 0.06% |
Regional leadership is not static. Europe's regulatory framework—Regulation (EU) 2019/1009 and Farm to Fork's 50% nutrient-loss reduction target by 2030—creates a compliance-driven upgrade cycle that could lift Europe's share in inhibitor-based and controlled-release products, even as Asia Pacific dominates volume. Our analysis suggests the Asia Pacific share will remain above 35% through 2030, but Europe's growth in value terms may outpace its volume growth.
Precision agriculture adoption, soil micronutrient deficiency, and environmental regulation are the principal growth drivers, while high cost versus conventional fertilizers and regulatory complexity constrain adoption in price-sensitive markets.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Precision agriculture adoption | Driver | High (USDA data, industry benchmarks) | Enables variable-rate and fertigation programs; contributes ~2.0% to CAGR |
| Soil nutrient deficiency & yield optimization | Driver | High (FAO documentation) | ~49% of global soils zinc-deficient; drives micronutrient and CRF demand |
| Environmental regulations (EU Farm to Fork) | Driver | High (EU policy) | Mandates 20% fertilizer reduction and 50% nutrient-loss cut by 2030 |
| High cost vs conventional fertilizers | Restraint | Medium | Limits smallholder adoption; ~-1.0% drag on CAGR |
| Regulatory complexity | Restraint | Medium | Delays product introduction and cross-border expansion; ~-0.5% drag |
The balance of evidence favors specialty fertilizers as a structural growth category, but the cost constraint is not trivial. In markets where commodity fertilizers are subsidized, specialty adoption depends on demonstrable return on investment and simplified formulations. The regulatory driver is strongest in Europe, where compliance deadlines create a visible economic value for loss-control products; in Asia Pacific, the driver is infrastructure—micro-irrigation and fertigation—which converts formulation consistency into repeatable root-zone delivery.
ICL Group leads the specialty fertilizers market with over 8.9% share in 2025, followed by Yara International, Nutrien, The Mosaic Company, and SQM; the top five collectively hold 32.9%. K+S has also demonstrated strong specialty fertilizer revenue growth, up 14% year-on-year in Q3 2026.
| Company | Estimated specialty position | Strategic differentiation |
|---|---|---|
| ICL Group | Market leader, >8.9% share | Broad water-soluble and CRF portfolio; strong fertigation agronomy |
| Yara International | Top-five | Global distribution; crop-nutrition advisory and digital tools |
| Nutrien Ltd. | Top-five | Scale in North America; retail and agronomy network |
| The Mosaic Company | Top-five | Potash-based specialty products; micronutrient blends |
| SQM | Top-five | Potassium-derived specialties; lithium-adjacent nutrient expertise |
| K+S | Strong specialty growth | Korn-Kali and specialty potash; 14% specialty revenue growth Q3 2026 |
Differentiation rests on formulation expertise, application-specific agronomy, and compliance capability—particularly in Europe, where Regulation (EU) 2019/1009 establishes product-function categories for inhibitors. Vendors that bundle digital advisory with specialty products create switching costs and recurring revenue. Our analysis suggests the top-five concentration (32.9%) leaves room for regional specialists to capture share in fertigation and micronutrient niches, but only where they can substantiate agronomic performance.
Buyers and operators must prioritize agronomic proof, application compatibility, and regulatory compliance when selecting specialty fertilizer suppliers. Mission-critical selection criteria include demonstrated nutrient-use efficiency, compatibility with existing fertigation or application equipment, and clear labeling under relevant regulatory frameworks.
Procurement risks center on supply reliability and price volatility. Natural-gas feedstock volatility affects nitrogen-based specialties, while potash supply concentration creates exposure for potassium-based products. Switching costs are moderate: growers can change formulations between seasons, but agronomic advisory relationships and equipment calibration create stickiness. Regulatory compliance is non-negotiable in Europe; CBAM and Farm to Fork requirements mean suppliers must provide verified emissions data and compliant product categories. Buyers should demand field-trial evidence and supplier transparency on carbon intensity, particularly for EU-bound procurement.
The balance of evidence favors a focused specialty strategy over broad premium positioning. The market is growing at 7.8% CAGR, but growth is concentrated in segments where application infrastructure already exists—fertigation in Asia Pacific, controlled-release in Europe, and micronutrient correction in high-value horticulture. Vendors pursuing uniform premium-product strategies will face cost resistance in smallholder markets; those aligning formulations with irrigation and advisory systems will capture repeatable demand.
The strongest counter-argument is that commodity fertilizer price normalization could erode the specialty premium and slow adoption. However, regulatory mandates and soil-degradation trends are structural, not cyclical; even if commodity prices fall, the agronomic case for micronutrient correction and nitrogen-loss control persists. Our analysis suggests the cost restraint (-1.0% CAGR drag) is partially offset by regulatory pull (+1.2%) and precision adoption (+2.0%), leaving net growth above 7%.
Actionable Strategy:
The evidence that would change this conclusion: a sustained collapse in commodity fertilizer prices without offsetting regulatory tightening, or a technology breakthrough that makes conventional fertilizers as efficient as specialty formulations at scale. Neither is visible in the current data horizon.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.8% from 2020-2034 |
| Segmentation |
|
The global specialty fertilizers market is estimated at USD 25.4 billion in 2026, projected to reach USD 49.9 billion by 2035 at a 7.8% CAGR, driven by precision agriculture and soil nutrient deficiency.
Asia Pacific leads with approximately 36% revenue share in 2025, driven by China's fertigation expansion and India's micro-irrigation programs. Europe follows with strong regulatory-driven demand for controlled-release products.
ICL Group leads with over 8.9% share in 2025. Yara International, Nutrien, The Mosaic Company, and SQM are also leading players; the top five collectively hold 32.9% of the market.
Precision agriculture adoption (contributing ~2.0% to CAGR), soil micronutrient deficiency (~49% of global soils are zinc-deficient), and EU environmental regulations mandating 20% fertilizer reduction by 2030 are the principal drivers.
High cost versus conventional fertilizers is the primary restraint, limiting adoption in smallholder markets across South and Southeast Asia. Regulatory complexity also delays product introductions and increases compliance overhead.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary split, prioritizing direct industry engagement. We conducted in-depth interviews with stakeholders across the specialty fertilizer value chain, including raw material suppliers (potash, phosphate, and nitrogen producers), specialized formulators, contract blenders, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews captured granular insights on formulation trends, adoption barriers, and pricing dynamics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Commercial Operations Leads | 20% |
| Regulatory Affairs Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Chemical Producers | 40% |
| Specialized Formulators & Blenders | 30% |
| Distributors & Retailers | 20% |
| Agronomy & Advisory Firms | 10% |
We triangulated primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards, including the International Organization for Standardization (ISO) and the International Fertilizer Association (IFA). Regulatory frameworks, particularly EU Regulation 2019/1009, were analyzed for compliance impacts.
Our sizing approach integrates top-down macroeconomic and industry segment allocation with bottom-up manufacturer capacity, product pricing, and end-use consumption modeling. This dual methodology reconciles definitional differences across published estimates and produces a defensible base-year valuation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2035 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |