Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Copper Alloys Connector Market: $5.5B by 2033, 7.5% CAGR
Copper Alloys Connector Market
Copper Alloys Connector Market: $5.5B by 2033, 7.5% CAGR
Copper Alloys Connector Market by Alloy Type (High-Conductivity Copper Alloys, Copper-Nickel-Silicon Alloys, Beryllium Copper Alloys, Phosphor Bronze Alloys, Others), by Connector Type (PCB Connectors, Circular & Rectangular Connectors, Board-to-Board, Wire-to-Board, High-Speed/Backplane Connectors), by Application (Telecommunications & Data Centers, Consumer Electronics, Automotive & Transportation, Industrial Automation, Medical Equipment, Renewable Energy), by Mounting Configuration (Board-to-Board, Wire-to-Board, Panel/Feed-Through), by Data-Rate Class (≤10 Gbps Standard, 10-25 Gbps, ≥25 Gbps Ultra-High-Speed), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea, Taiwan), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 260
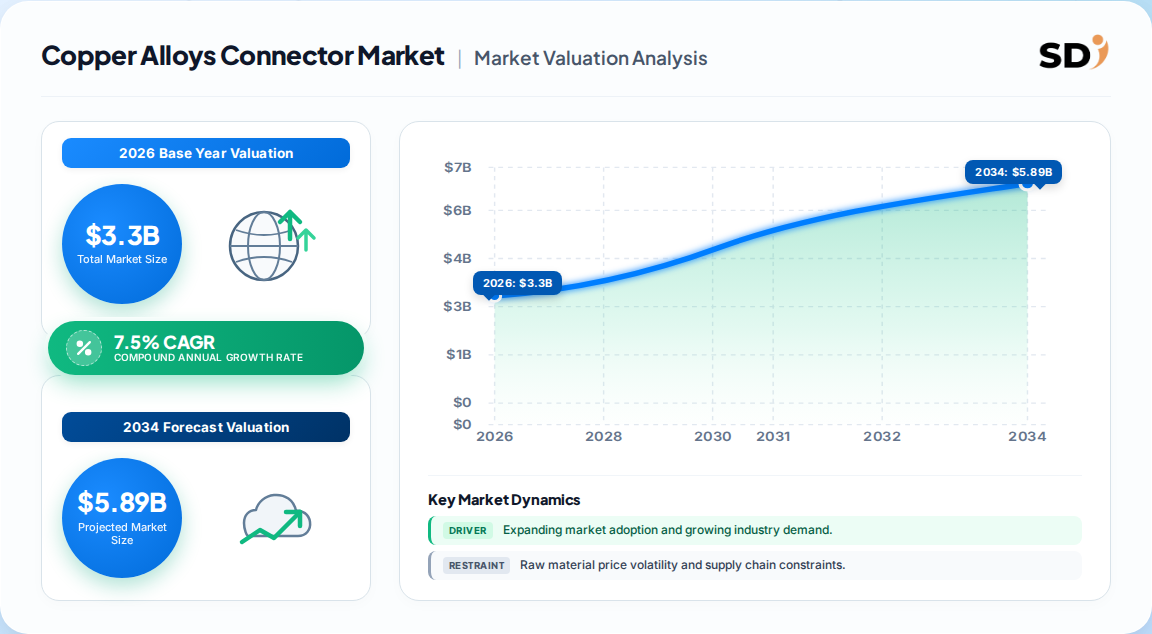
The global Copper Alloys Connector Market is valued at 3.3 Billion in 2026, projected to reach 5.5 Billion by 2033 at a 7.5% CAGR.
Asia Pacific dominates with ~65% revenue share, concentrated in China, Japan, and South Korea electronics and EV manufacturing clusters.
High-conductivity copper alloys lead alloy demand at ~38.5% share, driven by telecom/datacenter power and signal interconnects.
Telecommunications and data centers represent the single largest application at ~30-31% of revenue, with automotive EV connectors posting the fastest growth.
Leading vendors including Amphenol, TE Connectivity, Molex, and Yazaki compete on alloy qualification, design-in cycles, and supply resilience.
Why this matters for decision-makers: Buyers must lock multi-year alloy supply agreements now to hedge copper volatility; vendors must invest in lead-free CuNiSi capacity or risk ceding automotive and datacenter design wins to vertically integrated Asian competitors.
Copper Alloys Connector Market Size (In Billion)
5.0B
4.0B
3.0B
2.0B
1.0B
0
3.100 B
2025
3.300 B
2026
3.550 B
2027
3.810 B
2028
4.100 B
2029
4.410 B
2030
4.740 B
2031
Copper Alloys Connector Market Size (In Billion)
Year
Market Size
2025
3.100 B
2026
3.300 B
2027
3.550 B
2028
3.810 B
2029
4.100 B
2030
4.410 B
2031
4.740 B
What is the Copper Alloys Connector Market?
The Copper Alloys Connector Market encompasses the global supply of copper-based alloy materials—including high-conductivity copper, copper-nickel-silicon, beryllium copper, and phosphor bronze—specifically formulated and sold for the manufacture of electrical and electronic connectors. These alloys are selected for their conductivity, mechanical strength, corrosion resistance, and thermal stability across telecommunications, automotive, consumer electronics, and industrial applications.
Scope: what this report covers and excludes
This report covers copper alloy material demand for connector applications across alloy types (high-conductivity, CuNiSi, beryllium copper, phosphor bronze, and others), connector types, and end-use verticals spanning telecommunications/datacenters, consumer electronics, automotive, industrial automation, medical equipment, and renewable energy. Geographically it covers North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, with country-level detail for major markets. This analysis does not cover finished connector assemblies, cable harnesses, raw copper mining, or unrelated copper products such as plumbing and architectural copper.
How big is the market for Copper Alloys Connector Market?
The Copper Alloys Connector Market is most credibly sized at 3.3 Billion for 2026, with a forecast to 5.5 Billion by 2033 representing a 7.5% CAGR—a figure broadly corroborated by convergent independent estimates.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
3.3 Billion
2026
2033 (5.5 Bn)
7.5%
Copper alloys sold for connector applications, global
One published estimate
3.1 Billion
2025
2033 (5.5 Bn)
7.7%
Same scope, base-year shift
A competing analysis
3.3 Billion
2026
2033 (5.5 Bn)
7.7%
Same scope, differing CAGR rounding
A second competing analysis
2.8-2.5 Million
2025
2033
8.2%
Copper high-speed connector niche only
A niche-segment estimate
Our analysis favors the 3.3 Billion / 7.5% CAGR baseline for strategic planning. The small CAGR divergence (7.5% vs 7.7%) is rounding-driven and immaterial to a decade-long plan; the convergence on a 5.5 Billion 2033 endpoint across sources is a strong validation signal. We note that lower-tier estimates (sub-10 Million figures) reflect a narrow high-speed connector sub-niche and should not be extrapolated to the full alloy materials market.
How is the market segmented?
Segmentation is driven primarily by alloy metallurgy and end-use application, with each combination carrying distinct performance and qualification requirements.
The alloy segmentation is the most commercially consequential: high-conductivity alloys command ~38.5% of revenue, but CuNiSi is growing fastest due to stress-relaxation performance under automotive thermal cycling. Datacenter connectors increasingly demand ultra-high-speed capable alloys, creating a premium sub-market insulated from commodity price competition.
Which region leads in Copper Alloys Connector Market?
Asia Pacific leads the Copper Alloys Connector Market with approximately 65% of global revenue in 2026, anchored by China's dominance in electronics manufacturing, EV production, and telecom equipment, followed by Japan, South Korea, and Taiwan. North America is the fastest-growing region at ~6.8-7.0% CAGR.
Asia Pacific: China (largest), Japan, South Korea, India, Taiwan
North America: USA (approx. 140 Million base), Canada, Mexico
Europe: Germany, UK, France, Italy
Latin America: Brazil, Mexico, Argentina
Middle East & Africa: Saudi Arabia, UAE, South Africa
The ~65% Asia Pacific concentration is a double-edged sword: it delivers scale and cost advantages for global buyers, but exposes supply chains to geopolitical and tariff risk. Our analysis suggests the North America growth premium reflects deliberate nearshoring and CHIPS/Datacenter investment cycles rather than organic volume growth—implying regional demand will grow faster than global averages through 2030.
What is driving growth — and what is holding it back?
The single largest growth driver is datacenter and 5G infrastructure expansion, adding an estimated +1.8% to CAGR, while copper price volatility is the most material restraint at about -0.8% to CAGR.
Factor
Direction
Evidence Strength
Mechanism
5G roll-out & fiber densification
Driver (+1.8% CAGR)
High
3-4x more fiber runs per 5G site vs 4G; high-frequency connector demand
Rapid EV production ramp-up
Driver (+1.5% CAGR)
High
3-4x more connectors per BEV; 800V architectures demand high-performance alloys
Miniaturization of electronics
Driver (+1.2% CAGR)
High
Sub-1mm pitch connectors require CuNiSi and high-conductivity alloys
Co-packaged optics/PCIe Gen5-6
Driver (+0.9-0.7% CAGR)
Medium
Bespoke ultra-short copper interposers for AI/datacenter switching
Copper/precious-metal price volatility
Restraint (-0.8% CAGR)
High
Copper $8,000-11,000/ton; gold plating up 40% YoY compressing standard-connector margins
Sub-0.5mm pitch alignment tolerances
Restraint (-0.6% CAGR)
Medium
High scrap rates and rising R&D costs
Balance of evidence: Drivers materially outweigh restraints. The combined driver effect (~+5% incremental CAGR) versus restraint drag (~-1.4%) supports the 7.5-7.7% consensus range. The critical nuance: growth is skewed toward high-value segments (ultra-high-speed, high-voltage EV) while standard connectors face margin compression—a bifurcation strategically important for both buyers and investors.
Who are the leading vendors?
The competitive landscape is moderately concentrated, dominated by global connector OEMs who exert significant influence over alloy procurement, alongside specialized alloy producers.
Company
Primary Strength
Differentiation
Amphenol Corporation
Broad connector portfolio, datacenter/5G
Design-in lock-in with hyperscalers
TE Connectivity
Automotive and industrial connectors
Deep OEM qualification cycles, CuNiSi alloy expertise
Molex LLC
Micro connectors, datacenter
Miniaturization leadership
Yazaki Corporation
Automotive wire harness/connectors
EV architecture integration
Aptiv PLC
Automotive high-voltage connectors
800V platform expertise
Boway Alloy Material
Copper alloy materials supply
Cost-competitive Asian alloy producer
Differentiation rests on three moats: long qualification cycles (12-24 months) that lock in design wins; proprietary alloy formulations (CuNiSi, CuCrZr); and vertically integrated supply chains that buffer copper price volatility. Asian alloy material specialists like Boway and Chuangyitong compete primarily on cost and lead times, pressuring mid-tier Western suppliers' margins in standard segments.
What do buyers and operators need to know? (Decision Support)
Mission-critical selection criteria center on four variables: conductivity-to-strength ratio (determines connector power density), stress-relaxation resistance at operating temperatures (critical for EV and industrial), corrosion performance in harsh environments, and regulatory compliance (RoHS, REACH). Buyers should note that beryllium copper, while offering superior fatigue performance, faces increasing regulatory scrutiny and supply concentration risk—driving many OEMs toward CuNiSi and CuCrZr alternatives.
Procurement risk is dominated by raw-material volatility: copper traded between USD 8,000-11,000/ton during 2024-2025, and fixed-price long-term contracts can expose buyers to supplier distress if hedging is misaligned. Switching costs are high in qualified applications—replacing a specified alloy requires full re-qualification (electronics, automotive, medical), often 12-24 months. Operators should prioritize dual-source qualification for critical alloy grades and negotiate indexed pricing with copper pass-through clauses. Lead-free and PFAS-free formulations are emerging compliance requirements that could reset qualified material lists through 2028.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a bullish structural thesis on the high-value connector alloy tier, but with a clear warning on commoditized standard segments. The 5.5 Billion 2033 endpoint is defensible; the more actionable insight is that growth is not evenly distributed—ultra-high-speed datacenter connectors and high-voltage EV connectors will likely grow at 8-9% CAGR, while standard consumer-electronics connectors grow at 4-5%, compressing blended margins. The strongest counter-argument is that alternative materials (aluminum alloys, conductive polymers) and optical interconnect could erode copper's share faster than expected in specific low-power applications—but for high-reliability, high-temperature, high-current applications, copper alloys retain an irreplaceable performance envelope through the forecast horizon.
Actionable strategy:
Vendors: Secure CuNiSi and CuCrZr capacity and pursue lead-free alloy qualification now—automotive and datacenter design wins awarded in 2026-2027 will lock in material demand through 2033.
Buyers/OEMs: Dual-qualify critical alloy grades and negotiate copper-indexed pricing; the 12-24 month qualification cycle means supply disruptions cannot be solved reactively.
Investors: Focus on alloy producers with vertical integration and Asian cost positions; the regional concentration (~65% Asia Pacific) creates both a scale opportunity and a geopolitical hedging imperative.
What would change our conclusion: evidence that optical or aluminum interconnect displaces copper in >25 Gbps datacenter links faster than anticipated, or a sustained copper price above USD 12,000/ton that triggers accelerated substitution in cost-sensitive consumer segments.
Europe Copper Alloys Connector Market Revenue Billion Forecast, by Alloy Type 2020 & 2034
Frequently Asked Questions
1. How big is the Copper Alloys Connector Market?
The global Copper Alloys Connector Market is valued at approximately 3.3 Billion in 2026 and is projected to reach 5.5 Billion by 2033, growing at a 7.5% CAGR.
2. Which region dominates the Copper Alloys Connector Market?
Asia Pacific dominates with roughly 65% of global revenue, anchored by China's electronics, EV, and telecom manufacturing base, followed by Japan, South Korea, and Taiwan.
3. What is the fastest-growing application for copper alloys connectors?
Automotive and transportation connectors are growing fastest at around 8.3% CAGR, driven by EV electrification, 800V architectures, and ADAS electronics requiring more connectors per vehicle.
4. What are the main alloys used in connector applications?
High-conductivity copper alloys lead at about 38.5% share, followed by copper-nickel-silicon, beryllium copper, and phosphor bronze, each selected for specific conductivity, strength, and thermal performance requirements.
5. What is restraining the Copper Alloys Connector Market?
Copper and precious-metal price volatility—copper traded between USD 8,000 and 11,000 per ton recently—is the chief restraint, alongside sub-0.5mm alignment tolerances and regulatory compliance costs.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research employs a 70/30 primary-to-secondary methodology. In-depth interviews were conducted across the value chain: raw copper and alloying element suppliers, specialized alloy producers, connector manufacturers, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads across North America, Europe, and Asia Pacific.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP of Sourcing & Procurement Directors
30%
Heads of R&D & Technical Directors
35%
Commercial Operations Leads
20%
Regulatory Compliance Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Copper Producers
30%
Specialized Alloy Producers
35%
Connector Manufacturers
20%
Global Distributors & Traders
15%
Secondary Benchmarking & Public Trade Validation
We triangulate against official databases including UN Comtrade, WTO, US ITC, and Eurostat for cross-border copper alloy and connector trade flows. Corporate annual filings (10-K, SEC filings, investor presentations) validate capacity and revenue estimates. Patent databases and recognized industry standards bodies (ASTM, ISO, IEC) inform material qualification and compliance analysis.
Demand Modeling & Market Sizing Triangulation
Simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing, end-use consumption) modeling is applied. Consensus is reached where both approaches converge within a ±5% band.


 Copper Alloys Connector Market