 Activated Carbon Market
 Size, Share & Growth Forecast to 2031
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 191

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Activated Carbon Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2024 | 3.730 B |
| 2025 | 3.940 B |
| 2026 | 4.160 B |
| 2027 | 4.390 B |
| 2028 | 4.640 B |
| 2029 | 4.900 B |
| 2030 | 5.180 B |

The activated carbon market refers to the global industry involved in the production, distribution, and application of highly porous carbon materials used for adsorption and purification. These materials are essential in water treatment, air purification, food processing, pharmaceuticals, and industrial processes to remove contaminants from liquids and gases.
This report provides a comprehensive analysis of the global activated carbon market, covering raw materials (coal, coconut shell, wood), forms (powdered, granular, extruded), applications (water treatment, air purification, solvent recovery, etc.), and end-user industries. The study includes historical data for 2021–2025, base-year estimates for 2026, and forecasts through 2031. It analyzes market dynamics, competitive landscape, regulatory frameworks, and regional trends across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. This analysis does not cover adjacent markets such as activated carbon fibers (ACF) as a standalone segment, carbon molecular sieves, or biochar used for soil amendment, except where directly relevant as a substitute or feedstock.
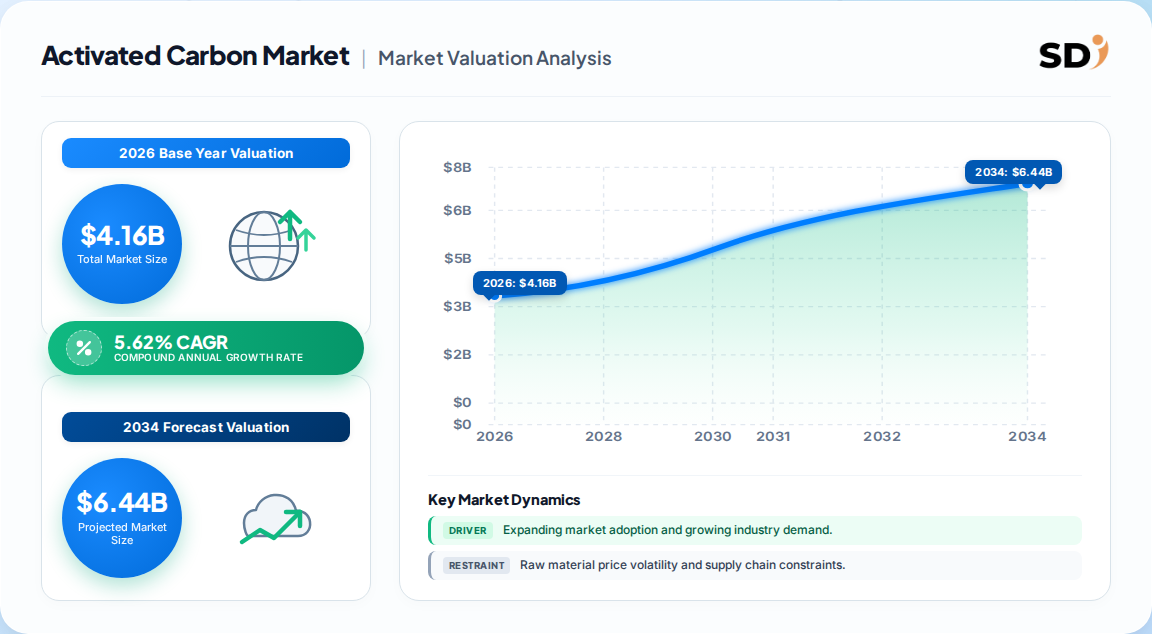
The global activated carbon market is estimated to be USD 4.16 billion in 2026, with forecasts projecting USD 5.47 billion by 2031, reflecting a 5.62% CAGR. However, other published estimates show notable divergence.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 4.16 Billion | 2026 | 2031 | 5.62% | Global market for all activated carbon types, value in USD | One published analysis |
| USD 4.2 Billion | 2026 | 2033 | 4.0% | Global market, product and end-use segmentation | A competing estimate |
| USD 5.43 Billion | 2026 | 2034 | 8.5% | Global market, broader definition including some industrial applications | Another published estimate |
The most defensible figure is the USD 4.16 billion estimate for 2026. Our analysis suggests that the higher 8.5% CAGR estimate likely includes a broader definition of activated carbon products and may incorporate adjacent markets such as carbon filters and canisters. The 4.0% CAGR appears conservative and may reflect a more mature market view. The mid-range 5.62% CAGR aligns with the regulatory drivers and capacity investments we observe, making USD 4.16 billion the most reliable baseline for strategic planning.
The activated carbon market is segmented by raw material, form, application, and end-user industry, with water treatment representing the largest application area.
| Parent Segment | Children |
|---|---|
| By Raw Material | Coal-Based, Coconut-Shell-Based, Wood-Based, Other |
| By Form | Powdered (PAC), Granular (GAC), Extruded / Pelletized |
| By Application | Water Treatment, Air Purification, Solvent Recovery, Decolorization, Sugar Production, Catalyst, Metal Extraction, Food & Beverage |
| By End-User Industry | Water Treatment, Industrial Processing, Pharmaceuticals, Automotive, Others |
Asia-Pacific is the largest and fastest-growing market for activated carbon, accounting for 37.72% of global revenue in 2025, driven by rapid industrialization and expanding water treatment infrastructure.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.41% |
| North America | 0.24% |
| Europe | 0.22% |
| South America | 0.06% |
| Middle East & Africa | 0.07% |
| Parent Region | Sub-Regions / Countries |
|---|---|
| Asia-Pacific | China, India, Japan, South Korea, Indonesia, Thailand, Australia |
| North America | United States, Canada, Mexico |
| Europe | Germany, United Kingdom, France, Italy, Spain, Netherlands |
| South America | Brazil, Argentina, Chile, Peru, Colombia |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Turkey |
Trade data from the World Bank (WITS) confirms that Asia-Pacific is a major import hub, with China and Korea among the top five global importers of activated carbon (HS 380210) in 2023. The United States, while a major producer, also imports significant volumes to meet domestic demand. This trade flow underscores the region's dominant role in both production and consumption. Our analysis indicates that local feedstock availability (coal and coconut shell) gives Asia-Pacific producers a structural cost advantage, but this is offset by weather-related supply risks and logistical bottlenecks.
Growth is primarily driven by stringent environmental regulations, particularly around water purification and air quality, while supply chain volatility and high capital costs act as restraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Growing demand for water purification | Driver | High | Tightening water-quality regulations and PFAS remediation programs force utilities to invest in high-capacity GAC filters and multi-year supply contracts. |
| Mercury-removal mandates for coal-fired plants | Driver | Medium | Revised Mercury and Air Toxics Standards (MATS) in the U.S., China, and India require powdered and impregnated carbons for flue-gas injection. |
| Surge in low-sulphur fuel regulations boosting solvent recovery | Driver | Medium | IMO 2020 sulphur cap and stricter emission ceilings drive demand for activated carbon in solvent recovery and VOC removal. |
| Supply-chain disruption for coconut-shell charcoal | Restraint | High | Weather-driven harvest shocks and logistical issues in Indonesia, Philippines, and Sri Lanka cause price volatility and supply interruptions. |
| Coal-price volatility squeezing margins | Restraint | High | Fluctuations in coal prices, particularly in China and India, increase production costs and create pricing uncertainty. |
The balance of evidence strongly favors the drivers, but the market faces near-term headwinds. Our analysis suggests that while regulatory tailwinds are durable and long-lasting, feedstock supply risks are acute in the short term. The shift toward GAC and reactivation services is expected to mitigate some of these risks by reducing reliance on virgin raw materials and improving supply chain resilience.
The global activated carbon market is moderately concentrated, with a mix of large multinationals and regional specialists competing on capacity, product purity, and service offerings.
| Company | Headquarters | Key Differentiators |
|---|---|---|
| Kuraray Co., Ltd. | Japan | Broad product portfolio, strong R&D, global distribution network, and expertise in high-performance grades. |
| Cabot Corporation | United States | Leading in specialty carbons, including high-purity grades for pharmaceuticals and medical applications. |
| Calgon Carbon Corporation | United States | Extensive line of GAC and reactivation services, long-term municipal contracts, and PFAS remediation expertise. |
| Jacobi Carbons | Sweden | Significant coconut-shell-based capacity, strong presence in Europe and Asia, and focus on sustainable sourcing. |
| Haycarb PLC | Sri Lanka | Vertically integrated coconut-shell supply, cost leadership, and extensive export network. |
Differentiation is increasingly based on the ability to offer reactivation services and guarantee supply of high-performance grades. Companies with vertically integrated raw material sources, such as Haycarb, enjoy cost advantages, while those with strong service networks, like Calgon Carbon, can capture higher margins in the municipal water sector.
Buyers of activated carbon must navigate a complex landscape of performance specifications, regulatory compliance, and supply chain risk. The most critical selection criteria are adsorption capacity, pore size distribution, and mechanical strength, which determine the product's efficiency and lifespan in a given application. For water utilities, compliance with PFAS removal standards is non-negotiable, requiring GAC with certified performance data. Procurement risks include feedstock price volatility, especially for coconut-shell-based grades, and logistical disruptions. Switching costs are moderate to high, as changing carbon type or supplier often requires re-validation of treatment processes and may necessitate equipment modifications. Long-term contracts with price adjustment clauses and guaranteed supply are recommended to mitigate risk. Operators should also consider total cost of ownership, factoring in reactivation services, which can reduce lifecycle costs by 20–30% compared to single-use PAC.
The balance of evidence favors a bullish outlook for the activated carbon market, underpinned by irreversible regulatory drivers and a structural shift toward higher-performance, service-integrated solutions. While feedstock volatility and capex requirements pose near-term challenges, the long-term trajectory is clear. The strongest counter-argument is that alternative technologies, such as advanced oxidation or membrane filtration, could reduce reliance on activated carbon in certain water treatment applications. However, we believe activated carbon will remain the dominant technology for PFAS removal and micropollutant control due to its proven efficacy, cost-effectiveness, and established infrastructure. Our analysis suggests that the market will increasingly reward vendors that can offer closed-loop systems—combining virgin carbon supply with reactivation services—and that buyers should prioritize suppliers with vertically integrated feedstock access or robust recovery networks. The evidence that would change our conclusion is a significant breakthrough in alternative adsorbents or a dramatic relaxation of environmental regulations, neither of which appears likely in the forecast period.
Actionable Strategy:
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.62% from 2020-2034 |
| Segmentation |
|
The global activated carbon market was valued at USD 4.16 billion in 2026 and is expected to reach USD 5.47 billion by 2031, growing at a 5.62% CAGR. This growth is driven by water purification and air quality regulations.
Asia-Pacific is the largest market, accounting for 37.72% of global revenue in 2025, and is also the fastest-growing region with a projected 6.44% CAGR through 2031. This is due to rapid industrialization and expanding water treatment infrastructure.
Key drivers include stringent water-quality regulations, PFAS remediation programs, mercury-removal mandates for coal-fired plants, and the shift toward low-sulphur fuels which boosts solvent recovery applications. These factors are creating sustained demand across water treatment and industrial sectors.
The market faces supply-chain disruptions for coconut-shell charcoal and volatility in coal prices, which squeeze margins. High capital costs for reactivation hubs also pose a barrier, but the shift toward GAC with reactivation services is helping to mitigate these risks.
Leading players include Kuraray Co., Cabot Corporation, Calgon Carbon Corporation, Jacobi Carbons, and Haycarb PLC. These companies compete on product purity, capacity, and the ability to offer reactivation services, with some enjoying vertical integration advantages.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology is anchored in a 70/30 primary-to-secondary research split, ensuring that insights are grounded in direct industry validation. We conducted in-depth interviews with key stakeholders across the activated carbon value chain, including raw material suppliers (coal and coconut shell), specialized producers, contract formulators, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews provided granular data on capacity, pricing, product specifications, and procurement strategies, and were instrumental in validating market sizing and segment shares.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory Affairs Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Chemical Producers | 45% |
| Specialized Formulators & Blenders | 35% |
| Industrial Distributors & Traders | 20% |
We rigorously triangulated primary insights with authoritative secondary sources. Trade data was sourced from UN Comtrade, the World Bank's WITS database, and national statistical agencies (e.g., US ITC, Eurostat) to validate cross-border flows and regional demand. Corporate filings, including 10-K and annual investor presentations, provided financial benchmarks and strategic initiatives for key market players. Patent databases and technical standards from associations such as the American Water Works Association (AWWA) and the International Activated Carbon Society were analyzed to assess innovation and regulatory trends.
Our market sizing employs a dual approach: Top-Down and Bottom-Up modeling. The Top-Down method allocates macroeconomic and industry segment data to derive total market value. The Bottom-Up method builds from manufacturer capacity, product pricing, and end-use consumption data. These models are then reconciled to produce a single, validated market estimate and forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |