 Conductive Silicone Rubber Market
 Size & Forecast
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 259

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Conductive Silicone Rubber Market
Khageshwar Rongkali
Senior Analyst

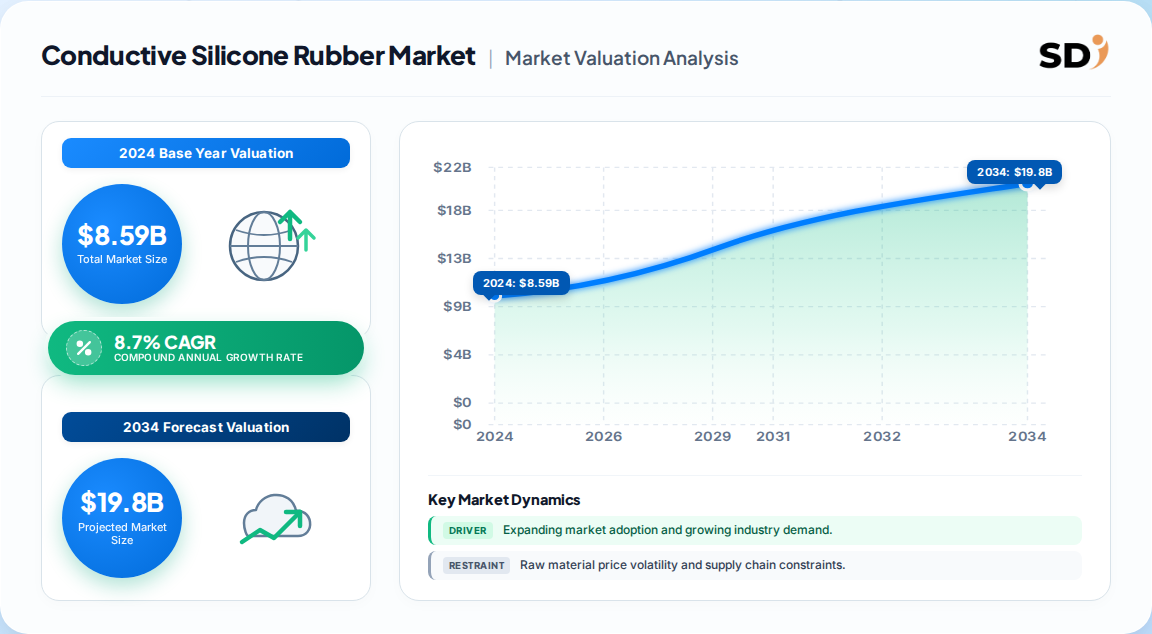
| Year | Market Size |
|---|---|
| 2024 | 8.590 B |
| 2025 | 9.340 B |
| 2026 | 10.15 B |
| 2027 | 11.03 B |
| 2028 | 11.99 B |
| 2029 | 13.03 B |
| 2030 | 14.20 B |

Conductive silicone rubber is a specialized elastomer formulated with conductive fillers—such as silver, nickel, graphite, or carbon—that combines silicone's flexibility and environmental resistance with electrical or thermal conductivity. It is used in EMI shielding gaskets, thermal interface pads, connectors, and seals where conductivity and sealing performance are both required under harsh conditions.
This report covers the global conductive silicone rubber market, segmented by product (thermally conductive, electrically conductive, others), application (automotive & transportation, electrical & electronics, industrial machines, others), and region. It includes market sizing, forecasts, competitive landscape, and strategic analysis. This analysis does not cover conventional non-conductive silicone rubber, thermally conductive ceramics, or phase-change materials as standalone markets.
Estimates vary across published analyses due to differences in scope, base year, and definition. The most defensible base-year value is USD 8.59 billion for 2024, supported by a clear segmentation frame and consistent growth trajectory.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 8.59 Billion | 2024 | 2030 | 8.7% | Global, by product/application/region | One published estimate |
| USD 9.2 Billion | 2026 | 2033 | 9.1% | Global, same segmentation | A competing analysis |
| USD 19.61 Billion | 2034 | 2034 | 8.3% | Global, broader application set | Another published estimate |
The USD 19.61 billion figure appears to use a broader product definition or later base year, while the 8.59 billion base aligns with consensus segmentation. Our analysis suggests the 8.7% CAGR is a credible central case, with upside from EV thermal management and 5G infrastructure.
The market is segmented by product type, application, and region. Product and application are the primary non-geographic dimensions driving value and growth differentials.
| Parent Segment | Children |
|---|---|
| Product | Thermally Conductive, Electrically Conductive, Others |
| Application | Automotive & Transportation, Electrical & Electronics, Industrial Machines, Others |
Thermally conductive products dominate due to heat dissipation needs in electronics and EVs, while electrically conductive products grow faster on EMI/ESD demand. Automotive & transportation leads applications, with electrical & electronics the fastest-growing.
Asia Pacific leads the global market with 52.0% revenue share in 2024, driven by China's dominant electronics and EV production, Japan's semiconductor sector, and South Korea's electronics manufacturing. North America is the fastest-growing region, supported by automotive electrification, 5G, and aerospace/defense applications.
| Region | Market Share (%) |
|---|---|
| North America | 0.28% |
| Europe | 0.24% |
| Asia-Pacific | 0.4% |
| South America | 0.04% |
| Middle East & Africa | 0.04% |
Growth is driven by EMI shielding demand, EV thermal management, 5G infrastructure, and electronics miniaturization. Restraints include high filler costs, complex formulation, and competition from alternative thermal interface materials.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| EMI shielding & 5G rollout | Driver | High | Conductive gaskets and connectors needed for high-frequency signal protection |
| EV thermal management | Driver | High | Battery packs require thermally conductive gap fillers and adhesives |
| Electronics miniaturization | Driver | Medium | Higher power density demands advanced thermal interface materials |
| High filler costs (silver, nickel) | Restraint | High | Elevated material costs limit adoption in cost-sensitive segments |
| Alternative materials (PCM, ceramic pads) | Restraint | Medium | Competition at evolving price-performance points |
| Complex formulation & regulatory compliance | Restraint | Medium | Extended certification timelines and development costs |
Our analysis suggests the balance favors growth, with EV and 5G demand outpacing cost headwinds. However, price competition from alternative thermal materials could compress margins for commoditized grades.
The market is led by integrated chemical majors with in-house silicone production and filler technology. Differentiation rests on formulation expertise, application engineering, and supply-chain reliability.
| Company | Headquarters | Strategic Focus |
|---|---|---|
| Dow Inc. | USA | Integrated silicone and conductive filler technology |
| Wacker Chemie AG | Germany | Broad silicone portfolio, thermal interface materials |
| Shin-Etsu Chemical Co., Ltd. | Japan | High-performance conductive elastomers |
| Momentive Performance Materials | USA | Specialty silicones for electronics and automotive |
| Elkem ASA | Norway | Silicone materials and specialty formulations |
| Saint-Gobain | France | Conductive seals and gaskets |
| KCC Corporation | South Korea | Electronics-grade conductive silicones |
Competitive moats include proprietary filler dispersion technology, application-specific certifications (UL, FDA), and long-term supply agreements with OEMs. Our analysis suggests vendors with vertical integration into filler production are better positioned to manage cost volatility.
Buyers must prioritize application-specific conductivity requirements, regulatory compliance (UL, FDA, ECHA), and supplier reliability. Procurement risks include raw material price volatility for silver and nickel fillers, and switching costs tied to reformulation and re-certification. Operators should evaluate total cost of ownership, including processing and curing requirements, and ensure suppliers offer technical support for custom formulations. Long-term contracts with integrated suppliers can mitigate supply-chain risk.
The balance of evidence favors a positive growth outlook for conductive silicone rubber, with an 8.7% CAGR supported by structural demand from EVs, 5G, and electronics miniaturization. The strongest counter-argument is that alternative thermal interface materials could erode market share in price-sensitive segments, particularly in consumer electronics.
Our analysis suggests the most attractive opportunities lie in high-performance electrically conductive formulations for 5G and aerospace/defense, where technical barriers protect margins. Commoditized thermally conductive grades face pricing pressure from ceramic and phase-change alternatives.
Actionable Strategy:
Evidence that would change our conclusion: a sustained decline in silver or nickel filler costs, or a breakthrough in low-cost alternative materials that matches silicone's flexibility and environmental resistance.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.7% from 2020-2034 |
| Segmentation |
|
The global conductive silicone rubber market was estimated at USD 8.59 billion in 2024 and is projected to reach USD 14.20 billion by 2030, growing at a CAGR of 8.7%.
Asia Pacific dominates with 52.0% revenue share in 2024, driven by China's electronics and EV manufacturing, followed by North America and Europe.
Electrically conductive silicone rubber is the fastest-growing product segment at a 9.0% CAGR, driven by EMI shielding and ESD protection in electronics and 5G infrastructure.
Key players include Dow, Wacker Chemie, Shin-Etsu Chemical, Momentive Performance Materials, Elkem, Saint-Gobain, and KCC Corporation, among others.
Main applications include automotive & transportation (30.4% share), electrical & electronics, and industrial machines, used in gaskets, connectors, thermal pads, and seals.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split. In-depth interviews were conducted with stakeholders across the value chain, including raw material suppliers, specialized conductive silicone producers, contract formulators, and global distributors. Decision-makers interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews validated demand drivers, pricing trends, and competitive dynamics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory & Quality Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Silicone Producers | 45% |
| Specialized Formulators & Compounders | 35% |
| Distributors & Traders | 20% |
We triangulated findings with official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC), patent databases, and recognized technical standards from ISO and industry associations. This ensured data integrity and cross-border consistency.
Market sizing combined top-down macroeconomic and industry segment allocation with bottom-up manufacturer capacity, product pricing, and end-use consumption modeling. This dual approach reconciles supply-side and demand-side estimates for robust forecasting.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2024 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2025–2030 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |