 Us Sustained Release Coatings Market
US Sustained Release Coatings Market Outlook 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 271

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Sustained Release Coatings Market
Khageshwar Rongkali
Senior Analyst

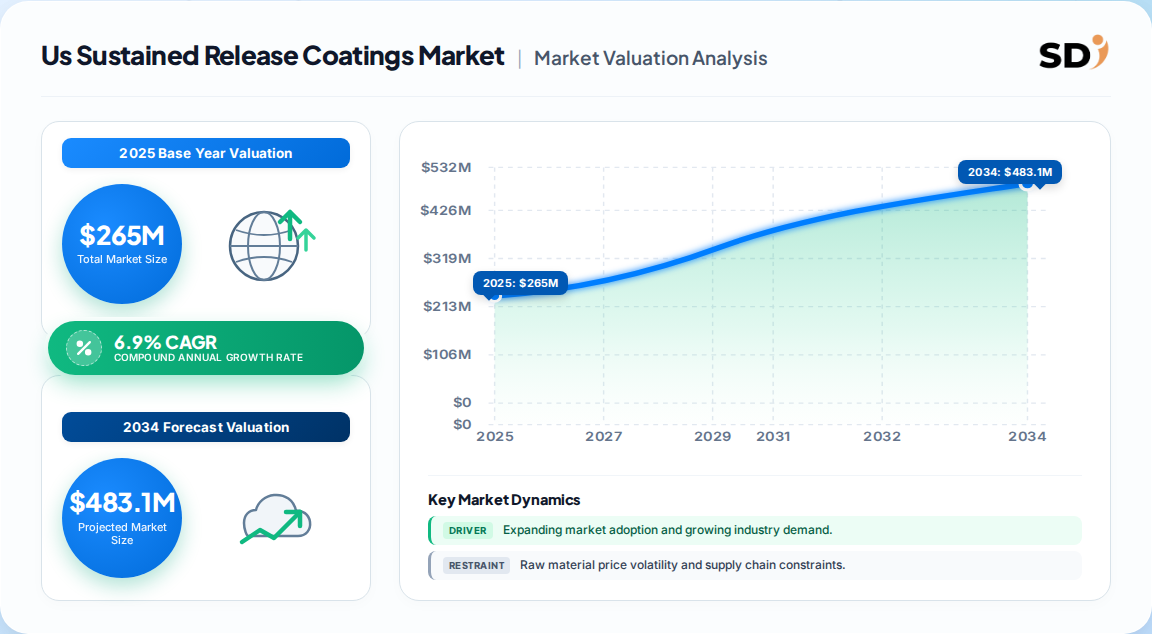
| Year | Market Size |
|---|---|
| 2025 | 265.0 M |
| 2026 | 283.0 M |
| 2027 | 303.0 M |
| 2028 | 324.0 M |
| 2029 | 346.0 M |
| 2030 | 370.0 M |
| 2031 | 395.0 M |

The US sustained release coatings market covers functional polymer coating systems applied to oral solid dosage forms — tablets, capsules, pills and multiparticulates — to modulate active pharmaceutical ingredient release over an extended period. It spans excipient supply, contract coating services and technical formulation support sold into pharmaceutical, nutraceutical and laboratory end uses.
This analysis covers sustained release and modified-release coating systems sold into the United States across substrate types (tablets, capsules, pills, multiparticulates), polymer chemistries (cellulosics, polyvinyl and cellulose acetate, methacrylic acid, PEG and others), application modes (in vitro and in vivo) and end-use industries (pharmaceuticals, nutraceuticals, laboratories). Value reflects coating material and formulated system revenue, not coating equipment or contract manufacturing service fees.
This analysis does not cover immediate-release film coatings, enteric coatings sold as standalone categories without sustained-release function, agricultural or veterinary controlled-release formulations, or coating machinery and pan/FBGC equipment.
The US market is best estimated at approximately USD 265 Million in 2025, anchoring a global category of roughly USD 685 Million. Published estimates diverge by a factor of more than ten, which reflects genuine definitional disagreement rather than data error.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 739 Million | 2025 | 2032 | 6.1% | Global; coatings for oral solids, narrow polymer scope | One published estimate |
| USD 336 Million | 2025 | 2033 | 7.3% | Global; excludes some multiparticulate systems | A competing analysis |
| USD 685 Million | 2025 | 2035 | 6.8% | Global; broad polymer and end-use inclusion | A competing analysis |
| USD 5.6 Billion | 2022 | 2032 | 7.1% | Global; likely includes all controlled-release delivery | A competing analysis |
The USD 5.6 Billion figure is almost certainly an all-modality controlled-release number rather than a coatings-only measure; treating it as a coating market would overstate the addressable pool by an order of magnitude. Our analysis suggests the USD 685 Million global base is the most defensible, because its polymer segmentation and end-use breadth match how excipient suppliers actually report revenue. Applying a 38% North American share and a ~76% US concentration within the region yields the ~USD 265 Million US figure used throughout this report.
Segmentation follows three independent axes — substrate, polymer chemistry and application mode — with polymer chemistry the most commercially decisive because it governs both release kinetics and regulatory documentation burden.
| Parent segment | Children |
|---|---|
| By Substrate | Tablets, Capsules, Pills, Multiparticulate Powder |
| By Polymer Material | Ethyl & Methyl Cellulose, Polyvinyl & Cellulose Acetate, Methacrylic Acid, PEG, Others |
| By Application | In Vitro, In Vivo |
| By End-Use Industry | Pharmaceuticals, Nutraceuticals, Laboratories |
Two structural notes matter for buyers. First, the in vivo segment carries roughly 69–71% of value in most published splits, but this is a measurement artifact of how trials are commissioned rather than a proxy for where formulation spend occurs. Second, multiparticulate powder is under-reported across nearly every published dataset, which means tablet shares are likely modestly overstated.
Demand concentrates heavily in the Mid-Atlantic and Northeast pharmaceutical manufacturing corridor, followed by the Midwest and California, mirroring the geographic footprint of branded and generic oral solid dosage production.
| Region | Market Share (%) |
|---|---|
| North America | 0.38% |
| Europe | 0.25% |
| Asia-Pacific | 0.24% |
| South America | 0.07% |
| Middle East & Africa | 0.06% |
Our analysis suggests the South will gain share through 2032 as generic manufacturers relocate capacity toward lower-cost states, though the Northeast will retain leadership on value because complex modified-release formulations remain anchored to established technical teams.
Growth is driven by chronic disease prevalence and patient-compliance economics; the binding constraint is formulation and regulatory complexity, not demand.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Chronic disease prevalence | Driver | High | Long-acting oral regimens for diabetes, cardiovascular and CNS conditions |
| Patient compliance mandates | Driver | High | Reduced dosing frequency lowers hospitalization and adherence failure |
| Generic and 505(b)(2) reformulation pipelines | Driver | Moderate | Lifecycle extension creates recurring coating demand |
| Polymer-API compatibility constraints | Restraint | High | Not all actives tolerate sustained-release matrices |
| Regulatory documentation burden | Restraint | High | Excipient safety dossiers and bioequivalence studies add 6–18 months |
| Small-batch economics | Restraint | Moderate | Coating development costs deter smaller formulators |
The balance favors sustained growth. Our analysis suggests the restraint side is a margin issue rather than a volume issue: demand exists, but the technical and regulatory cost of serving it concentrates value among suppliers with mature dossiers, effectively raising barriers rather than suppressing the category.
Competition is moderately fragmented, with a handful of global polymer and coating specialists holding disproportionate share through formulation IP, regulatory files and technical service networks.
| Vendor | Primary strength | Competitive moat |
|---|---|---|
| BASF SE | Broad excipient portfolio | Integrated polymer supply and global documentation |
| Evonik | Methacrylic acid copolymer systems | Deep patent estate and formulation literature |
| Colorcon | Coating systems and technical service | Application labs and formulation support depth |
| Coating Place, Inc. | Contract coating and multiparticulates | Specialized process know-how |
| Ashland | Cellulosic polymers | Cellulose chemistry integration |
| Eastman Chemical | Cellulose acetate esters | Raw material backward integration |
The moat is documentation, not chemistry. Substituting an established polymer typically triggers fresh bioequivalence work, meaning incumbents defend share through regulatory lock-in. Our analysis suggests challengers should target under-documented niche chemistries — particularly colon-targeted and biodegradable systems — rather than contesting commoditized cellulosics head-on.
Selection should be driven by four criteria in strict priority order: polymer-API compatibility, regulatory dossier completeness, supply continuity, and total cost of formulation. Cost ranks last because a coating substitution that fails bioequivalence erases any unit-price saving many times over.
Procurement risk concentrates in single-source cellulosic and methacrylic supply chains, where qualification lead times of six to twelve months leave little flexibility. Buyers should secure dual-source qualification before volume commitments and require suppliers to disclose change-control policies for manufacturing site transfers.
Switching costs are structurally high. Reformulating a coating system typically requires stability studies, dissolution profile revalidation and, in some cases, a supplemental filing — meaning vendor selection is effectively a multi-year commitment. Operators should treat coating supplier onboarding as a capital decision and negotiate technical service support and documentation access into the initial agreement, not as an afterthought.
The balance of evidence favors a steady, quality-led growth story rather than a high-velocity one. A ~6.9% US CAGR is credible because it tracks underlying oral solid dosage volume plus a modest mix shift toward modified-release formats — not because of any single disruptive catalyst. The strongest counter-argument is that the USD 5.6 Billion global figure implies a far larger opportunity; our view is that this figure conflates all controlled-release delivery and should not be used to size a coating-only procurement strategy.
Strategically, the decisive variable through 2032 is not demand but documentation capacity. Suppliers who can shorten a customer's path from coating selection to regulatory submission will capture disproportionate share of new formulation wins, even at premium pricing. Conversely, buyers who treat coating vendors purely as commodity suppliers will absorb reformulation risk that could have been contracted away.
What would change this conclusion: a significant shift toward non-oral delivery modalities, or a regulatory pathway that materially reduces bioequivalence burden for coating substitutions. Either would compress incumbent moats and shift value toward price-competitive suppliers. Our published dataset does not yet show evidence of either.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.9% from 2020-2034 |
| Segmentation |
|
The US market is estimated at approximately USD 265 Million in 2025, representing roughly three-quarters of the North American regional pool. Published global estimates vary widely due to differing scope definitions, so buyers should confirm whether a figure includes equipment or contract services.
Growth is forecast at approximately 6.9% CAGR through 2032. This tracks oral solid dosage volume growth plus a gradual shift toward modified-release formats, rather than reflecting any single disruptive catalyst in the category.
Tablets lead with roughly 52–59% of value, driven by manufacturing scale, cost efficiency and prescribing volume. Capsules and multiparticulate systems are the faster-growing secondary formats, particularly for pellet-based and colon-targeted applications.
BASF, Evonik, Colorcon, Coating Place, Ashland and Eastman are among the leading suppliers. Competition centers on formulation IP, regulatory documentation depth and technical service rather than unit pricing alone.
Regulatory documentation burden and polymer-API compatibility expertise are the primary barriers. Substituting an established coating typically triggers fresh bioequivalence work, which locks customers in and protects incumbent suppliers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Primary fieldwork comprised structured in-depth interviews with stakeholders across the sustained release coating value chain: specialty polymer and excipient producers, contract coating and formulation houses, oral solid dosage manufacturers, and technical distributors serving pharmaceutical and nutraceutical clients. Interviews targeted decision-makers including VP-level sourcing leads, heads of formulation R&D, technical directors, and commercial operations managers, with quota sampling to ensure representation across branded, generic and contract manufacturing business models.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Formulation & R&D Directors | 38% |
| Procurement & Sourcing Leads | 34% |
| Regulatory & Quality Managers | 28% |
| Company Type | Representation (%) |
|---|---|
| Polymer & Excipient Producers | 42% |
| Contract Coating & Formulation Houses | 33% |
| Technical Distributors | 25% |
Secondary validation drew on UN Comtrade and US ITC trade flow data for cellulose derivatives and methacrylic polymers, Eurostat and WTO tariff schedules, corporate annual filings and 10-K disclosures from publicly listed excipient suppliers, patent databases for coating polymer IP landscapes, and technical standards published by USP, the International Pharmaceutical Excipients Council, and FDA guidance documents on modified-release dosage forms.
Sizing was triangulated simultaneously through top-down and bottom-up methods. The top-down approach allocated macroeconomic pharmaceutical manufacturing output to the oral solid dosage segment and applied coating intensity factors by substrate type. The bottom-up approach modeled manufacturer coating material volumes, average formulated system pricing, and end-use consumption by dosage form, reconciling discrepancies at the polymer chemistry level.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |