 Textile Fiber Market
 Size, Share & Forecast to 2030
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 273

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Textile Fiber Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2024 | 48.70 B |
| 2025 | 50.90 B |
| 2026 | 53.20 B |
| 2027 | 55.60 B |
| 2028 | 58.10 B |
| 2029 | 60.70 B |
| 2030 | 63.40 B |

The textile fiber market encompasses the production and trade of natural and synthetic fibers — including cotton, wool, polyester and nylon — used to manufacture fabrics for apparel, home textiles, automotive, construction and industrial applications.
This analysis covers global textile fiber production, trade, pricing and consumption across natural and synthetic product categories and major end-use segments, including fashion, automotive, building and construction. This analysis does not cover finished fabric manufacturing, garment retailing, or the textile machinery market.
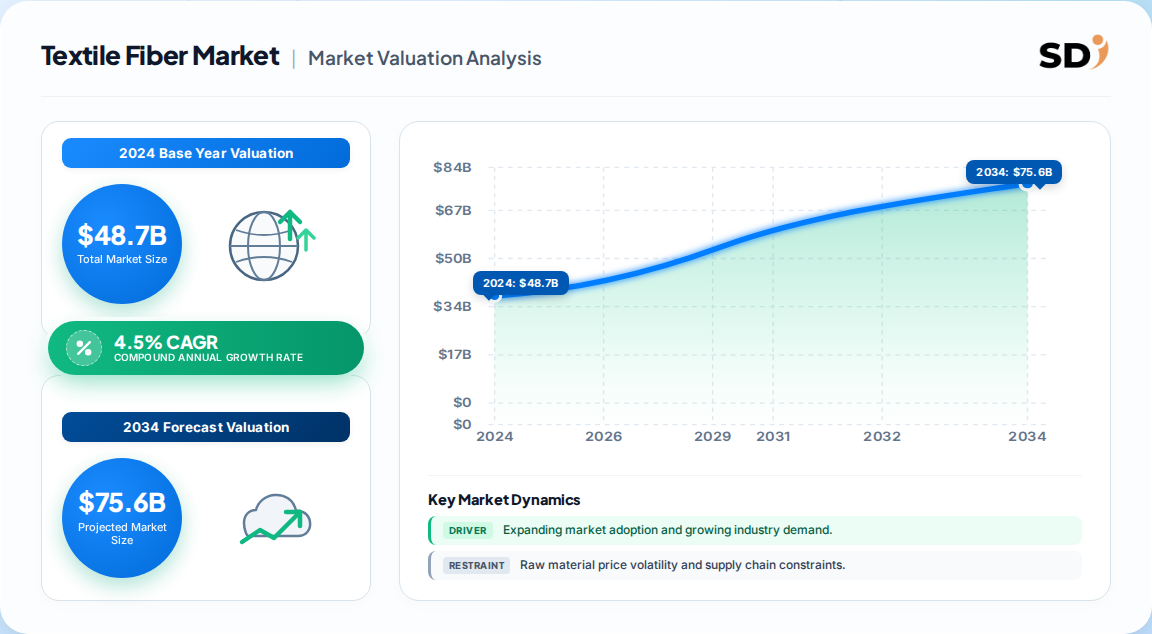
The balance of published estimates places the global textile fiber market at 48.7 Billion in 2024, rising to 63.4 Billion by 2030 at a 4.5% CAGR, with a 2026 midpoint near 53.2 Billion.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 48.7 Billion | 2024 | 2030 | 4.5% | Fiber-level production & trade | Published industry estimate |
| 53.2 Billion | 2026 | 2030 | 4.5% | Fiber-level revenue, mid-cycle | Published industry estimate |
| 63.4 Billion | 2030 | 2030 | 4.5% | Forecast endpoint | Published industry estimate |
Our analysis suggests the fiber-level figure is the most defensible for procurement planning, because it isolates raw fiber value rather than blended fabric value, which inflates broader textile benchmarks by roughly an order of magnitude. The narrower scope is the safer anchor for input-cost modeling.
Segmentation runs along two axes: product type (natural versus synthetic fibers) and end-use, where fashion and clothing account for more than half of fiber consumption.
| Parent segment | Children |
|---|---|
| By Product | Natural Fiber (cotton, wool, silk, jute, hemp), Synthetic Fiber (polyester, nylon, acrylic, viscose) |
| By End-use | Fashion & Clothing, Automotive, Building & Construction, Home Textiles, Industrial & Technical |
Our analysis indicates the polyester sub-segment warrants disproportionate attention, since synthetic fibers collectively hold 52.0% share and polyester is the single largest contributor to that total.
Asia Pacific leads the global textile fiber market with 47.3% revenue share in 2024, anchored by China's polyester capacity and India's cotton output. Europe and North America follow with higher-value, sustainability-driven demand.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.47% |
| North America | 0.18% |
| Europe | 0.16% |
| South America | 0.08% |
| Middle East & Africa | 0.11% |
| Parent region | Children |
|---|---|
| Asia Pacific | China, India, Japan, South Korea, Bangladesh, Indonesia |
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Turkey |
| Central & South America | Brazil, Argentina, Mexico |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
| Region | 2024 Share |
|---|---|
| Asia Pacific | 47.3% |
| North America | 17.6% |
| Europe | 16.1% |
| Middle East & Africa | 11.1% |
| Central & South America | 7.9% |
The concentration implies that any disruption to Asian fiber supply — whether tariff, energy or logistics — transmits globally within a single procurement cycle.
Demand growth is driven by apparel consumption, e-commerce penetration and technical textile adoption, while volatile raw material pricing and environmental compliance restrain margin expansion.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising disposable income | Driver | High | Higher apparel and home textile spend |
| E-commerce expansion | Driver | High | Broader access, faster fashion cycles |
| Technical textiles growth | Driver | Moderate | Automotive, medical, construction demand |
| Sustainability mandates | Restraint | High | Compliance cost, reformulation burden |
| Cotton price volatility | Restraint | High | Margin compression, substitution to polyester |
Our analysis suggests drivers outweigh restraints through 2030, but the balance tilts toward polyester on cost grounds wherever cotton volatility persists.
The competitive field is moderately concentrated, with large integrated synthetic producers and diversified natural fiber suppliers competing on scale, sustainability credentials and vertical integration.
| Vendor type | Strategic strength | Key moat |
|---|---|---|
| Integrated synthetic producers | Scale and cost leadership | Vertical integration |
| Natural fiber suppliers | Origin and traceability | Supply relationships |
| Specialty fiber innovators | Recycled and bio-based fibers | IP and certification |
| Diversified textile groups | Portfolio breadth | Distribution reach |
Differentiation increasingly rests on certified recycled content and traceable origin, which command premium pricing in European and North American markets.
Procurement strategy should anchor on dual-sourcing across natural and synthetic fibers to hedge cotton volatility, with selection criteria prioritizing certified recycled content, traceability documentation and compliance with emerging extended producer responsibility rules. Switching costs are moderate for commodity fibers but rise sharply for specialty and certified fibers, where qualification cycles run long. Operators should monitor energy costs in Asian production hubs and build contractual price-adjustment mechanisms to absorb raw material swings.
The balance of evidence favors a moderate-growth outlook near 4.5% annually, with value migrating toward sustainable and technical fibers rather than volume-driven commodity apparel. The strongest counter-argument is that recycled fiber capacity could scale faster than expected, compressing conventional fiber pricing and pulling the CAGR below consensus.
Our analysis suggests the 2030 endpoint is achievable but unevenly distributed: Asia Pacific retains volume leadership while Europe captures margin from certified sustainable fibers. Operators that lock in traceable supply now will be positioned to capture that premium.
Evidence that would change this conclusion: a sharp decline in cotton prices, accelerated recycled-capacity buildout, or a major trade policy shift altering Asian export economics.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.5% from 2020-2034 |
| Segmentation |
|
The global textile fiber market was valued at 48.7 Billion in 2024 and is projected to reach 63.4 Billion by 2030, growing at a 4.5% CAGR over the forecast period.
Asia Pacific dominates with 47.3% revenue share in 2024, driven by China's synthetic capacity and India's cotton production, followed by North America and Europe.
Building and construction is the fastest-growing end-use at 4.7% CAGR, driven by fiber use in concrete reinforcement, roofing, insulation and wall coverings.
Synthetic fiber held the largest product share at 52.0% in 2024, led by polyester's cost-effectiveness, durability and crease resistance versus natural fibers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with raw material suppliers, specialized fiber producers, contract formulators and global distributors. Decision-makers interviewed include VP-level Sourcing leads, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring validation of both volume and pricing assumptions at each supply tier.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement | 35% |
| Heads of R&D | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material Suppliers | 30% |
| Specialized Fiber Producers | 35% |
| Contract Formulators | 20% |
| Global Distributors | 15% |
Findings were cross-checked against UN Comtrade, WTO and US ITC trade flows, Eurostat industrial statistics, corporate annual filings (10-K, SEC disclosures and investor presentations), patent databases, and recognized technical standards bodies and industry associations. No third-party market research publishers were used as validation sources.
Market sizing combined simultaneous Top-Down allocation from macroeconomic and industry segment data with Bottom-Up modeling of manufacturer capacity, product pricing and end-use consumption. Divergences between the two approaches were reconciled through targeted follow-up interviews.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |