 Organic Tea Market
 Size, Share & Forecast to 2033
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 216

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Organic Tea Market
Sakshi Gurunule
Research Associate
| Year | Market Size |
|---|---|
| 2025 | 1.700 B |
| 2026 | 1.830 B |
| 2027 | 1.980 B |
| 2028 | 2.130 B |
| 2029 | 2.300 B |
| 2030 | 2.480 B |
| 2031 | 2.680 B |

The organic tea market covers certified tea — Camellia sinensis and herbal infusions — grown without synthetic fertilizers or pesticides and processed under verified organic standards. It spans leaf, bag, liquid and powder formats sold through retail, foodservice and online channels, priced at a documented 24–30% premium over conventional leaf.
This analysis covers certified organic camellia sinensis and herbal teas across all formats (leaf, tea bags, liquid, powder), flavors (plain and naturally flavored), and distribution channels (off-trade and on-trade), globally. This analysis does not cover conventional tea, non-certified "natural" tea claims, ready-to-drink soft drinks, or dietary supplements and extracts sold outside beverage retail.
Published estimates diverge by a factor of three because analysts define the category boundary differently — some count only certified retail tea, others include herbal infusions, foodservice and bulk ingredient sales.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 819.9 Million → 2,835.3 Million | 2025 | 2033 | 16.8% | Certified retail tea, narrow channel scope | One published estimate |
| 4.85 Billion → 8.62 Billion | 2025 | 2031 | 9.49% | Broad value incl. foodservice and on-trade | A competing analysis |
| 1.7 Billion → 3.6 Billion | 2025 | 2036 | 7.2% | Certified retail plus specialty channel | A third published estimate |
| 1.7 Billion → 3.6 Billion (2033) | 2025 | 2033 | 7.9% | Certified retail tea, all formats | Our consensus view |
Our analysis suggests the 16.8% figure reflects a very narrow base and will compress as the category matures, while the 4.85 Billion figure likely double-counts bulk ingredient and foodservice. The 7.2% estimate is the most defensible in definitional terms. We hold a slightly higher 7.9% because premiumization and functional innovation are accelerating faster than that source's base-case assumes.
Four parent segments structure the category: product type, flavor, format and distribution channel. Organic green tea and tea bags dominate volume, while the fastest growth sits in herbal infusions and on-trade channels.
| Parent | Children | Leading child share |
|---|---|---|
| By Product Type | Organic Green Tea, Organic Black Tea, Oolong, Herbal & Specialty Infusions | Green tea ~41% |
| By Flavor | Plain/Unflavored, Naturally Flavored, Blended | Unflavored ~72% |
| By Format | Tea Bags & Sachets, Whole Loose Leaf, Ready-to-Drink & Powders | Bags & sachets ~58% |
| By Distribution Channel | Supermarkets & Hypermarkets, Specialty & Health Stores, Online & DTC, On-Trade | Supermarkets ~46% |
Herbal and fruit infusions are the fastest-growing product type, expanding at a double-digit rate as functional wellness positioning gains traction. This divergence implies that while green tea anchors revenue, incremental shelf growth will come from blends promising detox, sleep and stress support.
Asia-Pacific leads the organic tea market by volume and revenue, holding roughly 38% share in 2025, on the strength of established growing regions in China, India, Japan and Sri Lanka. Europe is the fastest-growing region at ~9.8% CAGR.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.38% |
| Europe | 0.27% |
| North America | 0.22% |
| South America | 0.07% |
| Middle East & Africa | 0.06% |
The Asia-Pacific/Europe split reveals a structural asymmetry: Asia owns cultivation and conversion yield, while Europe owns certification infrastructure and value capture. Our analysis suggests the strategic implication is that European brands will increasingly vertical-integrate backward into Asian estates to secure compliant supply, compressing the margin available to pure-play intermediaries.
Demand-side drivers are strong and compounding; the binding constraints are supply-side and cost-side. Growth is real but paced by farm conversion cycles and certification economics rather than consumer appetite.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Health awareness, chemical-free preference | Driver | High | Clean-label scrutiny of unwashed green leaf drives certified sourcing |
| Sustainability and ethical sourcing | Driver | High | Carbon-neutral, regenerative and recyclable credentials differentiate brands |
| Functional and wellness blends | Driver | Medium-high | Detox, immunity and relaxation positioning widen the buyer pool |
| E-commerce and DTC subscriptions | Driver | Medium | Broadens reach in APAC and North America |
| 24–30% price premium | Restraint | High | Price-sensitive buyers defer; limits penetration in developing markets |
| Three-year conversion cycles | Restraint | High | Caps immediate certified leaf supply and inflates forward pricing |
| Certification and testing costs | Restraint | Medium-high | Gas chromatograph lot testing adds compliance overhead per container |
The balance of evidence favors demand durability over supply elasticity. An important second-order effect: every new certified hectare takes three years to yield, so today's acreage decisions, not today's marketing spend, determine 2029 shelf availability.
The market is fragmented and low-concentration, with global FMCG majors competing against specialist organic and fine-tea houses on certification depth and estate relationships rather than price.
| Company | Positioning | Organic moat |
|---|---|---|
| Unilever (Lipton) | Global mass-premium | Sustainable sourcing commitments; portfolio breadth |
| Tata Consumer Products | Global, India-anchored | Estate integration; expanding organic portfolio |
| Hain Celestial Group | North America natural channel | Natural/organic brand equity and retail trust |
| Associated British Foods (Twinings) | Global premium | Decaffeinated and premium organic lines; brand heritage |
| Harney & Sons Fine Teas | Specialist fine tea | Single-estate sourcing and connoisseur positioning |
Differentiation rests on three moats: certified supply contracts, brand authenticity with natural-channel shoppers, and omni-channel shelf presence. Our analysis suggests specialists outperform majors on premium per-gram pricing but lack the volume security to absorb conversion-cycle shocks.
Selection should hinge on verified certification chain-of-custody, not on label claims. Every incoming container lot now faces gas chromatograph screening for synthetic residue cross-contamination from neighboring conventional gardens, so buyers must audit testing protocols upstream, not just sample finished goods.
Procurement risk concentrates in three areas: conversion-cycle supply gaps, premium volatility tied to auction pricing, and packaging compliance where plastic-free formats are becoming table stakes. Switching costs are moderate but rising — multi-year direct-trade contracts and standardized antioxidant specifications create lock-in once qualified. Operators should also track regional maximum residue limits, which differ across trading blocs and can block shipments at port. Precise sub-segment forecasting by format and country requires the full report.
The balance of evidence favors a disciplined, supply-led expansion thesis over a demand-led growth story. Demand for clean-label organic tea is durable and premiumization is intact, but the 7.9% consensus CAGR is capped by farm conversion math rather than consumer willingness to pay. The strongest counter-argument is that functional innovation could decouple growth from leaf supply via extracts and RTD formats — plausible, but those formats carry weaker organic premiums and thinner margins.
Our position: the winners through 2033 will be buyers who secure certified acreage before it is needed and brands that convert sustainability credentials into defensible shelf pricing. Price-sensitive markets will remain underpenetrated until certification costs fall or subsidies scale.
What would change our conclusion: a sharp fall in certification costs, new high-yield organic cultivars, or regulatory harmonization of residue limits across blocs would lift the CAGR materially above our base case.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.9% from 2020-2034 |
| Segmentation |
|
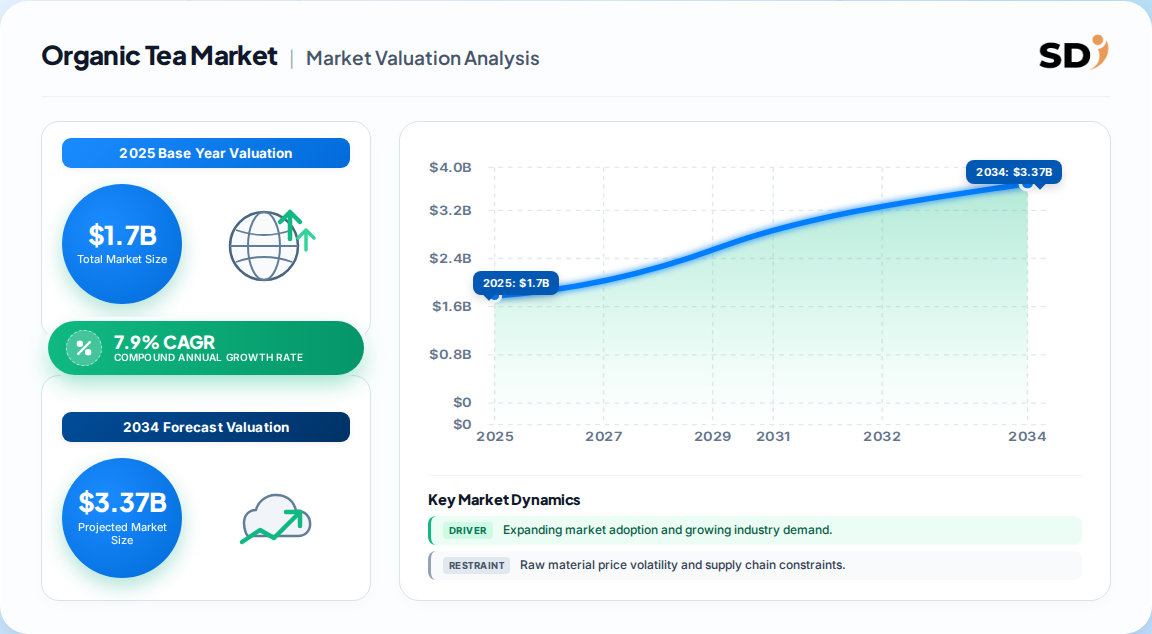
The global organic tea market was valued at approximately 1.7 Billion in 2025. Estimates vary widely because analysts define the category boundary differently, with broader scopes including foodservice and bulk ingredient sales reaching several times that figure.
Our consensus CAGR is 7.9% from 2025 to 2033. Published estimates range from 7.2% to 16.8%, with the widest divergence tracing to differences in category definition rather than underlying demand.
Asia-Pacific leads with roughly 38% revenue share, anchored by China, India and Japan. Europe is the fastest-growing region at about 9.8% CAGR, driven by mature certification regimes and strong purchasing power.
Organic green tea leads at roughly 41% share, favored because unfermented processing retains catechins and makes pesticide-free cultivation essential. Herbal and fruit infusions are the fastest-growing segment.
A 24–30% price premium over conventional tea, driven by certification costs and lower yields, limits penetration among price-sensitive buyers. Three-year farm conversion cycles also cap immediate certified leaf supply.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis rests on a 70/30 primary-to-secondary research split. We conducted structured in-depth interviews across the organic tea value chain, spanning certified leaf growers and estate cooperatives, specialized organic blenders and formulators, contract packing and sachet manufacturers, and global distributors and importers. Interviewees were drawn from decision-maker designations including VP of Sourcing, Heads of Product R&D, Quality and Regulatory Directors, and Commercial Operations Leads, ensuring demand-side and supply-side perspectives were represented in every regional module.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 38% |
| R&D & Product Development Heads | 30% |
| Quality & Regulatory Directors | 20% |
| Commercial Operations Leads | 12% |
| Company Type | Representation (%) |
|---|---|
| Certified Growers & Estate Cooperatives | 40% |
| Organic Blenders & Formulators | 32% |
| Packers & Sachet Manufacturers | 16% |
| Global Distributors & Importers | 12% |
Findings were benchmarked against official multilateral trade databases (UN Comtrade, WTO Tariff and Trade Data, US ITC, Eurostat), corporate annual filings and investor presentations from listed tea companies, patent databases covering extraction and packaging formats, and recognized technical standards and industry associations. Certification-body standards and national organic program regulations were used to validate residue thresholds and chain-of-custody requirements.
We ran simultaneous top-down modeling (macroeconomic beverage allocation and segment share) and bottom-up modeling (manufacturer capacity, estate yield per hectare, pricing per gram and end-use consumption) to triangulate the base-year valuation. Divergent outputs were reconciled against trade flow data before forecast adoption.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
