 Middle East Africa Liquid Dietary Supplements Market
 2025
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 244

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East Africa Liquid Dietary Supplements Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2024 | 208.0 M |
| 2025 | 230.0 M |
| 2026 | 255.0 M |
| 2027 | 282.0 M |
| 2028 | 313.0 M |
| 2029 | 347.0 M |
| 2030 | 384.0 M |

The Middle East Africa liquid dietary supplements market comprises nutrient-enriched liquid products — vitamins, minerals, botanicals, proteins and amino acids — formulated for ready absorption and ease of consumption. These supplements serve immunity, energy, fitness, prenatal and clinical nutrition needs across GCC, North African and Sub-Saharan markets.
This analysis covers liquid-format dietary supplements sold across the Middle East and Africa, segmented by ingredient, type (OTC vs prescribed), application, end user and distribution channel. This analysis does not cover solid-format supplements (tablets, capsules, soft gels), functional foods and beverages, or pharmaceutical drugs.
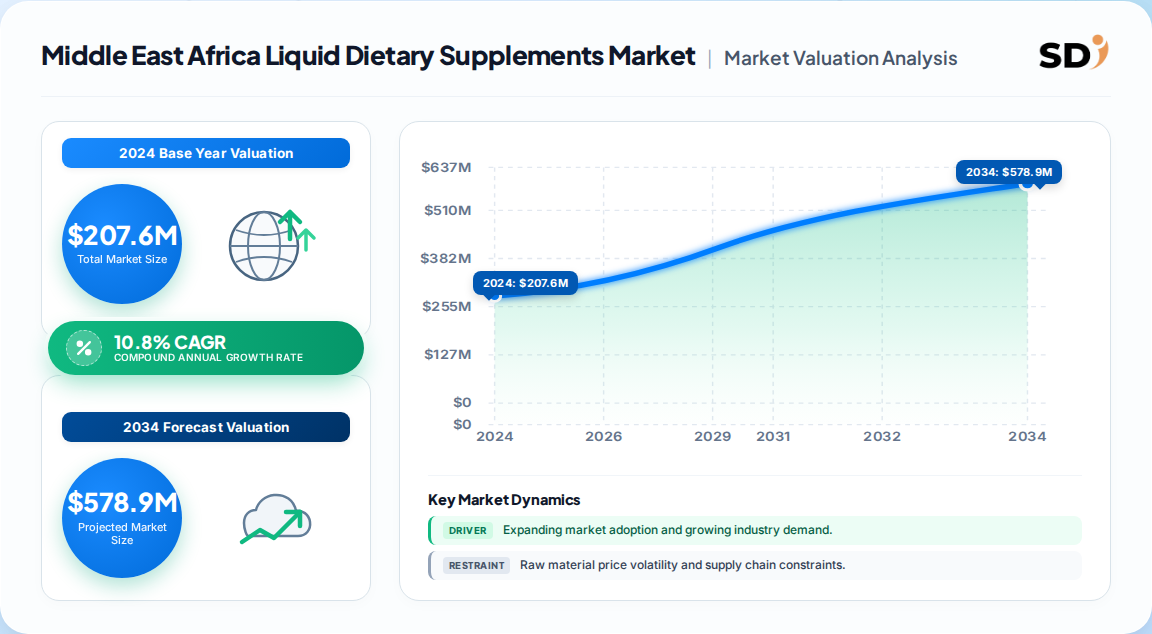
Published estimates diverge sharply — from 207.6 Million in 2024 at 10.8% CAGR to 1.31 Billion in 2024 at 8% CAGR — because some analysts define the category to include functional beverages and fortified drinks. The narrower definition is more defensible for procurement planning.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 207.6 Million | 2024 | 2030 | 10.8% | Liquid supplements only, all channels | A published industry estimate |
| 1.31 Billion | 2024 | 2034 | 8.0% | Liquid supplements incl. adjacent functional drinks | A competing analysis |
| 2.85 Billion | 2034 | 2034 | 8.0% | Broadened liquid nutrition definition | A competing analysis |
Our analysis suggests the 207.6 Million figure is the most defensible for buyers because it isolates true supplement formats rather than blending in fortified beverages. On that basis, the market reaches approximately 353 Million by 2030.
Segmentation spans ingredient, type, application, end user and channel. Botanicals lead ingredients, while proteins and amino acids post the steepest growth; immunity is the largest application and OTC the dominant type.
| Parent | Children |
|---|---|
| By Ingredient | Vitamins, Botanicals, Proteins & Amino Acids, Minerals, Others |
| By Type | OTC, Prescribed |
| By Application | Immunity, Energy & Weight Management, Bone & Joint, Cardiac, Anti-aging, Clinical Nutrition |
| By End User | Women, Men, Children, Senior Citizens |
| By Distribution Channel | Pharmacies & Drug Stores, Supermarkets/Hypermarkets, Online, Others |
The GCC countries lead, contributing roughly 44% of regional value on the strength of high disposable income, organized pharmacy chains and government wellness agendas such as Saudi Vision 2030 and UAE's SEHHI program.
| Region | Market Share (%) |
|---|---|
| GCC Countries | 0.44% |
| South Africa | 0.24% |
| Egypt | 0.13% |
| Nigeria | 0.09% |
| Rest of MEA | 0.1% |
| Parent | Children |
|---|---|
| GCC Countries | Saudi Arabia, UAE, Kuwait, Qatar, Oman, Bahrain |
| North Africa | Egypt, Morocco, Algeria, Tunisia |
| Sub-Saharan Africa | South Africa, Nigeria, Kenya, Ghana |
| Rest of MEA | Other markets |
Within GCC, the UAE and Saudi Arabia anchor volume; Egypt is the fastest-growing North African market on the back of universal health coverage investment, and South Africa remains the single largest country market driven by preventive healthcare spending.
Growth is driven by rising chronic disease burden, government wellness policy, fitness culture and expanding pharmacy and e-commerce access; it is restrained by premium pricing, regulatory fragmentation and weak rural distribution.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Chronic disease burden (diabetes) | Driver | High | Sustained metabolic-health supplement demand |
| Government wellness policy | Driver | High | Vision 2030, SEHHI, Egypt health initiatives |
| Fitness and sports nutrition culture | Driver | High | Protein and amino acid liquids demand |
| Phytomedicine and botanical initiatives | Driver | Medium | Local sourcing and product innovation |
| Premium pricing | Restraint | Medium | Limits uptake among price-sensitive consumers |
| Regulatory fragmentation | Restraint | High | Raises compliance cost and slows launches |
| Limited rural distribution | Restraint | Medium | Constrains volume beyond urban centers |
Our analysis suggests the balance favors growth: policy tailwinds and chronic-disease demand are structural, while pricing and regulatory friction are surmountable through local formulation and pharmacy partnerships.
The landscape is a mix of global nutrition majors and regional specialists. Herbalife and Amway lead direct-selling and brand equity; Bayer and Vitabiotics hold pharmacy shelf strength; Glanbia and BASF anchor protein and ingredient supply; Pharco and Nutrilife dominate local formulation.
| Company | Positioning | Key strength |
|---|---|---|
| Herbalife International | Global nutrition | Direct-selling reach, brand trust |
| Amway Corporation | Global wellness | Distributor network |
| Bayer AG | Pharma-nutrition | Pharmacy credibility |
| Vitabiotics Ltd | Supplement specialist | Premium formulations |
| Glanbia Plc | Protein and ingredients | Sports nutrition supply |
| BASF SE | Ingredient supplier | Formulation science |
| Pharco Pharmaceuticals | Regional producer | Local manufacturing, Egypt |
| Nutrilife International | Regional producer | Cost-competitive formulations |
Differentiation rests on local formulation (botanicals, halal certification), pharmacy relationships and price-tier portfolios. Moats are moderate: brand and channel access matter more than proprietary IP.
Buyers should prioritize regulatory compliance, halal certification and local formulation partnerships. Regulatory regimes vary sharply across GCC, Egypt, Nigeria and South Africa, so multi-country launches require country-specific registration planning. Procurement risk concentrates in import-dependent premium SKUs, where currency volatility and tariffs can compress margins quickly. Switching costs are low for commodity vitamins but rise for botanicals tied to local sourcing agreements. Operators should secure pharmacy-chain and e-commerce partnerships early, and build dual-sourcing for protein and botanical inputs to avoid supply disruption.
The balance of evidence favors growth optimism, but with definition discipline: the 207.6 Million base and 10.8% CAGR best reflect true liquid supplement demand, and buyers should anchor plans there rather than on broader liquid-nutrition figures. The strongest counter-argument is that premium pricing and regulatory fragmentation could compress the growth curve below 10% in North Africa and Nigeria; we judge this a timing risk, not a structural one.
Our analysis suggests the highest-value opportunities sit at the intersection of local botanical sourcing and pharmacy-plus-e-commerce distribution. Vendors that formulate with indigenous botanicals under clean-label positioning can defend margin against imported premium SKUs while aligning with government phytomedicine agendas. Regional producers such as Pharco and Nutrilife are best positioned to capture price-sensitive volume.
Actionable Strategy:
What would change our conclusion: a sustained currency shock across Egypt and Nigeria, or a regulatory tightening on botanical claims in GCC, would materially lower the growth trajectory.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.8% from 2020-2034 |
| Segmentation |
|
The market was estimated at 207.6 Million in 2024 and is projected to grow at a 10.8% CAGR through 2030, reaching roughly 353 Million by the end of the forecast period.
Botanicals led with a 31.4% revenue share in 2024. Proteins and amino acids are the fastest-growing segment at a 15.7% CAGR, driven by fitness culture and urbanization.
GCC countries account for roughly 44% of regional value, led by the UAE and Saudi Arabia. South Africa, Egypt and Nigeria are the next most significant country markets.
Pharmacies and drug stores lead sales because consumers trust their authenticity and regulatory oversight. E-commerce is the fastest-growing channel, especially in urban GCC markets.
Leading vendors include Herbalife International, Amway Corporation, Bayer AG, Vitabiotics, Glanbia, BASF, Pharco Pharmaceuticals and Nutrilife International, spanning global and regional players.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split. In-depth interviews were conducted with stakeholders across the value chain — raw material and botanical extract suppliers, specialized liquid supplement producers, contract formulators and blenders, and regional distributors. Decision-maker designations included VP Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads across GCC, North Africa and Sub-Saharan markets.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement Leads | 35% |
| Heads of R&D & Formulation | 30% |
| Technical Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Botanical Extract Suppliers | 40% |
| Specialized Liquid Supplement Producers | 30% |
| Contract Formulators & Blenders | 18% |
| Regional Distributors & Pharmacy Chains | 12% |
We validate against official multilateral databases including UN Comtrade, WTO trade statistics, US ITC and Eurostat; corporate annual filings and investor presentations; patent databases; and recognized technical standards from bodies such as the Codex Alimentarius Commission, ISO and regional food-safety authorities. No competitor market-research publications are cited.
We triangulate simultaneously through a Top-Down allocation from macroeconomic and industry segment data and a Bottom-Up model built on manufacturer capacity, product pricing and end-use consumption patterns. Divergences between the two are reconciled against trade-flow data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |