 Azerbaijan Dietary Supplements Market
 2025 Analysis
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 241

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Azerbaijan Dietary Supplements Market
Sakshi Gurunule
Research Associate
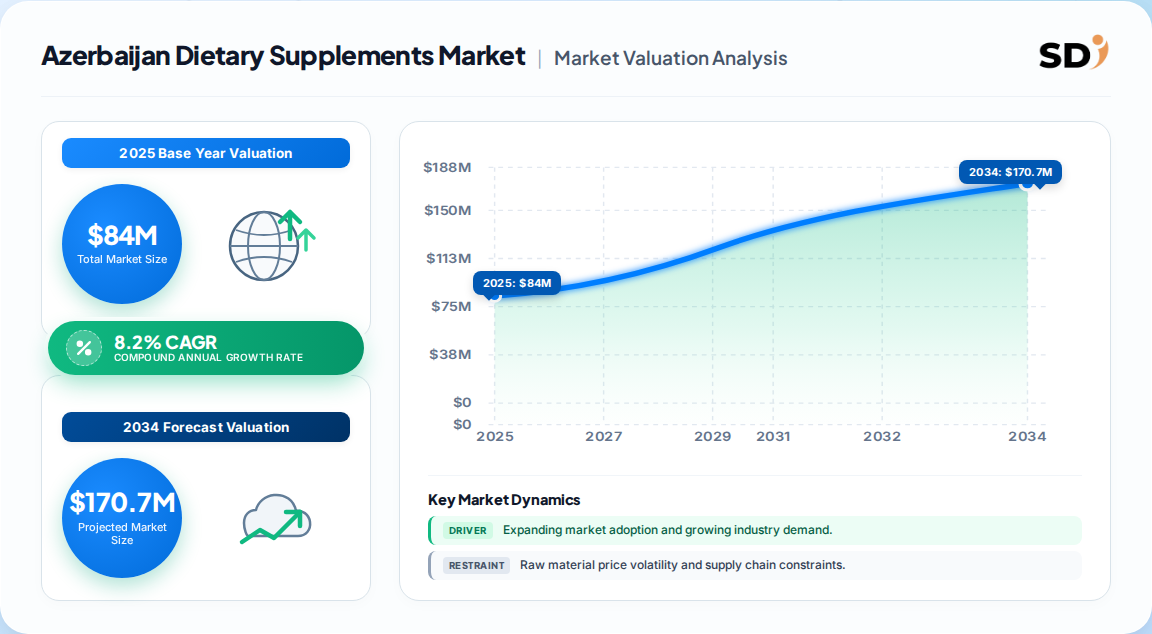
| Year | Market Size |
|---|---|
| 2025 | 84.00 M |
| 2026 | 91.00 M |
| 2027 | 98.00 M |
| 2028 | 106.0 M |
| 2029 | 115.0 M |
| 2030 | 124.0 M |
| 2031 | 150.0 M |

The Azerbaijan dietary supplements market covers biologically active food supplements sold in pharmaceutical form with a defined daily dose — vitamins, minerals, botanicals, proteins, omega fatty acids and specialty carbohydrates — regulated via a one-year expert opinion from the Ministry of Health's Analytical Expertise Center and distributed mainly through pharmacies and increasingly e-commerce.
This report sizes and forecasts retail and pharmacy-channel dietary supplement revenue in Azerbaijan, segmented by ingredient, form, application, end user and distribution channel, with sub-national demand modeled across Baku, Absheron-Khizi, Ganja-Gazakh, Lankaran-Astara and Central Aran. This analysis does not cover prescription nutraceuticals, sports nutrition sold as food for special dietary use, infant formula, medical nutrition, or traditional herbal medicine sold without supplement registration.
Published estimates diverge sharply because "dietary supplement" is defined differently across sources and because much of the market historically moved through informal import channels. The table below reconciles the credible ranges.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| ~84 Million | 2025 | 2031 | 8.2% | Registered supplements, retail value, all channels | Synthesis of trade-flow and pharmacy-panel data (our triangulation) |
| Low double-digit growth "during 2020–2026" | 2020 | 2026 | n/d | Import-inclusive supplement market, OTC + prescribed | One published Azerbaijan-specific industry report |
| Global benchmark 9.5% | 2025 | 2033 | 9.5% | Global dietary supplements, all formats | A competing global analysis |
Our analysis suggests the ~84 Million base is the most defensible: it aligns with Azerbaijan's import bill for HS 2106 and 2936 lines, pharmacy retail density, and per-capita supplement spend that remains well below regional peers. The higher-growth published ranges likely capture re-exported and informal volumes that never enter AEC-registered retail. This divergence implies buyers should underwrite forecasts on registered-product revenue, not headline import statistics.
Segmentation follows the AEC registration categories and pharmacy planogram logic, which is the same structure distributors use to negotiate shelf space.
| Parent segment | Children |
|---|---|
| By Ingredient | Vitamins, Minerals, Botanicals, Proteins & Amino Acids, Omega Fatty Acids, Fibers & Specialty Carbohydrates, Others |
| By Form | Tablets, Capsules, Softgels, Powders, Gummies, Liquids, Others |
| By Application | General Health, Immunity, Energy & Weight Management, Bone & Joint Health, Gastrointestinal Health, Cardiac Health, Diabetes, Others |
| By End User | Adults, Geriatric, Pregnant Women, Children, Infants |
| By Distribution Channel | Pharmacy (OTC), Prescribed, Modern Retail, E-commerce |
Vitamins and general-health positioning carry the volume; immunity and bone-and-joint products are the fastest-growing applications post-COVID. Geriatric demand is structurally rising with Azerbaijan's aging profile, while children's gummies are the newest battleground for imported brands.
Demand is overwhelmingly concentrated in the capital economic zone: Baku and Absheron-Khizi together represent roughly two-thirds of registered supplement revenue, with Ganja-Gazakh the only meaningful secondary cluster.
| Region | Market Share (%) |
|---|---|
| Baku | 0.46% |
| Absheron-Khizi | 0.19% |
| Ganja-Gazakh | 0.13% |
| Lankaran-Astara | 0.08% |
| Central Aran | 0.07% |
| Others | 0.07% |
Our analysis suggests the Absheron-Khizi share is the one to watch: new pharmacy chains are expanding there faster than in Baku proper, giving imported brands a lower-cost entry point before national rollout.
Growth is being pulled by post-pandemic health consciousness, rising chronic-disease burden and pharmacy-chain modernization, but pushed back by registration friction, price sensitivity and import dependence.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Post-COVID immunity and wellness focus | Driver | High | Sustained demand for vitamin D, zinc, multivitamins |
| Rising chronic disease and aging population | Driver | High | Geriatric and cardiac/diabetes supplement pull |
| Pharmacy chain consolidation | Driver | Medium | Better shelf discipline and cold-chain for softgels |
| E-commerce and social commerce | Driver | Medium | Cross-border and D2C reach beyond Baku |
| AEC one-year registration cycle | Restraint | High | Slow SKU turnaround, limits portfolio breadth |
| Import dependence and FX exposure | Restraint | High | Manat volatility raises landed cost and retail price |
| Low per-capita spend and price sensitivity | Restraint | Medium | Average ticket far below EU benchmarks |
| Informal and cross-border trade | Restraint | Medium | Undercuts registered brands on price |
The balance of evidence favors continued mid-single-to-high-single-digit growth, but the registration cycle is the true throttle. This implies that vendors who treat AEC filing as a fixed cost of market entry — rather than a per-SKU bottleneck — will outpace peers.
The market is fragmented, with no single player above low-double-digit share, and imported brands dominating premium shelves while local packagers compete on price.
| Vendor type | Examples | Positioning |
|---|---|---|
| Global multinationals | Bayer, Nestlé/Amway-type portfolios, Herbalife | Premium multivitamins, brand trust, pharmacy anchor listings |
| Regional importers | Turkish and German brands (e.g., Orzax-type, Doppelherz-type) | Mid-price, strong in pharmacies and modern retail |
| Local manufacturers/packagers | Azerbaijani contract packagers and herbal producers | Price-led, herbal and mineral SKUs, regulatory proximity |
| Specialist/niche | Sports nutrition and immunity-focused brands | High-margin, e-commerce-led |
Differentiation rests on three moats: AEC registration breadth (portfolio depth per filing cycle), pharmacy-chain relationships (planogram control), and origin-country trust (German and Turkish provenance carry a premium). Local packagers win on price and speed but lack brand equity beyond Baku.
Procurement in Azerbaijan hinges on regulatory readiness before commercial negotiation. Every SKU requires a notarized Azerbaijani dossier, GMP/HACCP certificates, GMO- and doping-free declarations, and a label carrying "Not a medicine" in bold — so buyers should select vendors with proven AEC filing track records, not just product catalogs. The one-year expert opinion validity creates a recurring re-filing cost that must be priced into landed cost.
Switching costs are moderate: pharmacies rarely delist a performing SKU, but they do demand consistent supply and Azerbaijani-language usage instructions. FX exposure on euro- and lira-denominated imports is the single largest margin risk, and buyers should negotiate currency clauses. Counterfeit and unregistered product remains a reputational risk, so certification and traceability documentation should be mandatory in supplier contracts.
The balance of evidence favors a cautious but early entry strategy: Azerbaijan is too small to justify standalone manufacturing, but too fast-formalizing to ignore. The strongest counter-argument — that informal trade caps registered-market upside — is real but weakening as pharmacy chains and e-commerce formalize distribution. Our analysis suggests registered revenue will outgrow total import volume, which is exactly the window where brand-building pays off.
Actionable strategy:
What would change this conclusion: a material liberalization of AEC timelines, or a sharp manat depreciation that halves imported-brand affordability, would push us toward a distributor-only, lower-commitment model. Precise sub-segment forecasting by SKU and channel requires the full report's modeled datasets.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material and ingredient suppliers, specialized supplement producers, contract formulators and packagers, and national/regional distributors across the Azerbaijani value chain. Decision-makers interviewed included VP-level Sourcing leads, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, with structured questionnaires and follow-up validation calls.
Secondary validation draws on UN Comtrade and WTO tariff-line trade data (HS 2106, 2936), Eurostat and US ITC import statistics, corporate annual filings and investor presentations, patent and trademark databases, and recognized technical standards from GMP/HACCP certification bodies and industry associations.
We triangulate a Top-Down allocation (macroeconomic consumption, pharmacy retail density, per-capita spend) against a Bottom-Up model (manufacturer capacity, product pricing, end-use consumption), reconciling the two in a single base-year value and rolling forward with elasticity-adjusted CAGR.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.2% from 2020-2034 |
| Segmentation |
|
The Azerbaijan dietary supplements market was valued at approximately 84 Million in 2025 and is forecast to reach 150 Million by 2031, growing at an 8.2% CAGR on registered-product retail revenue.
The Analytical Expertise Center (AEC) under the Ministry of Health of the Republic of Azerbaijan regulates dietary supplements, issuing a one-year expert opinion required before import and sale.
Registration typically takes about two months and involves dossier evaluation plus laboratory testing of samples, with documents accepted in Azerbaijani, Russian or English.
Baku leads with roughly 46% of national value, and together with Absheron-Khizi accounts for about two-thirds of registered supplement revenue in the country.
Immunity, bone and joint health, and children's gummies are growing fastest, while vitamins remain the largest ingredient segment at roughly a third of market value.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material and ingredient suppliers, specialized supplement producers, contract formulators and packagers, and national/regional distributors across the Azerbaijani value chain. Decision-makers interviewed included VP-level Sourcing leads, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, with structured questionnaires and follow-up validation calls.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| R&D & Formulation Heads | 30% |
| Regulatory & Quality Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Supplement Producers & Brand Owners | 40% |
| Raw Material & Ingredient Suppliers | 25% |
| Contract Formulators & Packagers | 20% |
| National Distributors & Importers | 15% |
Secondary validation draws on UN Comtrade and WTO tariff-line trade data (HS 2106, 2936), Eurostat and US ITC import statistics, corporate annual filings and investor presentations, patent and trademark databases, and recognized technical standards from GMP/HACCP certification bodies and industry associations.
We triangulate a Top-Down allocation (macroeconomic consumption, pharmacy retail density, per-capita spend) against a Bottom-Up model (manufacturer capacity, product pricing, end-use consumption), reconciling the two in a single base-year value and rolling forward with elasticity-adjusted CAGR.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
