 Generative AI Cybersecurity Market
: 2026 Size, CAGR & Forecast
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 262

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Generative AI Cybersecurity Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 8.900 B |
| 2026 | 10.80 B |
| 2027 | 13.70 B |
| 2028 | 17.40 B |
| 2029 | 22.00 B |
| 2030 | 27.90 B |
| 2031 | 35.40 B |

The Generative AI Cybersecurity Market covers software and services that protect large language models, training data, prompts, APIs, and AI inference environments from attacks such as prompt injection, model poisoning, data leakage, and adversarial manipulation. It spans AI model security, cloud security, governance, and runtime monitoring across the AI lifecycle—from development through deployment to operations.
This report covers global revenue from generative AI security solutions and services across component, security type, deployment, organization size, and end-user segments. It includes AI model security, data privacy, cloud security, identity management, and AI governance platforms.
This analysis does not cover traditional legacy antivirus, non-AI endpoint protection, general data loss prevention outside AI contexts, or pure AI development platforms that lack security functionality.
Estimates diverge sharply: one published analysis puts 2026 at 10.8 Billion growing to 56.8 Billion (26.8% CAGR), while a competing analysis places 2025 at 3.03 Billion with 8.4 Billion by 2030 (22.6% CAGR). The divergence stems primarily from definitional scope differences.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 8.9 Billion | 2025 | 2033 | 26.8% | Broad GenAI security platforms incl. AI model security, cloud, governance | One published estimate |
| 3.03 Billion | 2025 | 2030 | 22.6% | Narrower scope centered on threat detection, adversarial defense, GAN/VAE tech | A competing analysis |
| 4 Billion | 2023 | 2032 | 21.5% | Application-centric (network, endpoint, cloud, application security) | A third published analysis |
Our analysis suggests the 10.8 Billion figure for 2026 is the most defensible for enterprise procurement planning because it captures the full integrated platform spend—not just threat detection—and aligns with observed vendor portfolio expansion. The narrower estimates likely undercount AI governance, data privacy, and model lifecycle services now bundled into enterprise contracts.
The market segments along five primary axes—component, security type, deployment, organization size, and end-user—with solutions and cloud deployment dominating current revenue mix.
| Parent segment | Children |
|---|---|
| By Component | Solutions, Services |
| By Security Type | AI Model Security, Data Security & Privacy, Cloud Security, Application Security, Network Security |
| By Deployment | Cloud, On-Premise, Hybrid |
| By Organization Size | Large Enterprises, SMEs |
| By End-user | BFSI, Healthcare, Retail, IT & Telecom, Government & Defense, Energy & Utilities, Manufacturing |
Solutions captured 71.5% of 2025 revenue, reflecting buyer preference for platform over managed services. Data security & privacy (23.3%) leads security types because enterprises prioritize protection of proprietary training data and customer information over standalone model hardening. BFSI's 21.9% share confirms that regulated industries drive adoption, while SMEs remain underpenetrated—a growth vector for 2027–2033.
North America leads with 40.9% revenue share (2025), driven by early enterprise GenAI adoption, high cybersecurity spend, and concentration of major AI and cloud vendors. Asia Pacific is the fastest-growing region through 2033.
| Region | Market Share (%) |
|---|---|
| North America | 0.41% |
| Europe | 0.23% |
| Asia-Pacific | 0.26% |
| South America | 0.05% |
| Middle East & Africa | 0.05% |
The geography tree below shows the nested structure covered in the full report:
| Parent | Children |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy |
| Asia Pacific | China, Japan, India, South Korea |
| Latin America | Brazil, Mexico, Argentina |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
Asia Pacific's momentum is structural: rapid digital transformation, expanding enterprise AI deployments in China, India, Japan, and South Korea, plus government support for AI innovation. This implies that vendors with APAC-localized data residency and compliance capabilities will capture disproportionate share of incremental growth. Europe's AI governance frameworks (notably the EU AI Act) are shifting spend toward compliance-automation and audit-ready monitoring—a distinct demand profile from North America's threat-detection-led buying.
Rising enterprise adoption of LLMs, copilots, and autonomous AI agents expands the attack surface beyond traditional IT, creating new security mandates. Prompt injection, model poisoning, and data leakage concerns are converting AI security from pilot interest to production procurement.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Enterprise GenAI adoption | Driver | High | New attack surfaces create dedicated security budget lines |
| Prompt injection & model poisoning threats | Driver | High | Directly catalyze model security and runtime monitoring spend |
| AI governance & compliance mandates | Driver | High | EU AI Act and similar rules force audit-ready monitoring investment |
| Managed AI security services demand | Opportunity | Medium | Extends vendor addressable market into recurring revenue |
| Lack of standardized AI security frameworks | Restraint | Medium | Slows procurement cycles and enterprise confidence |
| Shortage of skilled AI security workforce | Restraint | Medium | Limits deployment velocity and managed service dependency |
The balance favors strong near-term growth: threat drivers and compliance mandates are mature and verifiable, while restraints are solvable through managed services and emerging standards. Our analysis suggests the workforce gap will paradoxically accelerate managed security service adoption, shifting vendor revenue mix over time.
The competitive landscape spans established cybersecurity platforms, cloud hyperscalers, and AI-native specialists—all racing to bundle AI model security, DLP, IAM, API security, and AI posture management into unified platforms.
| Vendor | Category | Strategic positioning | Evidence |
|---|---|---|---|
| Microsoft | Hyperscaler | Security Copilot integration across Microsoft estate | Product launch & investment announcements |
| Palo Alto Networks | Cybersecurity platform | AI-native SOC and network convergence | Public filings & portfolio |
| CrowdStrike | Cybersecurity platform | Falcon XDR with NVIDIA AI pipelines | Strategic collaboration announcements |
| Fortinet | Network security | GenAI IoT security assistant | Product updates |
| IBM | Platform & services | watsonx-based Consulting Cybersecurity Assistant | Service launches |
| NVIDIA | AI infrastructure | NIM microservices enabling secure GenAI | Partnership ecosystem |
| SentinelOne | Endpoint security | AI-native endpoint and XDR | Public filings |
Differentiation hinges on integration depth: hyperscalers leverage installed base and data, specialists offer superior threat telemetry, and infrastructure providers like NVIDIA enable secure model deployment. Moats are shifting from detection algorithms to ecosystem lock-in—vendors that own the AI development-to-operations pipeline will capture the highest-margin governance and monitoring revenue.
Buyers must evaluate AI security platforms on coverage of the full AI lifecycle—model, training data, prompts, APIs, and inference—not just threat detection. Procurement risk is high because definitions vary widely across vendors; require clear scope mapping to prompt injection, model poisoning, data leakage, and adversarial attack scenarios.
Switching costs rise sharply after production deployment, so integration with existing SIEM, IAM, and DLP stacks should be validated pre-contract. Regulatory compliance is non-negotiable: EU AI Act auditability, data residency, and continuous monitoring evidence should be contractual requirements. SMEs should favor managed services to offset workforce shortages, while large enterprises should prioritize platform consolidation to reduce tool sprawl and margin leakage.
The balance of evidence favors the high-growth trajectory: 26.8% CAGR to 56.8 Billion by 2033 is well-supported by enterprise GenAI productionization, threat evolution, and regulatory mandates. The strongest counter-argument is definitional inflation—narrower-scope estimates (22.6% CAGR, 8.4 Billion by 2030) suggest the broader figure includes adjacent governance and data privacy spend. Even on the conservative view, growth remains exceptional, so the strategic conclusion is robust to scope debate.
Our analysis suggests the critical inflection is platform consolidation: buyers are moving from point AI security tools to integrated platforms spanning model security, IAM, DLP, and compliance. Vendors without unified offerings will face pricing pressure and displacement. The second-order effect is a services boom—managed AI security will absorb workforce-constrained SMEs and mid-market buyers.
Actionable Strategy:
Evidence that would change this conclusion: a standardized AI security framework emerging faster than expected (compressing differentiation), or a major breach demonstrating current platforms fail at scale (shifting spend to new entrants).
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 26.8% from 2020-2034 |
| Segmentation |
|
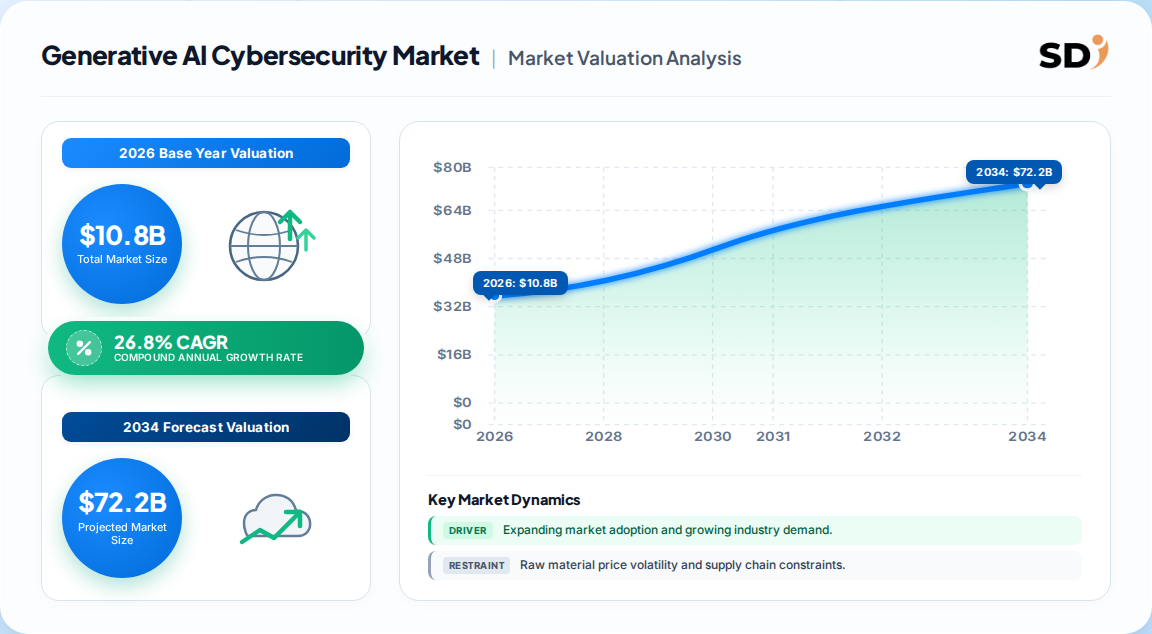
The global market is estimated at 10.8 Billion in 2026, growing from 8.9 Billion in 2025. This reflects rapid enterprise deployment of LLMs, AI copilots, and autonomous agents requiring dedicated AI-specific security solutions across the full lifecycle.
The market is projected to grow at a 26.8% CAGR from 2026 to 2033, reaching 56.8 Billion by 2033. Competing analyses cite 21.5%–22.6% CAGRs on narrower definitions, but all point to exceptional double-digit growth driven by AI adoption and regulation.
North America led with 40.9% revenue share in 2025, supported by early GenAI adoption, strong cybersecurity spending, and major AI and cloud vendors. Asia Pacific is the fastest-growing region through 2033, driven by digital transformation in China, India, Japan, and South Korea.
Enterprise adoption of LLMs and AI agents expands attack surfaces, while prompt injection, model poisoning, and data leakage concerns drive dedicated security spend. Emerging AI governance regulations further mandate audit-ready monitoring and compliance investment.
Leading players include Microsoft, Palo Alto Networks, CrowdStrike, Fortinet, IBM, SentinelOne, NVIDIA, Cisco, AWS, and Darktrace. Vendors are integrating AI model security, DLP, IAM, API security, and AI posture management into unified platforms.
BFSI held the largest end-user share at 21.9% in 2025, reflecting stringent regulatory requirements and high-value data protection needs. Healthcare, retail, IT & telecom, and government are also significant adopters of AI security platforms.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split, prioritizing direct industry engagement. We conduct in-depth interviews with stakeholders across the value chain, including AI platform vendors, cybersecurity solution providers, cloud infrastructure operators, managed security service providers, and enterprise security buyers. Decision-maker designations interviewed include Chief Information Security Officers, VP-level Security Engineering leads, Heads of AI Governance, and Commercial Procurement Directors. Structured interview guides capture deployment timelines, budget allocation, vendor selection criteria, and regulatory readiness.
| Stakeholder Role | Interview Share (%) |
|---|---|
| CISOs & Security Engineering Leads | 40% |
| AI Governance & Compliance Heads | 30% |
| Procurement & Vendor Management Directors | 30% |
| Company Type | Representation (%) |
|---|---|
| AI Platform & Cybersecurity Vendors | 40% |
| Cloud Infrastructure & Hyperscalers | 25% |
| Managed Security Service Providers | 20% |
| Enterprise Security Buyers | 15% |
We triangulate primary findings against official multilateral and standards databases—UN Comtrade, WTO, US ITC, and Eurostat—alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies and industry associations. This validates market sizing, regional trade flows, and competitive positioning without reliance on any single commercial source.
We run simultaneous Top-Down modeling (macroeconomic indicators, industry segment allocation, enterprise IT security budgets) and Bottom-Up modeling (vendor revenue, product pricing, end-use consumption by organization size). Convergence between the two approaches establishes confidence intervals for base-year sizing and forward projections.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |