Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Data Center Colocation Market Size, Share & Forecast 2026
Data Center Colocation Market
Data Center Colocation Market Size, Share & Forecast 2026
Data Center Colocation Market by Colocation Type (Retail Multi-Tenant, Wholesale Multi-Tenant, Hybrid), by Tier Level (Tier 1 & 2, Tier 3, Tier 4), by Facility Size (Small, Medium, Large, Hyperscale), by Enterprise Size (Large Enterprises, SMEs), by End Use (IT & Telecom, Healthcare, BFSI, Government & Defense, Media & Entertainment, Retail, Others), by Power Capacity (Below 5 MW, 5-20 MW, Above 20 MW), by North America (United States, Canada, Mexico), by Europe (Germany, UK, France, Netherlands, Ireland), by Asia-Pacific (China, Japan, India, Singapore, Australia, South Korea), by Latin America (Brazil, Mexico, Chile, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Israel) Forecast 2026-2034
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 230
Srinwanti Kar
Senior Research Analyst
Data Center Colocation Market Size, Share & Forecast 2026
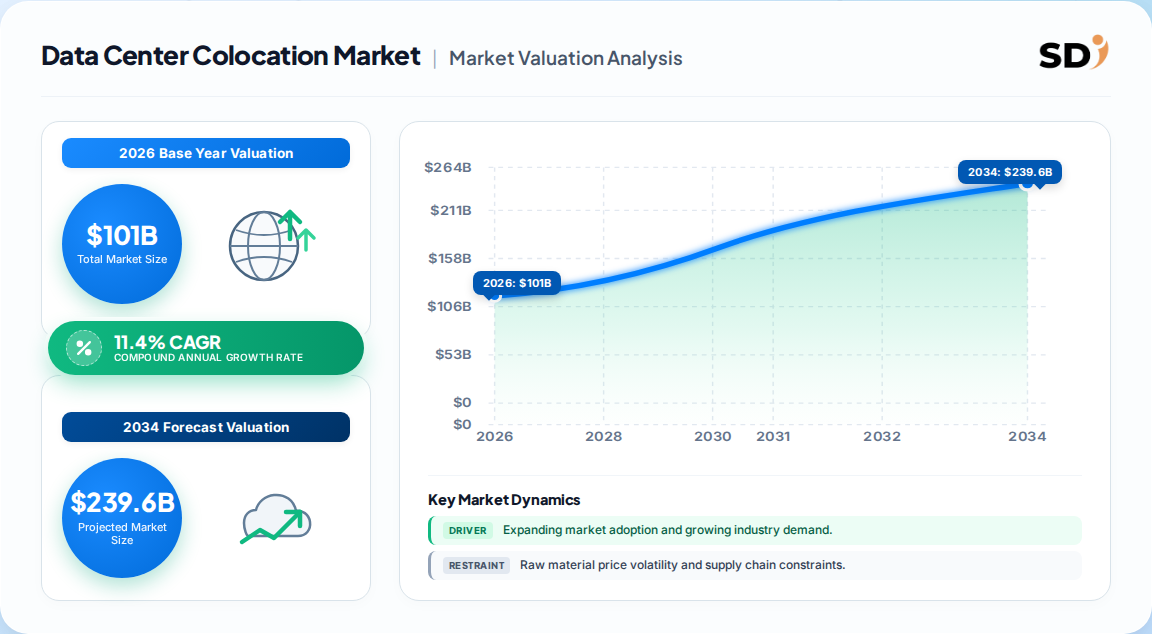
The global data center colocation market was valued at 91.1 Billion in 2025 and is estimated at 101.0 Billion in 2026, with a long-run compound growth rate of 11.4% through 2035.
Forecast horizon output reaches 267.9 Billion by 2035 on the higher-growth trajectory; a more conservative independent series points to 184.4 Billion by 2033, a spread our analysis attributes to differing AI-capacity assumptions.
Retail colocation remains the volume anchor at roughly 63–69% of revenue, but wholesale and hyperscale suites are the fastest-compounding product lines.
North America leads with about 39–41% of global revenue, while Asia-Pacific and the Middle East & Africa are the fastest-growing regions on grid and sovereignty tailwinds.
Tier 3 facilities hold the largest installed base near 46–59% depending on definition, yet Tier 4 and liquid-cool-ready halls command premium per-kilowatt pricing.
Equinix leads with over 7.4% share; the top five operators collectively hold roughly 19.5%, confirming a fragmented, medium-concentration market.
Why this matters for decision-makers: Power, not real estate, is now the binding constraint — buyers must contract capacity 24–48 months ahead or accept secondary-market pricing and latency trade-offs.
Data Center Colocation Market Size (In Billion)
200.0B
150.0B
100.0B
50.0B
0
88.20 B
2025
101.0 B
2026
112.5 B
2027
125.3 B
2028
139.6 B
2029
155.5 B
2030
173.2 B
2031
Data Center Colocation Market Size (In Billion)
Year
Market Size
2025
88.20 B
2026
101.0 B
2027
112.5 B
2028
125.3 B
2029
139.6 B
2030
155.5 B
2031
173.2 B
What is the Data Center Colocation Market?
The data center colocation market is the third-party provision of secured physical space, redundant power, cooling, and network connectivity for customer-owned IT infrastructure. Tenants retain control of servers while outsourcing capital-intensive facilities, enabling rapid scaling, carrier diversity, and compliance-aligned deployment.
Scope: what this report covers and excludes
This analysis covers retail and wholesale multi-tenant colocation, Tier 1–4 facility classifications, small through hyperscale facility sizes, and end-use demand across IT and telecom, healthcare, BFSI, government, and media. Coverage spans North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. This analysis does not cover self-built enterprise data centers, single-tenant hyperscale build-to-suit ownership, cloud infrastructure-as-a-service revenue, or the server, networking, and cooling equipment supply markets.
How big is the market for Data Center Colocation Market?
The market sits between 91.1 Billion (2025) and 88.2 Billion (2025) on two independent base-year estimates, converging on a 2026 midpoint near 100 Billion. The divergence is definitional, not directional.
Our analysis suggests the 11.4% trajectory is the most defensible central case, because it explicitly prices in AI-driven rack density (40–80 kW per rack) and the multi-year grid interconnection lag. The 9.3% series is credible but assumes slower premium-capacity conversion. The spread itself is the signal: forecast uncertainty is concentrated in power delivery timelines, not demand.
How is the market segmented?
Segmentation splits along commercial model, facility tier, facility scale, and end-use vertical. Retail multi-tenant space dominates revenue today, while wholesale and hyperscale configurations capture the marginal growth dollar.
IT & telecom, Healthcare, BFSI, Government & defense, Media & entertainment, Retail, Others
By Power Capacity
Below 5 MW, 5–20 MW, Above 20 MW
Retail's 63.5–69.2% share reflects interconnection density and stickiness. Wholesale's 12.3% CAGR reflects hyperscaler preference for turnkey power blocks. The strategic implication: operators cannot serve both models with one campus design, so portfolio bifurcation is now a capital-allocation decision, not a marketing one.
Which region leads in Data Center Colocation Market?
North America leads with roughly 39–41% of global colocation revenue, anchored by Northern Virginia, Dallas, Silicon Valley, and Chicago. Asia-Pacific is the fastest-compounding region at approximately 12.7% CAGR.
Data Center Colocation Market Regional Market Share
Loading chart...
Data Center Colocation Market Regional Market Share
Region
Market Share (%)
North America
0.39%
Europe
0.24%
Asia-Pacific
0.28%
Latin America
0.04%
Middle East & Africa
0.05%
Global
North America — United States, Canada, Mexico (largest, ~39%)
Europe — Germany, UK, France, Netherlands, Ireland (FLAP-D constrained)
Asia-Pacific — China, Japan, India, Singapore, Australia, South Korea (fastest, ~28%)
Latin America — Brazil, Mexico, Chile, Argentina
Middle East & Africa — Saudi Arabia, UAE, South Africa, Israel (fastest-growing emerging bloc)
The regional picture is bifurcating. Utility-imposed caps in Northern Virginia, Singapore, and Dublin have pushed approval timelines to three or four years, artificially tightening premium supply and sustaining double-digit pricing in mature metros. Our analysis suggests this constraint redistributes — rather than destroys — demand, redirecting investment to secondary US markets, India, and Gulf sovereign-backed campuses where power contracts are pre-secured.
What is driving growth — and what is holding it back?
Power-secured, liquid-cool-ready capacity is the demand engine; grid availability and per-megawatt capital cost are the brakes. On balance, demand is outrunning deliverable supply through 2028.
Factor
Direction
Evidence strength
Mechanism
AI and cloud workload acceleration
Driver
Strong
Global data center electricity to ~945 TWh by 2030; high-density racks require purpose-built halls
Enterprise outsourcing and hyperscale expansion
Driver
Strong
North America primary-market net absorption hit 1,809.5 MW in 2024
Data-sovereignty regulation
Driver
Moderate-strong
EU Data Act, India DPDP Act, Saudi PDPL force in-country hosting
Edge and IoT latency demand
Driver
Moderate
1–5 MW micro-nodes proliferate; 40% of new data is latency-sensitive
Escalating power and capital costs
Restraint
Strong
Build costs near 12 Million per MW in 2024, with tariff pressure
Grid availability and moratoriums
Restraint
Strong
Data centers ~1.5% of global electricity in 2024; interconnection queues add years
Operational and compliance barriers
Restraint
Moderate
Certified staffing, uptime guarantees, and audit obligations raise entry cost
The balance is unambiguous: restraints are supply-side and time-bound, while drivers are demand-side and structural. That asymmetry explains why pricing power sits with operators who already hold energized land — and why late entrants face both higher build costs and slower revenue conversion.
Who are the leading vendors?
Equinix leads with over 7.4% global share, followed by Digital Realty and NTT Global Data Centers. The top five operators hold roughly 19.5% combined, indicating a fragmented market with meaningful regional specialists.
Company
Position
Differentiation
Equinix
Leader, 7.4%+
Global interconnection fabric; ~22% of deployments demanded liquid cooling vs 9% prior year
Digital Realty
Strong #2
PlatformDIGITAL bookings up 38%; wholesale plus connectivity bundles
NTT Global Data Centers
Strong global
APAC footprint depth; 85 micro-nodes deployed in Japan
CyrusOne
Regional strong
US wholesale and hyperscale focus
Iron Mountain Data Centers
Niche strong
Compliance, government, and records-adjacent workloads
ST Telemedia
APAC specialist
India and Southeast Asia sovereign demand
Moat analysis: interconnection density creates switching costs that pure power capacity cannot replicate. A tenant with 40 cross-connects faces meaningful migration friction, which sustains renewal rates and pricing. Conversely, wholesale campuses compete on power deliverability and price — a thinner moat that invites hyperscaler self-build substitution.
What do buyers and operators need to know?
Procurement has shifted from price negotiation to capacity reservation. Buyers should treat power delivery date, not square footage, as the contract's critical variable, and should contractualize utility-interconnection milestones with remedies for delay.
Selection criteria that now drive outcomes:
Certified liquid-cooling readiness and thermal headroom per row, not just per hall.
Pre-secured medium-voltage feeds with documented utility commitments.
Tier III or IV certification aligned to Uptime Institute standards.
Cross-connect density and cloud on-ramp proximity — the real latency determinant.
Data-residency compliance roadmap mapped to EU, India, and Gulf statutes.
Switching costs are asymmetric: retail tenants face high interconnection migration friction, while wholesale tenants retain more optionality but face longer lead times for replacement capacity. Operators, meanwhile, carry the inverse risk — a signed lease against undelivered power converts to penalty exposure, so underwriting discipline on utility timelines is now a margin determinant.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the higher-growth trajectory, but with a critical qualification: growth accrues disproportionately to operators holding energized, liquid-ready capacity, not to the market as a whole. The installed general-purpose estate faces obsolescence risk as AI clusters demand thermal architectures it cannot economically retrofit.
Strongest counter-argument: if AI capital expenditure normalizes after 2027, the 267.9 Billion endpoint overshoots and 2029–2031 capacity could oversupply secondary markets. This is credible — build pipelines are large, and 6,350 MW was under construction in North America alone at end-2024. Our rebuttal is that enterprise outsourcing and sovereignty mandates provide a non-AI demand floor that did not exist in prior cycles.
Actionable strategy:
Investors: underwrite power contracts and interconnection density, not megawatt pipeline announcements; premium valuations belong to pre-energized campuses.
Operators: retrofit liquid cooling in existing high-demand metros before 2027 to capture premium pricing before competing supply lands.
Buyers: lock multi-year take-or-pay capacity now in constrained metros; the cost of waiting exceeds the cost of over-reservation.
Evidence that would change this conclusion: sustained utility interconnection reform compressing approval timelines below 18 months, or a measurable decline in AI training capital expenditure across two consecutive quarters.
Data Center Colocation Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Data Center Colocation Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 11.4% from 2020-2034
Segmentation
By Colocation Type
Retail Multi-Tenant
Wholesale Multi-Tenant
Hybrid
By Tier Level
Tier 1 & 2
Tier 3
Tier 4
By Facility Size
Small
Medium
Large
Hyperscale
By Enterprise Size
Large Enterprises
SMEs
By End Use
IT & Telecom
Healthcare
BFSI
Government & Defense
Media & Entertainment
Retail
Others
By Power Capacity
Below 5 MW
5-20 MW
Above 20 MW
By Geography
North America
United States
Canada
Mexico
Europe
Germany
UK
France
Netherlands
Ireland
Asia-Pacific
China
Japan
India
Singapore
Australia
South Korea
Latin America
Brazil
Mexico
Chile
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Israel
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Colocation Type
5.1.1. Retail Multi-Tenant
5.1.2. Wholesale Multi-Tenant
5.1.3. Hybrid
5.2. Market Analysis, Insights and Forecast - by Tier Level
5.2.1. Tier 1 & 2
5.2.2. Tier 3
5.2.3. Tier 4
5.3. Market Analysis, Insights and Forecast - by Facility Size
5.3.1. Small
5.3.2. Medium
5.3.3. Large
5.3.4. Hyperscale
5.4. Market Analysis, Insights and Forecast - by Enterprise Size
5.4.1. Large Enterprises
5.4.2. SMEs
5.5. Market Analysis, Insights and Forecast - by End Use
5.5.1. IT & Telecom
5.5.2. Healthcare
5.5.3. BFSI
5.5.4. Government & Defense
5.5.5. Media & Entertainment
5.5.6. Retail
5.5.7. Others
5.6. Market Analysis, Insights and Forecast - by Power Capacity
5.6.1. Below 5 MW
5.6.2. 5-20 MW
5.6.3. Above 20 MW
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia-Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Colocation Type
6.1.1. Retail Multi-Tenant
6.1.2. Wholesale Multi-Tenant
6.1.3. Hybrid
6.2. Market Analysis, Insights and Forecast - by Tier Level
6.2.1. Tier 1 & 2
6.2.2. Tier 3
6.2.3. Tier 4
6.3. Market Analysis, Insights and Forecast - by Facility Size
6.3.1. Small
6.3.2. Medium
6.3.3. Large
6.3.4. Hyperscale
6.4. Market Analysis, Insights and Forecast - by Enterprise Size
6.4.1. Large Enterprises
6.4.2. SMEs
6.5. Market Analysis, Insights and Forecast - by End Use
6.5.1. IT & Telecom
6.5.2. Healthcare
6.5.3. BFSI
6.5.4. Government & Defense
6.5.5. Media & Entertainment
6.5.6. Retail
6.5.7. Others
6.6. Market Analysis, Insights and Forecast - by Power Capacity
6.6.1. Below 5 MW
6.6.2. 5-20 MW
6.6.3. Above 20 MW
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Colocation Type
7.1.1. Retail Multi-Tenant
7.1.2. Wholesale Multi-Tenant
7.1.3. Hybrid
7.2. Market Analysis, Insights and Forecast - by Tier Level
7.2.1. Tier 1 & 2
7.2.2. Tier 3
7.2.3. Tier 4
7.3. Market Analysis, Insights and Forecast - by Facility Size
7.3.1. Small
7.3.2. Medium
7.3.3. Large
7.3.4. Hyperscale
7.4. Market Analysis, Insights and Forecast - by Enterprise Size
7.4.1. Large Enterprises
7.4.2. SMEs
7.5. Market Analysis, Insights and Forecast - by End Use
7.5.1. IT & Telecom
7.5.2. Healthcare
7.5.3. BFSI
7.5.4. Government & Defense
7.5.5. Media & Entertainment
7.5.6. Retail
7.5.7. Others
7.6. Market Analysis, Insights and Forecast - by Power Capacity
7.6.1. Below 5 MW
7.6.2. 5-20 MW
7.6.3. Above 20 MW
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Colocation Type
8.1.1. Retail Multi-Tenant
8.1.2. Wholesale Multi-Tenant
8.1.3. Hybrid
8.2. Market Analysis, Insights and Forecast - by Tier Level
8.2.1. Tier 1 & 2
8.2.2. Tier 3
8.2.3. Tier 4
8.3. Market Analysis, Insights and Forecast - by Facility Size
8.3.1. Small
8.3.2. Medium
8.3.3. Large
8.3.4. Hyperscale
8.4. Market Analysis, Insights and Forecast - by Enterprise Size
8.4.1. Large Enterprises
8.4.2. SMEs
8.5. Market Analysis, Insights and Forecast - by End Use
8.5.1. IT & Telecom
8.5.2. Healthcare
8.5.3. BFSI
8.5.4. Government & Defense
8.5.5. Media & Entertainment
8.5.6. Retail
8.5.7. Others
8.6. Market Analysis, Insights and Forecast - by Power Capacity
8.6.1. Below 5 MW
8.6.2. 5-20 MW
8.6.3. Above 20 MW
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Colocation Type
9.1.1. Retail Multi-Tenant
9.1.2. Wholesale Multi-Tenant
9.1.3. Hybrid
9.2. Market Analysis, Insights and Forecast - by Tier Level
9.2.1. Tier 1 & 2
9.2.2. Tier 3
9.2.3. Tier 4
9.3. Market Analysis, Insights and Forecast - by Facility Size
9.3.1. Small
9.3.2. Medium
9.3.3. Large
9.3.4. Hyperscale
9.4. Market Analysis, Insights and Forecast - by Enterprise Size
9.4.1. Large Enterprises
9.4.2. SMEs
9.5. Market Analysis, Insights and Forecast - by End Use
9.5.1. IT & Telecom
9.5.2. Healthcare
9.5.3. BFSI
9.5.4. Government & Defense
9.5.5. Media & Entertainment
9.5.6. Retail
9.5.7. Others
9.6. Market Analysis, Insights and Forecast - by Power Capacity
9.6.1. Below 5 MW
9.6.2. 5-20 MW
9.6.3. Above 20 MW
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Colocation Type
10.1.1. Retail Multi-Tenant
10.1.2. Wholesale Multi-Tenant
10.1.3. Hybrid
10.2. Market Analysis, Insights and Forecast - by Tier Level
10.2.1. Tier 1 & 2
10.2.2. Tier 3
10.2.3. Tier 4
10.3. Market Analysis, Insights and Forecast - by Facility Size
10.3.1. Small
10.3.2. Medium
10.3.3. Large
10.3.4. Hyperscale
10.4. Market Analysis, Insights and Forecast - by Enterprise Size
10.4.1. Large Enterprises
10.4.2. SMEs
10.5. Market Analysis, Insights and Forecast - by End Use
10.5.1. IT & Telecom
10.5.2. Healthcare
10.5.3. BFSI
10.5.4. Government & Defense
10.5.5. Media & Entertainment
10.5.6. Retail
10.5.7. Others
10.6. Market Analysis, Insights and Forecast - by Power Capacity
10.6.1. Below 5 MW
10.6.2. 5-20 MW
10.6.3. Above 20 MW
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Data Center Colocation Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Data Center Colocation Market Revenue (Billion), by Colocation Type 2026 & 2034
Figure 3: North America Data Center Colocation Market Revenue Share (%), by Colocation Type 2026 & 2034
Figure 4: North America Data Center Colocation Market Revenue (Billion), by Tier Level 2026 & 2034
Figure 5: North America Data Center Colocation Market Revenue Share (%), by Tier Level 2026 & 2034
Figure 6: North America Data Center Colocation Market Revenue (Billion), by Facility Size 2026 & 2034
Figure 7: North America Data Center Colocation Market Revenue Share (%), by Facility Size 2026 & 2034
Figure 8: North America Data Center Colocation Market Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 9: North America Data Center Colocation Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 10: North America Data Center Colocation Market Revenue (Billion), by End Use 2026 & 2034
Figure 11: North America Data Center Colocation Market Revenue Share (%), by End Use 2026 & 2034
Figure 12: North America Data Center Colocation Market Revenue (Billion), by Power Capacity 2026 & 2034
Figure 13: North America Data Center Colocation Market Revenue Share (%), by Power Capacity 2026 & 2034
Figure 14: North America Data Center Colocation Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Data Center Colocation Market Revenue Share (%), by Country 2026 & 2034
Europe Data Center Colocation Market Revenue (Billion), by Colocation Type 2026 & 2034
List of Tables
Table 1: Data Center Colocation Market Revenue Billion Forecast, by Colocation Type 2020 & 2034
Table 2: Data Center Colocation Market Revenue Billion Forecast, by Tier Level 2020 & 2034
Table 3: Data Center Colocation Market Revenue Billion Forecast, by Facility Size 2020 & 2034
Table 4: Data Center Colocation Market Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 5: Data Center Colocation Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 6: Data Center Colocation Market Revenue Billion Forecast, by Power Capacity 2020 & 2034
Table 7: Data Center Colocation Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Data Center Colocation Market Revenue Billion Forecast, by Colocation Type 2020 & 2034
Table 9: North America Data Center Colocation Market Revenue Billion Forecast, by Tier Level 2020 & 2034
Table 10: North America Data Center Colocation Market Revenue Billion Forecast, by Facility Size 2020 & 2034
Table 11: North America Data Center Colocation Market Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 12: North America Data Center Colocation Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 13: North America Data Center Colocation Market Revenue Billion Forecast, by Power Capacity 2020 & 2034
Table 14: North America Data Center Colocation Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: United States Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Canada Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. What is the data center colocation market size in 2026?
The market is estimated between 99.2 Billion and 101.0 Billion in 2026, depending on definitional scope. The midpoint near 100 Billion reflects consistent base-year convergence across independent benchmarks, with retail multi-tenant capacity contributing the majority of revenue.
2. What is the growth rate of the data center colocation market?
Consensus compound growth ranges from 9.3% to 11.9%, with 11.4% through 2035 as the most defensible central case. The higher figure explicitly prices in AI rack density and multi-year grid interconnection delays constraining new supply.
3. Which region dominates data center colocation?
North America leads with roughly 39–41% of global revenue, anchored by Northern Virginia, Dallas, and Silicon Valley. Asia-Pacific is the fastest-growing region at about 12.7% CAGR, driven by India, Japan, and Southeast Asian sovereign demand.
4. Who are the leading colocation providers?
Equinix leads with over 7.4% global share, followed by Digital Realty, NTT Global Data Centers, CyrusOne, and Iron Mountain. The top five hold roughly 19.5% combined, indicating a fragmented market with strong regional specialists.
5. Why is power availability the key constraint?
Data centers consumed about 1.5% of global electricity in 2024, triggering moratoriums and multi-year interconnection queues. Utility caps in Northern Virginia, Singapore, and Dublin stretch approvals to three or four years, tightening premium supply and sustaining pricing.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted with stakeholders across the colocation value chain, including wholesale campus developers, retail colocation operators, hyperscale infrastructure procurement teams, connectivity and interconnection providers, and enterprise IT infrastructure buyers. Decision-maker designations interviewed include VP-level Infrastructure Sourcing, Heads of Data Center Strategy, Technical Directors of Facilities Engineering, and Commercial Operations Leads responsible for lease structuring. Interview programs were stratified by facility tier and region to ensure balanced representation across mature and emerging metros.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Infrastructure Sourcing
30%
Heads of Data Center Strategy
28%
Technical Facilities Directors
24%
Commercial Operations Leads
18%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Wholesale Campus Developers
30%
Retail Colocation Operators
25%
Hyperscale Procurement Teams
20%
Interconnection & Connectivity Providers
15%
Enterprise IT Buyers
10%
Secondary Benchmarking & Public Trade Validation
Findings are validated against official multilateral and regulatory sources, including UN Comtrade for cross-border equipment and services flows, WTO services trade statistics, US International Trade Commission filings, and Eurostat digital-economy indicators. Corporate annual filings, 10-K disclosures, and investor presentations from listed operators were used to reconcile capacity and revenue claims. Uptime Institute certification standards, IEA energy and AI datasets, and national data-protection statutes (EU Data Act, India DPDP Act, Saudi PDPL) anchor the regulatory and technical validation layer.
Demand Modeling & Market Sizing Triangulation
Top-down sizing allocates macroeconomic digital-infrastructure spend across facility tiers and regions using segment share data. Bottom-up modeling builds revenue from operator capacity, per-kilowatt pricing, and contracted utilization rates, cross-checked against net absorption figures in primary markets. Divergences between the two approaches are resolved through stakeholder re-interview and definitional reconciliation.
Data Triangulation & Validation Matrix
Dimension
Analytical Scope
Methodology Applied
Validation Level
Base-Year Market Size
USD value for 2025–2026
Bottom-up capacity and revenue triangulation
High
Forecast Horizon
2026–2035 compound projection
Historical CAGR, regression, demand elasticity
High
Regional Distribution
Regional share breakdown
Trade flow analysis and regional consumption
High
Competitive Landscape
Leading market players
Annual reports, capacity mapping, filings
High
Sources Referenced
International Energy Agency (IEA) — Energy and AI datasets
Uptime Institute — Tier certification and rack-density surveys
UN Comtrade and Eurostat — digital infrastructure trade and services flows
US Securities and Exchange Commission — 10-K and investor filings
CBRE North America Data Center Trends — absorption and construction benchmarks
Figure 16:
Figure 17: Europe Data Center Colocation Market Revenue Share (%), by Colocation Type 2026 & 2034
Figure 18: Europe Data Center Colocation Market Revenue (Billion), by Tier Level 2026 & 2034
Figure 19: Europe Data Center Colocation Market Revenue Share (%), by Tier Level 2026 & 2034
Figure 20: Europe Data Center Colocation Market Revenue (Billion), by Facility Size 2026 & 2034
Figure 21: Europe Data Center Colocation Market Revenue Share (%), by Facility Size 2026 & 2034
Figure 22: Europe Data Center Colocation Market Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 23: Europe Data Center Colocation Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 24: Europe Data Center Colocation Market Revenue (Billion), by End Use 2026 & 2034
Figure 25: Europe Data Center Colocation Market Revenue Share (%), by End Use 2026 & 2034
Figure 26: Europe Data Center Colocation Market Revenue (Billion), by Power Capacity 2026 & 2034
Figure 27: Europe Data Center Colocation Market Revenue Share (%), by Power Capacity 2026 & 2034
Figure 28: Europe Data Center Colocation Market Revenue (Billion), by Country 2026 & 2034
Figure 29: Europe Data Center Colocation Market Revenue Share (%), by Country 2026 & 2034
Figure 30: Asia-Pacific Data Center Colocation Market Revenue (Billion), by Colocation Type 2026 & 2034
Figure 31: Asia-Pacific Data Center Colocation Market Revenue Share (%), by Colocation Type 2026 & 2034
Figure 32: Asia-Pacific Data Center Colocation Market Revenue (Billion), by Tier Level 2026 & 2034
Figure 33: Asia-Pacific Data Center Colocation Market Revenue Share (%), by Tier Level 2026 & 2034
Figure 34: Asia-Pacific Data Center Colocation Market Revenue (Billion), by Facility Size 2026 & 2034
Figure 35: Asia-Pacific Data Center Colocation Market Revenue Share (%), by Facility Size 2026 & 2034
Figure 36: Asia-Pacific Data Center Colocation Market Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 37: Asia-Pacific Data Center Colocation Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 38: Asia-Pacific Data Center Colocation Market Revenue (Billion), by End Use 2026 & 2034
Figure 39: Asia-Pacific Data Center Colocation Market Revenue Share (%), by End Use 2026 & 2034
Figure 40: Asia-Pacific Data Center Colocation Market Revenue (Billion), by Power Capacity 2026 & 2034
Figure 41: Asia-Pacific Data Center Colocation Market Revenue Share (%), by Power Capacity 2026 & 2034
Figure 42: Asia-Pacific Data Center Colocation Market Revenue (Billion), by Country 2026 & 2034
Figure 43: Asia-Pacific Data Center Colocation Market Revenue Share (%), by Country 2026 & 2034
Figure 44: Latin America Data Center Colocation Market Revenue (Billion), by Colocation Type 2026 & 2034
Figure 45: Latin America Data Center Colocation Market Revenue Share (%), by Colocation Type 2026 & 2034
Figure 46: Latin America Data Center Colocation Market Revenue (Billion), by Tier Level 2026 & 2034
Figure 47: Latin America Data Center Colocation Market Revenue Share (%), by Tier Level 2026 & 2034
Figure 48: Latin America Data Center Colocation Market Revenue (Billion), by Facility Size 2026 & 2034
Figure 49: Latin America Data Center Colocation Market Revenue Share (%), by Facility Size 2026 & 2034
Figure 50: Latin America Data Center Colocation Market Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 51: Latin America Data Center Colocation Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 52: Latin America Data Center Colocation Market Revenue (Billion), by End Use 2026 & 2034
Figure 53: Latin America Data Center Colocation Market Revenue Share (%), by End Use 2026 & 2034
Figure 54: Latin America Data Center Colocation Market Revenue (Billion), by Power Capacity 2026 & 2034
Figure 55: Latin America Data Center Colocation Market Revenue Share (%), by Power Capacity 2026 & 2034
Figure 56: Latin America Data Center Colocation Market Revenue (Billion), by Country 2026 & 2034
Figure 57: Latin America Data Center Colocation Market Revenue Share (%), by Country 2026 & 2034
Figure 58: Middle East & Africa Data Center Colocation Market Revenue (Billion), by Colocation Type 2026 & 2034
Figure 59: Middle East & Africa Data Center Colocation Market Revenue Share (%), by Colocation Type 2026 & 2034
Figure 60: Middle East & Africa Data Center Colocation Market Revenue (Billion), by Tier Level 2026 & 2034
Figure 61: Middle East & Africa Data Center Colocation Market Revenue Share (%), by Tier Level 2026 & 2034
Figure 62: Middle East & Africa Data Center Colocation Market Revenue (Billion), by Facility Size 2026 & 2034
Figure 63: Middle East & Africa Data Center Colocation Market Revenue Share (%), by Facility Size 2026 & 2034
Figure 64: Middle East & Africa Data Center Colocation Market Revenue (Billion), by Enterprise Size 2026 & 2034
Figure 65: Middle East & Africa Data Center Colocation Market Revenue Share (%), by Enterprise Size 2026 & 2034
Figure 66: Middle East & Africa Data Center Colocation Market Revenue (Billion), by End Use 2026 & 2034
Figure 67: Middle East & Africa Data Center Colocation Market Revenue Share (%), by End Use 2026 & 2034
Figure 68: Middle East & Africa Data Center Colocation Market Revenue (Billion), by Power Capacity 2026 & 2034
Figure 69: Middle East & Africa Data Center Colocation Market Revenue Share (%), by Power Capacity 2026 & 2034
Figure 70: Middle East & Africa Data Center Colocation Market Revenue (Billion), by Country 2026 & 2034
Figure 71: Middle East & Africa Data Center Colocation Market Revenue Share (%), by Country 2026 & 2034
Table 16:
Table 17: Mexico Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 18: Europe Data Center Colocation Market Revenue Billion Forecast, by Colocation Type 2020 & 2034
Table 19: Europe Data Center Colocation Market Revenue Billion Forecast, by Tier Level 2020 & 2034
Table 20: Europe Data Center Colocation Market Revenue Billion Forecast, by Facility Size 2020 & 2034
Table 21: Europe Data Center Colocation Market Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 22: Europe Data Center Colocation Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 23: Europe Data Center Colocation Market Revenue Billion Forecast, by Power Capacity 2020 & 2034
Table 24: Europe Data Center Colocation Market Revenue Billion Forecast, by Country 2020 & 2034
Table 25: Germany Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 26: UK Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 27: France Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 28: Netherlands Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 29: Ireland Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 30: Asia-Pacific Data Center Colocation Market Revenue Billion Forecast, by Colocation Type 2020 & 2034
Table 31: Asia-Pacific Data Center Colocation Market Revenue Billion Forecast, by Tier Level 2020 & 2034
Table 32: Asia-Pacific Data Center Colocation Market Revenue Billion Forecast, by Facility Size 2020 & 2034
Table 33: Asia-Pacific Data Center Colocation Market Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 34: Asia-Pacific Data Center Colocation Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 35: Asia-Pacific Data Center Colocation Market Revenue Billion Forecast, by Power Capacity 2020 & 2034
Table 36: Asia-Pacific Data Center Colocation Market Revenue Billion Forecast, by Country 2020 & 2034
Table 37: China Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 38: Japan Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 39: India Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 40: Singapore Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 41: Australia Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 42: South Korea Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 43: Latin America Data Center Colocation Market Revenue Billion Forecast, by Colocation Type 2020 & 2034
Table 44: Latin America Data Center Colocation Market Revenue Billion Forecast, by Tier Level 2020 & 2034
Table 45: Latin America Data Center Colocation Market Revenue Billion Forecast, by Facility Size 2020 & 2034
Table 46: Latin America Data Center Colocation Market Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 47: Latin America Data Center Colocation Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 48: Latin America Data Center Colocation Market Revenue Billion Forecast, by Power Capacity 2020 & 2034
Table 49: Latin America Data Center Colocation Market Revenue Billion Forecast, by Country 2020 & 2034
Table 50: Brazil Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 51: Mexico Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 52: Chile Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 53: Argentina Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 54: Middle East & Africa Data Center Colocation Market Revenue Billion Forecast, by Colocation Type 2020 & 2034
Table 55: Middle East & Africa Data Center Colocation Market Revenue Billion Forecast, by Tier Level 2020 & 2034
Table 56: Middle East & Africa Data Center Colocation Market Revenue Billion Forecast, by Facility Size 2020 & 2034
Table 57: Middle East & Africa Data Center Colocation Market Revenue Billion Forecast, by Enterprise Size 2020 & 2034
Table 58: Middle East & Africa Data Center Colocation Market Revenue Billion Forecast, by End Use 2020 & 2034
Table 59: Middle East & Africa Data Center Colocation Market Revenue Billion Forecast, by Power Capacity 2020 & 2034
Table 60: Middle East & Africa Data Center Colocation Market Revenue Billion Forecast, by Country 2020 & 2034
Table 61: Saudi Arabia Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 62: UAE Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 63: South Africa Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 64: Israel Data Center Colocation Market Revenue (Billion) Forecast, by Application 2020 & 2034
 Data Center Colocation Market