 AI Search Engine Market
 Size, Share & Forecast 2026
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 256

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 AI Search Engine Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 16.30 B |
| 2026 | 20.75 B |
| 2027 | 26.02 B |
| 2028 | 32.63 B |
| 2029 | 40.92 B |
| 2030 | 51.31 B |
| 2031 | 64.34 B |

The AI search engine market covers software platforms that use machine learning, natural language processing and generative models to interpret user intent and return synthesized, personalized, multimodal answers rather than ranked links. It spans consumer web search, enterprise knowledge search, voice and visual search, and embedded e-commerce search delivered via cloud or on-premises infrastructure.
This analysis covers AI-native search platforms and the AI layers retrofitted onto incumbent engines, segmented by technology, application, deployment, organization size and end use, across five regions. Revenue includes subscriptions, advertising, API and licensing fees.
This analysis does not cover general-purpose chatbot subscriptions without retrieval capability, standalone vector database software, conventional SEO tooling, or advertising technology platforms not embedded in a search interface. Hardware, data-center construction and semiconductor supply are treated only as cost drivers.
Estimates diverge sharply because publishers define "AI search" differently — some count only AI-native platforms, others count the AI-attributed portion of incumbent search revenue.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 18.3 Billion | 2025 | 2033 | 13.8% | Enterprise-weighted AI search software, all deployment | One published estimate |
| 20.6 Billion | 2026 | 2033 | 13.8% | Same series, forward base | One published estimate |
| 49.83 Billion | 2026 | 2033 | 14.2% | Broad AI search including advertising-linked revenue | A competing analysis |
| 17.55 Billion | 2025 | 2032 | 13.3% | AI search software by organization size and end use | A competing analysis |
| 20.75 Billion | 2026 | 2035 | 27.3% | AI-native plus AI-attributed incumbent search, consumer included | A competing analysis |
Our analysis suggests the 20.6–20.75 Billion band for 2026 is the most defensible base, because it reconciles enterprise software revenue with consumer AI search adoption. The 27.3% CAGR is aggressive but plausible if generative answer monetization and agentic commerce scale; the 13.3–14.2% band better reflects software-only scope. Buyers should anchor budgets to the mid-teens and model upside separately.
Segmentation matters because growth rates differ by a factor of two across segments — selecting the wrong slice distorts investment cases materially.
| Parent segment | Children | Leading share (2026) | Fastest-growing child |
|---|---|---|---|
| By Technology | NLP, Machine Learning, Deep Learning, Reinforcement Learning, AI Algorithms, Generative AI | NLP ~30–32% | Generative AI |
| By Application | Web Search, Enterprise Search, Voice & Visual Search, E-commerce Search | Web search 62.7% | E-commerce search |
| By Deployment | Cloud, On-premises | Cloud ~55–60% | Cloud |
| By Organization Size | Large Enterprises, SMEs | Large enterprises 60% | SMEs |
| By End Use | Retail & E-commerce, IT & Telecom, BFSI, Healthcare, Media, Education, Travel, Manufacturing | Retail & e-commerce | Healthcare |
Our analysis suggests the SME and healthcare slices are under-modeled by most buyers. Affordable cloud AI search removes the infrastructure barrier that once confined these capabilities to large enterprises, compressing sales cycles but also compressing average contract values.
North America leads the global AI search engine market with roughly 37–41% revenue share in 2026, underpinned by hyperscaler R&D, enterprise cloud maturity and supportive AI research policy. Asia Pacific is the fastest-growing region, expanding on mobile-first demand and state digital programs.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.22% |
| Asia-Pacific | 0.29% |
| Latin America | 0.06% |
| Middle East & Africa | 0.06% |
| Region | 2026 share | Growth posture |
|---|---|---|
| North America | ~37% | Mature, monetization-led |
| Asia Pacific | ~29% | Fastest; mobile and vernacular |
| Europe | ~22% | Regulation-constrained, privacy-led |
| Latin America | ~6% | Early, price-sensitive |
| Middle East & Africa | ~6% | Infrastructure-led expansion |
This divergence implies Western vendors cannot assume global pricing power. In India and Southeast Asia, vernacular and voice-first interfaces determine adoption more than model quality, rewarding localization investment over raw benchmark leadership.
Growth is driven by three reinforcing forces: explosive data volume demanding semantic retrieval, generative AI's ability to answer multi-part conversational queries, and cloud delivery that makes enterprise-grade search affordable for mid-market buyers.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| NLP and generative AI capability | Driver | High | Answers complex, ambiguous queries without link browsing |
| Data explosion and digital transformation | Driver | High | Semantic retrieval replaces keyword matching at scale |
| Personalization and context awareness | Driver | High | Behavioral signals raise relevance and engagement |
| Cloud scalability and plug-and-play SME offers | Driver | Medium | Lowers entry cost, shortens deployment |
| Privacy and cross-border data regulation | Restraint | High | Raises compliance cost, limits training data |
| Hallucination and misinformation risk | Restraint | High | Erodes trust, forces verification spend |
| Compute and infrastructure cost | Restraint | Medium | Compresses vendor margins at scale |
| Antitrust scrutiny of default distribution | Restraint | Medium | Constrains incumbent distribution moats |
Our analysis suggests the restraint balance is shifting. Trust and attribution are becoming purchase criteria rather than afterthoughts: the vendors that can prove citation lineage and control hallucination rates will win enterprise deals even at a price premium.
Google and Microsoft are the clear forerunners, combining proprietary models, global distribution and productivity-suite integration. Baidu leads China with its ERNIE stack, while Perplexity AI and You.com compete on citation transparency and privacy positioning.
| Vendor | Position | Core differentiator | Primary segment |
|---|---|---|---|
| Forerunner | Gemini models, AI Overviews, ecosystem reach | Consumer and enterprise web | |
| Microsoft | Forerunner | OpenAI partnership, Bing and Copilot integration | Enterprise productivity |
| Baidu | Innovator | ERNIE model, cost-efficient inference, China scale | Consumer and business search |
| Perplexity AI | Innovator | Cited answers, Comet browser, subscription model | Prosumer and enterprise |
| You.com | Innovator | Privacy-first, vertical customization | Enterprise and developer |
| Alibaba / Tencent | Regional leader | Commerce and messaging search integration | E-commerce and social |
| Anthropic / Algolia | Specialist | Safety-focused AI, search-as-a-service APIs | Enterprise search |
Moat durability differs by layer. Distribution moats favor incumbents; model-quality moats are eroding as open-weight models close the gap. Our analysis suggests defensibility increasingly sits in proprietary retrieval indexes, enterprise integrations and trust infrastructure — not in the underlying model.
Selection criteria should center on retrieval accuracy on your own corpus, not vendor benchmarks. Demand a proof-of-concept against representative queries, and measure hallucination rate, citation precision and latency under peak load before signing.
Procurement risk concentrates in three areas. First, cost variability — generative inference pricing is volatile, so insist on capped or predictable usage tiers. Second, switching costs — index and embedding pipelines are sticky; negotiate data portability and export rights upfront. Third, compliance — under GDPR and comparable regimes, confirm where queries and training data are processed and whether logs are retained.
Operators should also model the zero-click effect: as answers surface directly in the interface, referral traffic declines, reshaping content and SEO strategies. Enterprises embedding AI search into customer-facing products must plan for attribution, brand-safety and content-licensing obligations alongside technical integration.
The balance of evidence favors a mid-teens CAGR as the planning baseline, with a genuine upside scenario above 25% if agentic commerce and subscription monetization mature. The low-end estimates understate consumer adoption; the high-end estimates assume pricing power that regulation and open-weight competition may erode.
The strongest counter-argument is that AI search is a feature, not a market — that incumbents will absorb it into existing platforms and standalone vendors will be squeezed on distribution. That view has merit for consumer search, but it underweights enterprise vertical search, where domain-specific retrieval and compliance requirements create durable niches.
What would change this conclusion: a sharp fall in inference costs combined with standardized citation regulation would accelerate commoditization, pushing value toward distribution owners and away from model-layer specialists. Conversely, enterprise trust failures at scale would slow adoption materially in regulated sectors.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
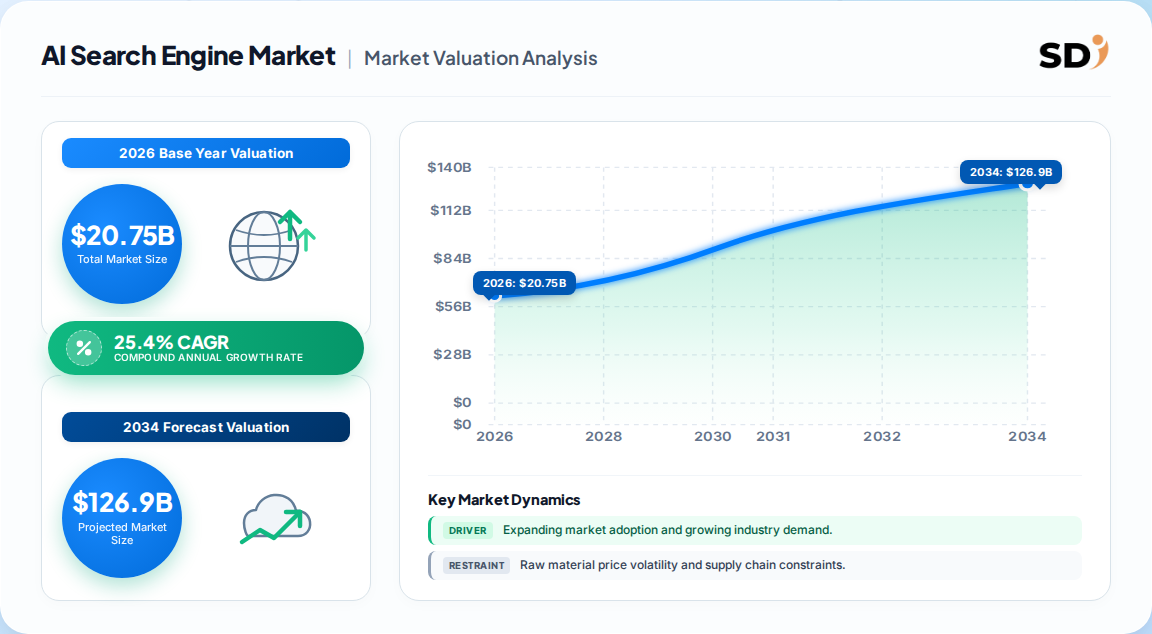
| Growth Rate | CAGR of 25.4% from 2020-2034 |
| Segmentation |
|
The global AI search engine market is estimated at approximately 20.75 Billion in 2026, with published estimates ranging from 20.6 Billion to 49.83 Billion depending on whether advertising-linked incumbent revenue is included. Most software-focused analyses cluster near the 20 Billion mark.
Published CAGRs range from 13.3% to 27.3% through the early 2030s. A mid-teens rate is the defensible planning baseline for software scope, while the high-20s figure assumes rapid monetization of generative answers and agentic commerce.
North America leads with roughly 37–41% revenue share, supported by hyperscaler investment and enterprise cloud maturity. Asia Pacific is the fastest-growing region, driven by China, India and Japan on mobile-first and vernacular demand.
Google and Microsoft are the forerunners, combining proprietary models with global distribution. Baidu leads China, while Perplexity AI, You.com, Alibaba, Tencent and enterprise specialists such as Algolia and Anthropic compete on citations, privacy and vertical depth.
Three forces dominate: generative AI's ability to answer complex conversational queries, explosive digital data volume requiring semantic retrieval, and cloud delivery that makes enterprise-grade search affordable for mid-market and SME buyers.
Hallucination and misinformation erode user trust, privacy and cross-border data rules raise compliance costs, and heavy inference requirements compress vendor margins. Antitrust scrutiny of default distribution also constrains incumbent moats.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split. Structured depth interviews were conducted with decision-makers across the AI search value chain, including foundation-model and infrastructure providers, search platform vendors, enterprise software integrators, cloud distributors and vertical search specialists. Within client organizations we interviewed VP-level search and platform owners, Heads of Data and AI, Chief Information Security Officers and Commercial Operations Leads responsible for procurement. Interview programs targeted quota-based samples across enterprise and SME buyers in five regions to capture divergent adoption economics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Heads of Data & AI | 38% |
| VP Search & Platform Owners | 27% |
| Procurement & Commercial Operations | 20% |
| Security & Compliance Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Search Platform & Model Vendors | 40% |
| Enterprise Software & Integrators | 28% |
| Cloud Infrastructure & Distribution | 20% |
| Vertical & Specialist Search Providers | 12% |
Secondary validation draws on official multilateral and standards sources, including UN Comtrade for cross-border digital services trade, WTO and OECD digital-economy statistics, US ITC and Eurostat filings, and national statistical offices. Corporate evidence includes 10-K and SEC filings, annual investor presentations and earnings disclosures from listed search and cloud vendors. Patent databases and technical standards bodies inform technology-readiness assessment. No third-party market-research publisher data is used as a validation source.
We run simultaneous top-down and bottom-up models. Top-down allocates macroeconomic digital-advertising and enterprise software spend to search-attributed revenue by segment. Bottom-up models vendor revenue, seat pricing, query volumes and inference cost per query, then reconciles the two against reported financials. Divergence beyond a defined tolerance triggers re-interrogation of assumptions rather than simple averaging.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up vendor revenue and query-volume triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border digital services trade and regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping and commercial filings | High |