 Aviation Software Market
 Outlook 2026: Size, CAGR & Trends
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 220

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Aviation Software Market
Srinwanti Kar
Senior Research Analyst

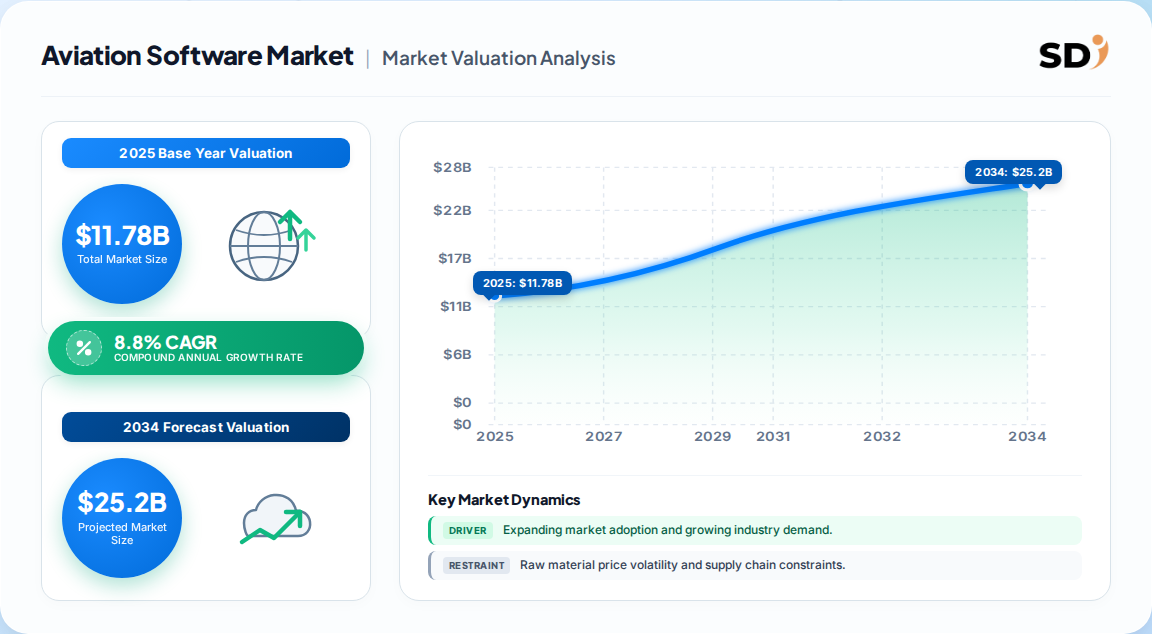
| Year | Market Size |
|---|---|
| 2025 | 11.78 B |
| 2026 | 12.50 B |
| 2027 | 13.60 B |
| 2028 | 14.80 B |
| 2029 | 16.10 B |
| 2030 | 17.50 B |
| 2031 | 19.00 B |

The aviation software market covers commercial and operational software used by airlines, airports, ground handlers, MRO providers and air navigation service providers — spanning flight operations, maintenance, crew management, passenger services, air traffic management, safety compliance and aviation analytics. It excludes onboard avionics firmware and general enterprise ERP sold outside aviation verticals.
This analysis covers software sold to aviation operators across airline, airport and MRO end users, in cloud, on-premise and hybrid deployment modes, globally. It includes licensing, subscription and pay-as-you-go commercial models. This analysis does not cover aircraft avionics and embedded flight-control firmware, aerospace manufacturing CAD/PLM outside aviation-specific verticals, or general-purpose enterprise software not purpose-built for aviation operations.
The global aviation software market was valued at approximately 11.78 Billion in 2025 and is forecast to reach roughly 22.5–25.5 Billion by 2033, with estimates clustering around an 8.8% CAGR. The spread across published figures reflects differing treatment of MRO analytics and simulation software.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 12.5 Billion | 2026 | 2033 | 8.8% | Software type, deployment, airline/airport application | One published estimate |
| 13.0 Billion | 2026 | 2033 | 10.1% | Broader 10-category application taxonomy, hybrid included | Competing analysis |
| 11.78 Billion | 2025 | 2035 | 8.8% | Cloud, on-prem, subscription and SaaS licensing | Another published study |
Our analysis suggests the lower-CAGR cluster is more defensible. The 10.1% figure appears to fold broader simulation and design software into the aviation category, which inflates the base and growth rate simultaneously. The 8.8% trajectory is consistent with the actual pace of airline IT budget expansion and with ICAO-documented integration overruns that slow deployment cycles.
Segmentation follows three primary axes — application, deployment mode and end user — with application the most commercially decisive for vendor positioning and pricing power.
| Axis | Leading segment | Share (2025) | Fastest-growing segment |
|---|---|---|---|
| Application | MRO software | ~34% | Analytics & simulation (~10–12% CAGR) |
| Deployment | Cloud | 66–70% | On-premise (defense-driven) |
| End user | Airlines | 77–78% | Airports & ground handlers (~10.9% CAGR) |
| Licensing | Subscription SaaS | ~58.6% | Pay-as-you-go (regional carriers) |
So what: The cloud-versus-on-premise split is no longer the strategic battleground. Differentiation now sits in analytics layering atop MRO and flight-operations systems, where switching costs are highest and margins most durable.
North America leads the global aviation software market with roughly 36% revenue share, underpinned by FAA regulatory mandates, high fleet density and the headquarters presence of major vendors including Jeppesen and Honeywell.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.24% |
| Asia-Pacific | 0.24% |
| Latin America | 0.06% |
| Middle East & Africa | 0.1% |
This divergence implies that North American revenue is largely replacement and upgrade spend, while Asia Pacific growth is greenfield. Vendors optimized for legacy migration will defend share in the former; those with low-touch, modular deployment models will win the latter.
Demand is being pulled by digital transformation of airline operations and pushed back by integration complexity and cybersecurity exposure. The net effect is steady rather than explosive growth.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Airline digital transformation | Driver | Strong | 10–15% operational cost reduction among fully digitized carriers |
| Regulatory compliance mandates | Driver | Strong | FAA/EASA EFB and digital maintenance record requirements |
| Fleet expansion (44,000+ aircraft to 2040) | Driver | Strong | Scalable software architecture required |
| AI predictive maintenance | Driver | Moderate–Strong | Up to 35% fewer unscheduled maintenance events |
| Legacy migration cost | Restraint | Strong | 20–30% typical budget overrun on transition projects |
| Cybersecurity exposure | Restraint | Moderate | 53% rise in transport-sector cyberattacks, 2021–2024 |
The balance of evidence favors the drivers. Compliance mandates are non-discretionary, which converts a portion of this market into effectively captive demand. Restraints are real but primarily affect small and mid-sized operators, thinning the long tail of buyers rather than suppressing overall spend.
The competitive field splits between aerospace primes with embedded software portfolios and enterprise IT incumbents with aviation vertical solutions. No single vendor holds dominant share.
| Vendor | Primary strength | Competitive moat |
|---|---|---|
| Honeywell | Flight ops, avionics integration | Installed base and certification depth |
| RTX Corporation | ATM, connected aviation | Defense and ANSP relationships |
| Thales | ATM, cockpit systems | Regulatory certification |
| GE | Predictive maintenance analytics | Engine telemetry data access |
| Boeing / Airbus | Design, simulation, digital twins | OEM data asymmetry |
| SAP / IBM | Enterprise airline platforms | ERP integration lock-in |
| Amadeus IT Group | Passenger service, commercial | Network effects in distribution |
Moat analysis: The durable advantages here are certification pedigree and data asymmetry — not feature breadth. Vendors with proprietary telemetry access (engine OEMs) or regulatory approval history (avionics primes) can defend pricing even as cloud-native entrants compress feature-level differentiation.
Selection criteria in this category are unforgiving because failure modes are regulatory, not merely financial. Buyers should weight certified compliance coverage — EASA and FAA audit trails, digital maintenance records, automated safety reporting — above interface quality or headline price.
Procurement risk concentrates in migration. Parallel system operation during cutover, retraining load and prolonged validation phases routinely push transition budgets 20–30% over plan. Mid-sized carriers and regional MRO providers are most exposed, and should negotiate phased deployment with contractual exit ramps.
Switching costs rise steeply after two to three years of operational data accumulation. Buyers should therefore secure data portability and export rights at contract signature, not renewal. Cybersecurity posture — vendor certifications, intrusion detection, data sovereignty guarantees — should be a scored criterion rather than a checkbox.
The balance of evidence favors a steady, compliance-anchored expansion path at roughly 8.8% CAGR rather than the higher 10.1% trajectory. Compliance mandates make a meaningful share of this demand non-discretionary, and the migration-cost restraint disproportionately removes small buyers rather than suppressing enterprise spend. The result is a market that grows reliably while consolidating toward vendors with certification pedigree.
The strongest counter-argument is AI-driven analytics. If predictive maintenance and route optimization deliver the claimed 35% reduction in unscheduled events and 1.5 Billion in annual industry fuel savings, analytics could become a standalone budget line rather than an MRO add-on — accelerating growth beyond consensus. The evidence for these figures is credible but not yet demonstrated at fleet scale.
What would change our conclusion: Sustained evidence that AI analytics attach rates exceed 40% of new MRO deployments, or a material relaxation in legacy migration costs, would justify migrating to the higher 10.1% growth case.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.8% from 2020-2034 |
| Segmentation |
|
The global aviation software market was valued at approximately 11.78 Billion in 2025, with forecasts placing 2026 near 12.5 Billion. Projections reach roughly 22.5 to 25.5 Billion by 2033, depending on how broadly simulation and design software are classified.
Consensus forecasts cluster around an 8.8% CAGR from 2026 to 2033. One published estimate runs higher at 10.1%, largely because it includes a broader application taxonomy covering design and simulation software within the aviation category.
MRO software leads by application with roughly 34% share in 2025, driven by predictive maintenance and fleet lifecycle management. Cloud deployment dominates at 66 to 70% of revenue, and airlines represent 77 to 78% of end-user spend.
North America holds the largest share at approximately 36%, supported by FAA mandates, high fleet density and major vendor headquarters. Asia Pacific is the fastest-growing region, with CAGRs cited between 10% and 12% on airport expansion programs.
Leading vendors include Honeywell, RTX Corporation, Thales Group, General Electric, Boeing, Airbus, SAP, IBM, Northrop Grumman and Amadeus IT Group. Competition centers on certification pedigree and proprietary operational data access rather than feature breadth.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a deliberate 70/30 primary-to-secondary split, prioritizing direct verification of commercial and operational reality over published aggregation. Fieldwork comprised structured depth interviews across the aviation software value chain: aerospace software developers, systems integrators, MRO technology providers, airline IT departments and air navigation service vendors. Interviews were conducted with decision-makers holding direct procurement and technical authority, specifically VP-level Sourcing leads, Heads of Airline IT and Digital Transformation, Technical Directors of Maintenance Systems, and Commercial Operations Leads responsible for platform licensing. Each interview probed deployment timelines, migration costs, certification requirements and switching behavior, producing verified inputs rather than extrapolated assumptions.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement Leads | 35% |
| Heads of Airline IT & Digital Transformation | 30% |
| Technical Directors, Maintenance Systems | 22% |
| Commercial Operations Leads | 13% |
| Company Type | Representation (%) |
|---|---|
| Aviation Software Developers & ISVs | 40% |
| Systems Integrators & MRO Technology Providers | 30% |
| Airline & Airport IT Operators | 20% |
| Air Navigation Service Vendors | 10% |
All primary findings were cross-validated against official multilateral and regulatory sources. Corporate annual filings, SEC Form 10-K disclosures and investor presentations from listed aviation technology vendors provided revenue and segment-level verification. Patent databases informed analysis of AI and predictive-maintenance innovation pipelines. Regulatory frameworks and safety directives issued by the FAA and EASA were reviewed to establish compliance-driven demand baselines, alongside IATA traffic statistics and ICAO technology transition reporting.
Market sizing was triangulated simultaneously from two directions. Top-down modeling allocated macroeconomic aviation IT expenditure across application and deployment segments using published operator budget ratios. Bottom-up modeling built revenue from vendor-level software license and subscription volumes, multiplied by verified pricing tiers and end-use consumption by airline, airport and MRO operator counts.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up vendor revenue & subscription triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |