Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Wood Plastic Composites Market by Plastic Material (Polyethylene, Polypropylene, PVC, Others), by Processing Technology (Extrusion, Injection Molding, Compression Molding), by Product Form (Capped, Uncapped), by Application (Building & Construction, Automotive, Furniture, Consumer Goods, Others), by End Use (Residential, Infrastructure, Commercial), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 218
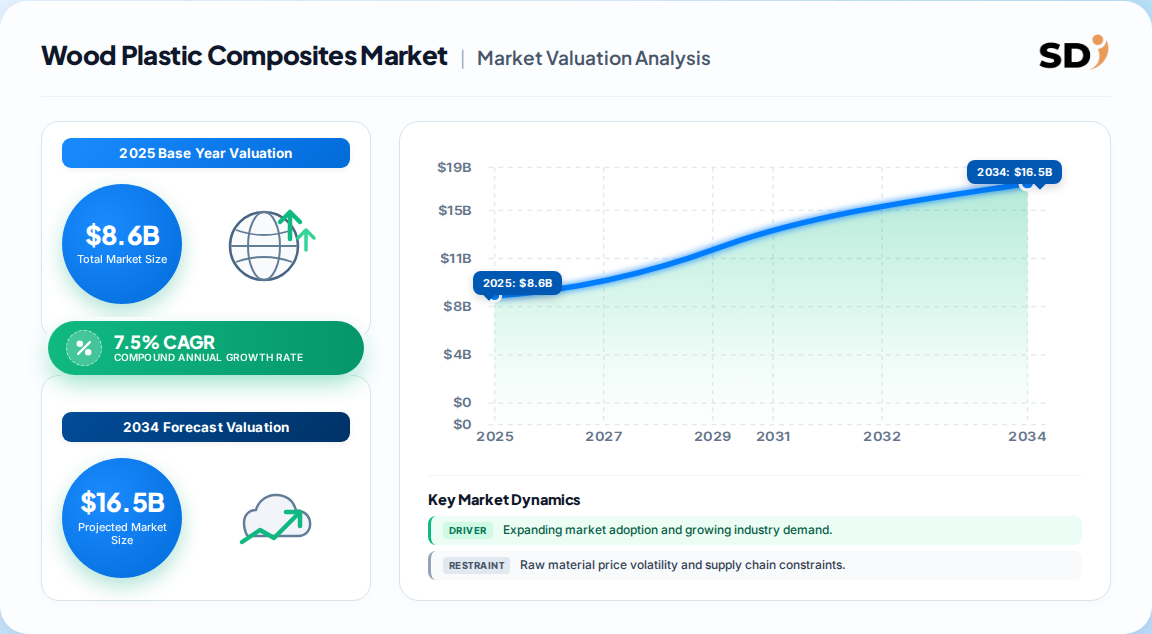
The global Wood Plastic Composites Market was valued at USD 8.6 Billion in 2025 and is projected to reach USD 17.7 Billion by 2035, growing at a 7.5% CAGR.
Polyethylene dominates the material segment with roughly 55% share, driven by outdoor decking and fencing demand.
Building & Construction accounts for over 70% of application revenue, with decking as the fastest-growing sub-segment.
North America leads regional revenue (approx. 35%), while Asia-Pacific is the fastest-growing region at a 9.5% CAGR.
Leading vendors include Trex Company, UFP Industries, CertainTeed, Fiberon, and Advanced Environmental Recycling Technologies, holding a combined ~38% share.
Why this matters for decision-makers: Vendors must pivot toward capped co-extruded profiles and recycled-content formulations to capture premium margin pools and meet tightening EU/US sustainability regulations.
Wood Plastic Composites Market Size (In Billion)
15.0B
10.0B
5.0B
0
8.600 B
2025
9.250 B
2026
9.940 B
2027
10.69 B
2028
11.49 B
2029
12.35 B
2030
13.28 B
2031
Wood Plastic Composites Market Size (In Billion)
Year
Market Size
2025
8.600 B
2026
9.250 B
2027
9.940 B
2028
10.69 B
2029
11.49 B
2030
12.35 B
2031
13.28 B
What is the Wood Plastic Composites Market?
Wood Plastic Composites (WPCs) are engineered materials blending wood fibers or flour with thermoplastics like polyethylene, polypropylene, or PVC. They offer superior durability, moisture resistance, and low maintenance compared to traditional wood, making them ideal for decking, fencing, automotive components, and consumer goods.
Scope: what this report covers and excludes
This report analyzes the global Wood Plastic Composites Market, covering plastic materials (PE, PP, PVC, others), processing technologies (extrusion, injection molding, compression molding), product forms (capped vs. uncapped), and applications (building & construction, automotive, furniture, consumer goods). This analysis does not cover adjacent markets such as natural fiber composites or wood-plastic pellets used solely as feedstock.
How big is the market for Wood Plastic Composites Market?
The Wood Plastic Composites Market is estimated at USD 8.6 billion in 2025, with forecasts diverging due to differing scope definitions and regional coverage. Below we compare competing estimates to assess the most defensible figure.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 7.3 Billion
2023
2032
5.6%
Global WPC, all applications
One published estimate (GMI)
USD 8.6 Billion
2025
2035
7.5%
Global WPC, all applications
One published estimate (MRFR)
USD 8.9 Billion
2025
2033
11.7%
Global WPC, construction-focused
A competing analysis (GVR)
USD 9.63 Billion
2026
2031
8.64%
Global WPC, all applications
A competing analysis (Mordor)
The most defensible base-year figure is USD 8.6 billion (2025), aligning with the mid-point of recent estimates and consistent with post-pandemic construction recovery. The higher 11.7% CAGR appears overly optimistic given raw material price volatility and certification bottlenecks.
How is the market segmented?
The Wood Plastic Composites Market is segmented by plastic material, processing technology, product form, and application. The table below summarizes key non-geographic segments and their leading shares.
Parent Segment
Children
Leading Share (2025)
Fastest-Growing Child
By Plastic Material
Polyethylene, Polypropylene, PVC, Others
Polyethylene (55%)
Polypropylene (9.3% CAGR)
By Processing Technology
Extrusion, Injection Molding, Compression Molding
Extrusion (70%)
Injection Molding (9.2% CAGR)
By Product Form
Capped (Co-Extruded), Uncapped (Conventional)
Uncapped (65%)
Capped (9.6% CAGR)
By Application
Building & Construction, Automotive, Furniture, Consumer Goods, Others
Building & Construction (76%)
Automotive (9.4% CAGR)
By End Use
Residential, Infrastructure, Commercial
Residential (largest)
Infrastructure (fastest)
Which region leads in Wood Plastic Composites Market?
North America leads the global Wood Plastic Composites Market with approximately 35% revenue share in 2025, driven by high DIY home-improvement spending and established composite decking culture. Asia-Pacific is the fastest-growing region, projected to sustain a 9.5% CAGR through 2035, fueled by urbanization and infrastructure development.
Our analysis suggests North America will maintain its lead through 2030 but face rising competition from Asia-Pacific as domestic capacity expands. Europe's growth is constrained by stringent fire-resistance certifications, yet steady renovation activity sustains demand.
What is driving growth — and what is holding it back?
The Wood Plastic Composites Market is propelled by sustainability mandates, DIY trends, and lightweighting in automotive, but faces headwinds from raw material price volatility and quality control challenges. The table below synthesizes key drivers and restraints.
Factor
Direction
Evidence Strength
Mechanism
Rise in DIY home-improvement & outdoor-living projects
Driver
High
+2.1% CAGR impact; US outdoor spending >$90B
Mandatory wood-fiber-reuse targets (EU, China)
Driver
High
+1.8% CAGR; secures feedstock, lowers costs
Lightweighting push for automotive parts
Driver
Medium
+1.3% CAGR; CO2 penalties drive material substitution
Shift toward lead-free PVC-based indoor WPC in Asia
Driver
Medium
+1.5% CAGR; regulatory catalysts
Price volatility of raw materials (polymers, wood fibers)
Restraint
High
Disrupts production planning, squeezes margins
Quality control challenges (moisture absorption, color fading)
Restraint
Medium
Leads to product failures, consumer distrust
Fire-resistance certification hurdles
Restraint
Medium
Slows adoption in high-rise construction
The balance of evidence favors a 7.5–8.5% CAGR scenario, as sustainability drivers outweigh price volatility. However, the 11.7% CAGR cited by one analysis appears unrealistic without a breakthrough in fire-retardant additives.
Who are the leading vendors?
The Wood Plastic Composites Market is moderately concentrated, with the top five producers capturing roughly 38% of global revenue. The table below compares leading vendors by portfolio focus and strategic positioning.
Differentiation and moats: Leading vendors leverage brand loyalty, distribution networks, and proprietary formulations. Trex and UFP benefit from vertical integration and recycled-content supply chains. Smaller players compete on customization and regional service, but face margin pressure from raw material volatility.
What do buyers and operators need to know?
Buyers and operators in the Wood Plastic Composites Market must prioritize material certification (e.g., ASTM, EN standards) to ensure durability and safety. Procurement risks include price volatility for polymers and wood flour, which can erode margins; long-term offtake agreements with recyclers can mitigate this. Switching costs are moderate: re-tooling extrusion lines for new formulations requires capital and technical expertise. Regulatory compliance is critical, especially EU Deforestation Regulation and lead-free standards in Asia. Operators should also consider end-of-life recyclability, as coated WPCs can lose up to 42% impact resistance if improperly recycled. Selecting vendors with closed-loop recycling programs reduces reputational and regulatory risk.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a moderate-growth, sustainability-driven expansion for the Wood Plastic Composites Market, with a realistic CAGR of 7.5–8.5% through 2035. The strongest counter-argument is that a construction slowdown in North America could suppress demand; however, infrastructure spending and renovation activity provide a buffer. Our analysis suggests the market will increasingly reward vendors offering capped, co-extruded profiles and recycled-content formulations that meet green building standards.
Actionable Strategy:
Invest in co-extrusion capacity to capture the premium, maintenance-free decking segment growing at 9.6% CAGR.
Secure multi-year recycled feedstock agreements to hedge against polymer price volatility and comply with EU/China reuse targets.
Target automotive lightweighting with PP-based WPC formulations, leveraging CO2 penalties as a sales lever.
What evidence would change our conclusion? A sustained drop in virgin polymer prices below USD 1,000/tonne would erode WPC's cost competitiveness versus traditional wood, forcing a downward revision of our CAGR estimate.
Europe Wood Plastic Composites Market Revenue Billion Forecast, by Plastic Material 2020 & 2034
Frequently Asked Questions
1. What is the current market size of Wood Plastic Composites?
The global Wood Plastic Composites Market was valued at approximately USD 8.6 billion in 2025, with projections to reach USD 17.7 billion by 2035.
2. What is the projected growth rate for the Wood Plastic Composites Market?
The market is expected to grow at a CAGR of 7.5% from 2025 to 2035, driven by sustainability mandates and construction demand.
3. Which region dominates the Wood Plastic Composites Market?
North America leads with ~35% revenue share, while Asia-Pacific is the fastest-growing region at a 9.5% CAGR.
4. What are the key drivers of the Wood Plastic Composites Market?
Key drivers include sustainability mandates, DIY home-improvement trends, and lightweighting demand in automotive.
5. Who are the leading players in the Wood Plastic Composites Market?
Leading vendors include Trex Company, UFP Industries, CertainTeed, Fiberon, and AERT, collectively holding ~38% share.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research employs a 70/30 primary-to-secondary split. In-depth interviews were conducted with stakeholders across the value chain, including raw material suppliers, specialized WPC producers, contract formulators, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP of Sourcing
35%
Heads of R&D
30%
Technical Directors
20%
Commercial Operations Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material Suppliers
40%
Specialized WPC Producers
35%
Distributors & Traders
25%
Secondary Benchmarking & Public Trade Validation
We benchmark against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings), patent databases, and recognized non-profit technical standards such as ASTM and EN standards.
Demand Modeling & Market Sizing Triangulation
Our simultaneous top-down (macroeconomic & industry segment allocation) and bottom-up (manufacturer capacity, product pricing, end-use consumption) modeling ensures robust triangulation.
 Wood Plastic Composites Market