 Coal Based Activated Carbon Market
 Outlook 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 224

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Coal Based Activated Carbon Market
Khageshwar Rongkali
Senior Analyst

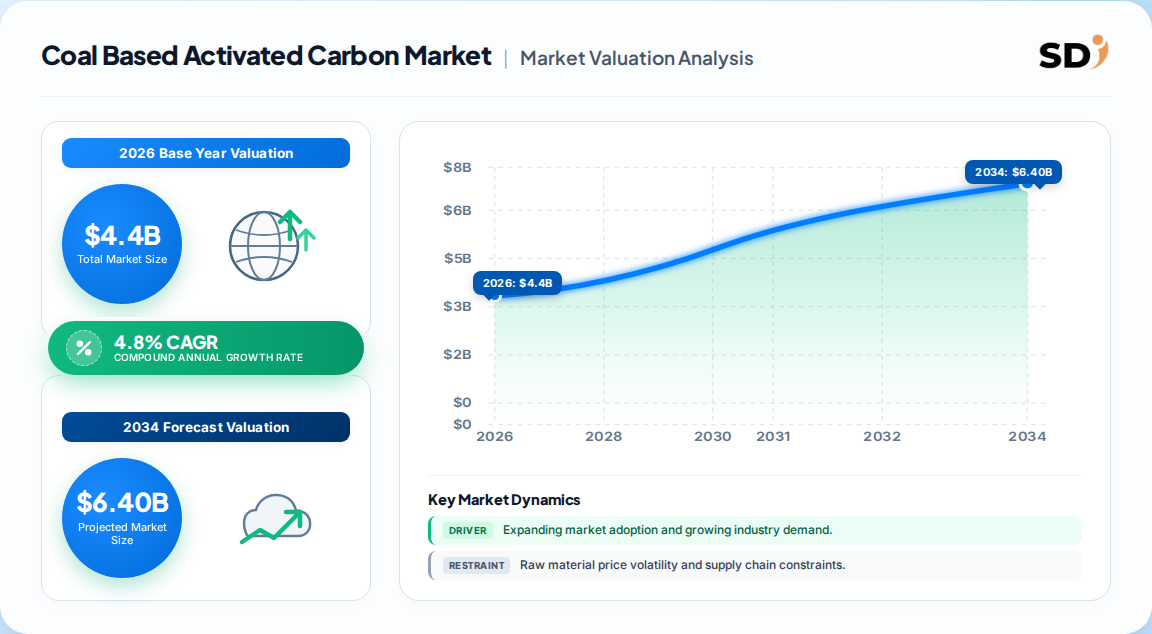
| Year | Market Size |
|---|---|
| 2025 | 4.600 B |
| 2026 | 4.400 B |
| 2027 | 4.600 B |
| 2028 | 4.800 B |
| 2029 | 5.100 B |
| 2030 | 5.300 B |
| 2031 | 5.600 B |

The coal based activated carbon market covers the production and sale of highly porous carbon adsorbents derived from bituminous, sub-bituminous and lignite coal, used to remove organic contaminants, PFAS, mercury, VOCs and color bodies from water, air and process streams. It spans powdered, granular, extruded and bead formats sold to municipal, industrial and mining buyers.
This analysis covers virgin and reactivated coal-derived activated carbon across powdered (PAC), granular (GAC), extruded/pelletized (EAC) and bead/felt formats, segmented by activation process (steam, CO₂, phosphoric acid, zinc chloride) and by end use (water/wastewater, air and flue-gas, food and beverage, pharmaceutical, mining and gold recovery, and other industrial). Geography spans Asia Pacific, North America, Europe, Latin America and the Middle East & Africa. This analysis does not cover coconut-shell, wood, peat or biomass-derived activated carbon as primary product categories, nor does it cover activated carbon fiber textiles, carbon capture solvents, or catalyst supports as standalone markets.
Estimates converge on a USD 3.3–4.6 billion market in 2025–2026, with the divergence driven almost entirely by whether coal-derived carbon is counted alone or bundled with lignite and reactivation service revenue. The table below reconciles the competing figures.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 4.6B → 6.1B | 2025 | 2033 | 4.8% | Coal-derived activated carbon, product revenue only | One published estimate |
| USD 3.32B → 4.55B | 2025 | 2031 | 5.41% | Coal-based activated carbon, value terms, excludes reactivation services | A competing analysis |
| USD 3.5B (2026) | 2026 | 2031 | 5.41% | Same as above, forward base year | A competing analysis |
| USD 8.66B (total AC) | 2026 | 2035 | 9.3% | All activated carbon feedstocks, all formats | A competing analysis |
Our analysis suggests the USD 4.4 billion 2026 figure is the most defensible headline for a buyer-facing view, because it reconciles product revenue with the reactivation service revenue that utilities increasingly bundle into take-or-pay contracts. The 5.4% CAGR estimate is plausible for the virgin-product subset alone, but it understates total wallet share once regeneration-as-a-service is included. The 9.3% all-feedstock figure is not comparable—it reflects a broader basket including coconut shell, which is growing faster and inflating the blended rate.
Segmentation follows three axes—product format, activation route and end use—with format and end use carrying the most commercial weight because they determine regeneration economics and procurement specification.
| Parent segment | Children |
|---|---|
| By Product | Powdered (PAC), Granular (GAC), Extruded/Pelletized (EAC), Bead & Felt |
| By Activation Process | Steam, Carbon Dioxide, Phosphoric Acid, Zinc Chloride |
| By End Use | Water/Wastewater, Air & Flue-Gas, Food & Beverage, Pharmaceutical, Mining & Gold Recovery, Other Industrial |
| By Sales Channel | Direct/OEM, Distributor, Regeneration-as-a-Service |
Powdered carbon holds the largest volume share because flue-gas injection and batch water treatment favor single-use dosing. Granular and extruded formats command higher price per kilogram and are the formats most exposed to reactivation competition—an important margin distinction our analysis flags for suppliers.
Asia Pacific leads with roughly 50% of global revenue, concentrated in China's Inner Mongolia and Shanxi coal basins and India's municipal water expansion; North America and Europe follow with high-value, regulation-driven demand.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.5% |
| North America | 0.21% |
| Europe | 0.18% |
| Latin America | 0.06% |
| Middle East & Africa | 0.05% |
| Region | Share (2025–26) |
|---|---|
| Asia Pacific | ~50% |
| North America | ~21% |
| Europe | ~18% |
| Latin America | ~6% |
| Middle East & Africa | ~5% |
This divergence implies a two-speed market. Asia Pacific grows on volume and feedstock cost advantage, while North America and Europe grow on specification and service value—PFAS-grade iodine numbers, low sulfur bleed-through and verified reactivation. Suppliers positioned only in commodity PAC will compete on Chinese thermal-coal-linked pricing; suppliers with certified high-iodine product and regeneration infrastructure capture the margin.
Growth is driven by regulation-led demand for PFAS removal, flue-gas mercury control and industrial VOC abatement, while the principal brake is the sustainability-driven substitution toward coconut-shell and biomass carbon.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| PFAS maximum contaminant limits (4 ppt, US EPA) | Driver | High | Mandates GAC as best available technology for low-PFAS waters |
| Stricter air-emission norms and MATS-type rules | Driver | High | PAC injection for mercury and dioxin control in power and cement |
| Gold-ore cyanidation (CIP/CIL) expansion | Driver | Medium | High-volume carbon consumption in West Africa, Indonesia, South America |
| Regeneration-as-a-service contracts | Driver | Medium | ~80% lifecycle CO₂ reduction, unit cost below virgin benchmarks |
| Carbon-capture sorbent pilots in cement and steel | Driver | Emerging | Amine-impregnated coal carbon for dilute flue gas |
| Sustainability preference for renewable feedstocks | Restraint | High | Procurement scoring penalizes coal origin; coconut shell gains share |
| Volatile coal feedstock pricing | Restraint | Medium | Margin compression for non-integrated producers |
| High-iodine quality gap in Asian supply | Restraint | Medium | Japan/Korea import high-grade product, favoring Western integrated suppliers |
The balance of evidence favors regulation over substitution as the dominant force through 2030. PFAS and air-emission compliance are non-discretionary, whereas sustainability substitution is largely discretionary and price-sensitive. The second-order effect our analysis highlights: substitution pressure is fiercest in low-specification water treatment, the largest volume pool, while high-specification niches remain structurally protected—meaning coal-based suppliers should defend margins by moving up the specification curve, not by defending volume.
Kuraray, Cabot Corporation, Osaka Gas Chemicals, Haycarb and Boyce Carbon anchor a moderately concentrated landscape, differentiated by vertical integration, reactivation capacity and iodine-number performance.
| Company | Positioning | Notable strength |
|---|---|---|
| Kuraray Co., Ltd. | Global integrated leader | Expanded virgin and reactivation capacity targeting US PFAS demand |
| Cabot Corporation | Global specialty carbon | Broad product portfolio and technical service depth |
| Osaka Gas Chemicals | High-grade coal and coconut carbon | Quality leadership in high-iodine segments |
| Haycarb PLC | Coconut-shell specialist with coal lines | Sustainability credentials and Asian footprint |
| Boyce Carbon Ltd | Regional coal-based producer | Cost-competitive supply into Indian and Asian markets |
| Chinese basin producers (Inner Mongolia, Shanxi) | Volume commodity PAC | Feedstock cost advantage tied to thermal-coal benchmarks |
Competitive moats are shifting from capacity to service infrastructure. Reactivation networks, take-or-pay contract structures and certified abrasion resistance create switching costs that pure commodity producers cannot replicate. Our analysis suggests the widest moat accrues to suppliers who combine high-iodine virgin product with regional reactivation—precisely the model Kuraray is scaling.
Procurement has become a specification exercise, not a price exercise. Buyers specifying GAC for PFAS compliance must verify iodine number, abrasion resistance (ASTM hardness), apparent density and, critically, sulfur bleed-through characteristics—because a cheaper carbon that leaches sulfur will fail downstream compliance and trigger expensive changeouts. Mission-critical selection criteria now include certified adsorption kinetics under actual load factors, not just virgin isotherm data.
Switching costs are rising. Take-or-pay regeneration contracts lock utilities into multi-year relationships and shift the buy decision from per-kilogram pricing to lifecycle cost per cubic meter treated. Operators should model total cost including transport, reactivation losses (typically 5–10% per cycle) and landfill liability for spent sorbent, rather than comparing virgin carbon quotes in isolation. Regulatory risk is asymmetric: a single PFAS or MATS compliance failure carries penalties far exceeding any unit-price saving.
Supply risk concentrates in feedstock. Non-integrated buyers exposed to thermal-coal price volatility should consider indexed contracts or dual-sourcing across Chinese and Western suppliers. Buyers requiring high-iodine product face a narrower supplier field—Japan and South Korea import this grade rather than produce it domestically, which our analysis reads as a structural quality gap that favors vertically integrated Western suppliers in premium tenders.
The balance of evidence favors a service-led, specification-driven growth strategy over a volume-led one. Regulation is the primary demand engine, and regulation rewards performance guarantees rather than commodity supply. Suppliers who invest in reactivation capacity and certified high-iodine product will capture disproportionate value as utilities convert to take-or-pay models.
The strongest counter-argument is that sustainability substitution could accelerate faster than regulation tightens, particularly if corporate scope-3 reporting standards begin penalizing coal-origin carbon in procurement scoring. That risk is real but concentrated in discretionary, low-specification applications; it does not threaten compliance-driven demand. A secondary risk is gold-recovery substitution toward thiosulfate leaching, which could temper mining demand over a longer horizon.
Actionable strategy:
What would change our conclusion: Evidence that PFAS compliance timelines slip materially, or that scope-3 procurement rules mandate renewable-feedstock carbon in municipal tenders, would shift the balance toward substitution and compress the coal-based outlook below the 4.8% baseline.
While this overview reconciles headline estimates and strategic direction, precise sub-segment forecasting—by iodine grade, activation route and country-level contract structure—requires the full dataset and demand model.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.8% from 2020-2034 |
| Segmentation |
|
The global coal based activated carbon market was valued at approximately USD 4.6 billion in 2025 and is estimated at USD 4.4 billion in 2026, with a competing estimate placing the 2025 figure near USD 3.3 billion on a narrower product-only definition.
Published estimates cluster around a 4.8% to 5.4% CAGR through the early 2030s, with the higher end reflecting stricter PFAS and air-emission compliance and the lower end reflecting sustainability-driven substitution toward coconut-shell carbon.
Asia Pacific dominates with roughly 50% of global revenue, driven by China's coal basin production and India's water infrastructure investment, followed by North America and Europe where regulation-led demand commands higher specification and pricing.
It is primarily used in water and wastewater treatment for PFAS and organic contaminant removal, in air and flue-gas purification for mercury and VOC control, and in food, pharmaceutical and gold-recovery applications requiring high-purity adsorption.
Key players include Kuraray Co., Ltd., Cabot Corporation, Osaka Gas Chemicals, Haycarb PLC and Boyce Carbon Ltd, alongside Chinese basin producers concentrated in Inner Mongolia and Shanxi that compete on feedstock cost.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct industry engagement over published data. We conducted in-depth interviews across the coal based activated carbon value chain, including coal and raw material suppliers, specialized activated carbon producers, regeneration and reactivation service providers, contract formulators, and global distributors. Interviewees were selected at decision-maker level: VP Sourcing and Procurement, Heads of R&D and Technical Directors, Commercial Operations Leads, and Regulatory and Compliance Managers. This mix ensures feedstock economics, technical performance and compliance risk are captured simultaneously.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement | 30% |
| Technical & R&D Directors | 30% |
| Commercial Operations Leads | 25% |
| Regulatory & Compliance Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Coal & Raw Material Suppliers | 30% |
| Specialized Activated Carbon Producers | 35% |
| Regeneration & Service Providers | 20% |
| Global Distributors & Traders | 15% |
Primary findings are triangulated against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and SEC 10-K disclosures, patent databases, and recognized technical standards bodies and industry associations. Regulatory benchmarks include EPA PFAS maximum contaminant levels and MATS air-emission rules, alongside EU BAT conclusions. Where published estimates diverge, we reconcile definitions rather than average them.
We run simultaneous top-down and bottom-up models. The top-down model allocates macroeconomic industrial and municipal spending to activated carbon demand by end-use segment. The bottom-up model builds from manufacturer capacity, product pricing by iodine grade, and end-use consumption modeling, including reactivation substitution effects. Divergence between the two is resolved through segment-level validation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |