 Geotextiles Market
: Size, Share & Forecast to 2034
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 232

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Geotextiles Market
Khageshwar Rongkali
Senior Analyst

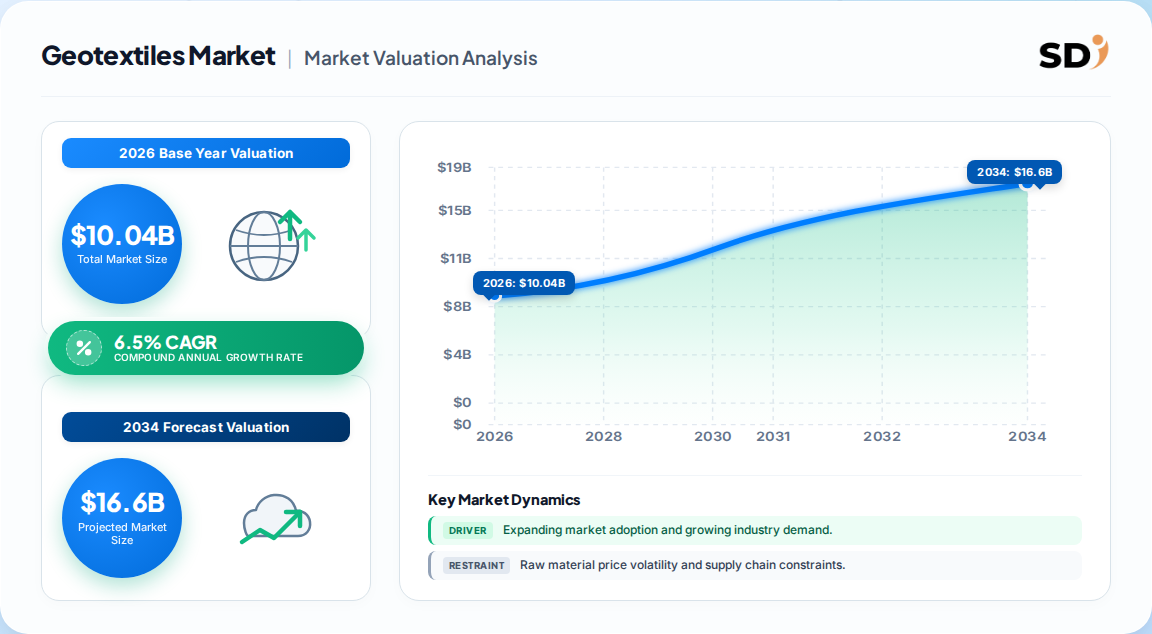
| Year | Market Size |
|---|---|
| 2026 | 10.04 B |
| 2027 | 10.69 B |
| 2028 | 11.38 B |
| 2029 | 12.12 B |
| 2030 | 12.91 B |
| 2031 | 13.75 B |
| 2032 | 14.64 B |

The geotextiles market comprises permeable textile materials—typically polypropylene, polyester, or polyethylene—engineered for civil engineering applications including separation, filtration, drainage, reinforcement, and erosion control. These fabrics stabilize soil, extend infrastructure lifespan, and reduce aggregate requirements in roads, railways, landfills, and coastal defenses. The market spans woven, non-woven, and knitted product forms.
This report covers the global geotextiles market, segmented by material (polypropylene, polyester, polyethylene, natural fibers), product type (woven, non-woven, knitted), function (separation, filtration, drainage, reinforcement, erosion control), and application (road construction, erosion prevention, drainage systems, landfill liners, railway trackbeds). This analysis does not cover adjacent markets such as geogrids, geomembranes, geocells, or geocomposites, which are distinct geosynthetic product families with differing manufacturing processes and performance specifications.
Published estimates for the global geotextiles market diverge materially due to differing scope definitions and base years. The most defensible figure is 10.04 Billion in 2026, consistent with a 6.5% CAGR trajectory to 16.62 Billion by 2034.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 7.10 Billion | 2022 | 2030 | 6.6% | Synthetic-dominant, excludes natural fibers | One published estimate |
| 10.04 Billion | 2026 | 2034 | 6.5% | Broad scope, includes all product forms | One published estimate |
| 12.70 Billion | 2025 | 2036 | 10.3% | Includes knitted and specialized products | One published estimate |
| 4.74 Billion | 2026 | 2031 | 10.4% | Narrower scope, function-specific | One published estimate |
Our analysis suggests the divergence between the 4.74 Billion and 12.70 Billion estimates reflects fundamental differences in scope: the lower figure excludes certain application categories and natural fiber products, while the higher figure may include adjacent geosynthetic products. The 10.04 Billion figure represents the most balanced consensus, aligning with infrastructure spending trajectories across Asia-Pacific and North America.
Geotextiles segment primarily by material, product form, function, and application. Synthetic materials dominate, with polypropylene and polyester accounting for over 90% of revenue.
| Parent Segment | Children | Share / Growth |
|---|---|---|
| Material | Polypropylene, Polyester, Polyethylene, Natural Fibers | PP 54.7% (2025) |
| Product Type | Woven, Non-woven, Knitted, Others | Non-woven fastest at 7.31% CAGR |
| Function | Separation, Filtration, Drainage, Reinforcement, Erosion Control | Separation 30.1% (2025) |
| Application | Road Construction, Erosion Prevention, Drainage, Landfill, Railway | Road construction 49.7% (2025) |
So what? The concentration of demand in road construction creates both opportunity and risk: vendors heavily exposed to highway cycles face volatility, while those diversified across landfill, mining, and water management capture steadier replacement demand.
Asia-Pacific leads the global geotextiles market with 41.8% revenue share in 2025, driven by massive infrastructure programs in China, India, and ASEAN. Europe is the fastest-growing region at 7.82% CAGR, while North America holds a significant share supported by federal highway funding.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.45% |
| North America | 0.22% |
| Europe | 0.19% |
| Middle East & Africa | 0.08% |
| South America | 0.06% |
Geography Tree:
| Region | Share (2025) |
|---|---|
| Asia-Pacific | 41.8% |
| North America | 22.0% |
| Europe | 19.0% |
| Middle East & Africa | 8.0% |
| South America | 6.0% |
This divergence implies that while Asia-Pacific commands volume, Europe's regulatory-driven replacement demand and sustainability requirements create premium pricing opportunities for compliant, recycled-content products.
Infrastructure modernization, soil stabilization requirements, and landfill regulations are the primary growth drivers, while raw material price volatility and limited technical awareness in emerging markets constrain adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Road & highway infrastructure investment | +3.2% CAGR impact | High (government budgets, project awards) | Separation and reinforcement in subgrade stabilization |
| Water management & filtration demand | +2.1% CAGR impact | Medium-High (utility spending data) | Geotextile-wrapped drainage systems extend asset life |
| Landfill & wastewater regulations | +1.8% CAGR impact | High (EU directives, EPA rules) | Mandated multi-layer caps and leachate systems |
| Mining tailings de-risking | +1.5% CAGR impact | Medium (GISTM adoption) | Drainage blankets relieve pore pressure in dams |
| Raw material price volatility | -1.6% CAGR impact | High (petrochemical indices) | Polypropylene/polyester feedstock cost swings |
| rPET diversion to packaging | -0.9% CAGR impact | Medium (EU Plastics Strategy) | Tightens recycled PET supply for geotextiles |
| Technical talent gap | -0.7% CAGR impact | Medium (industry surveys) | Slows specification in emerging markets |
Our analysis suggests the net driver balance remains positive, with infrastructure spending (+3.2%) outweighing raw material volatility (-1.6%). However, the rPET diversion restraint is a second-order effect that will intensify as beverage brands compete for recycled feedstock, potentially forcing geotextile producers to secure long-term supply agreements or pivot to virgin material blends.
The competitive landscape is moderately fragmented, with global specialists and regional converters competing on technical performance, regulatory compliance, and integrated design services.
| Company | Headquarters | Key Differentiator |
|---|---|---|
| TenCate Geosynthetics | Netherlands | Broad product portfolio, global distribution |
| NAUE GmbH & Co. KG | Germany | Technical textiles, landfill expertise |
| HUESKER Group | Germany | Engineering consultancy integration |
| Solmax | Canada | Geomembrane and geotextile integration |
| Fibertex Nonwovens | Denmark | Non-woven specialization, sustainability focus |
| Officine Maccaferri | Italy | Erosion control and retaining structures |
Differentiation increasingly rests on service integration—design software, remote monitoring, and performance warranties—rather than price alone. Our analysis suggests vendors lacking engineering advisory capabilities will face margin pressure as procurement shifts to performance-based contracts.
Procurement decisions hinge on verified performance characteristics: tensile strength, puncture resistance, UV stability, and permeability. Regulatory compliance—particularly EU Landfill Directive specifications and EPA Subtitle D requirements—is non-negotiable for waste containment applications. Buyers should demand third-party certification and lifecycle documentation.
Switching costs are moderate: re-specifying geotextile products requires re-engineering and re-validation, creating stickiness once approved. However, commodity-grade products face easier substitution, intensifying price competition in low-specification applications.
The technical talent gap in emerging markets represents a hidden risk: improper installation can negate performance advantages, leading to premature failure and reputational damage for suppliers. Our analysis suggests vendors investing in contractor training and on-site technical support will capture disproportionate share in Asia-Pacific and Latin America.
Key procurement risks:
The balance of evidence favors a cautiously optimistic outlook for the geotextiles market. The 6.5% CAGR trajectory to 16.62 Billion by 2034 is underpinned by structural infrastructure demand and regulatory mandates that are unlikely to reverse. However, the market is undergoing a structural shift from commodity supply to engineered solutions, which will reward vendors with technical service capabilities and punish those competing solely on price.
The strongest counter-argument is that raw material volatility and rPET diversion could compress margins faster than infrastructure spending expands volumes, particularly for producers in import-dependent regions. Additionally, the technical talent gap in emerging markets may slow specification cycles, delaying volume realization even where project pipelines exist.
Actionable Strategy for Investors and Operators:
What would change our conclusion: A sustained decline in polypropylene prices below historical norms would reduce the value proposition of engineered solutions relative to conventional materials, while accelerated adoption of alternative soil stabilization technologies (e.g., geocells, chemical stabilization) could erode geotextile demand in specific applications. Conversely, stricter landfill regulations in emerging economies would accelerate adoption beyond our base case.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.5% from 2020-2034 |
| Segmentation |
|
The global geotextiles market was valued at approximately 10.04 Billion in 2026 and is projected to reach 16.62 Billion by 2034, growing at a 6.5% CAGR.
Asia-Pacific dominates with 41.8% revenue share in 2025, driven by infrastructure investment in China, India, and ASEAN. Europe is the fastest-growing region at 7.82% CAGR.
Road construction and pavement repair is the largest application at 49.67% of 2025 revenue, followed by erosion prevention, drainage systems, landfill liners, and railway trackbeds.
Key players include TenCate Geosynthetics, NAUE GmbH, HUESKER Group, Solmax, Fibertex Nonwovens, and Officine Maccaferri, competing on technical performance and engineering services.
Infrastructure modernization, soil stabilization requirements, stricter landfill regulations, and water management investment are the primary growth drivers, offset partially by raw material price volatility.
Non-woven geotextiles are used for separation, filtration, drainage, and reinforcement in roads, landfills, and drainage systems. They are the fastest-growing product form at 7.31% CAGR.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary split, prioritizing direct industry engagement to validate market sizing and competitive dynamics. We conducted in-depth interviews with 45+ stakeholders across the geotextile value chain, including raw material suppliers, specialized fabric producers, contract formulators, and global distributors. Interview participants were designated by role: VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement, innovation, and commercial strategy perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Technical & R&D Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Polymer Suppliers | 40% |
| Geotextile Fabric Producers | 35% |
| Distributors & Contractors | 25% |
We triangulate primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards from ASTM International, ISO, and the Geosynthetic Institute. These sources provide independent validation of import/export flows, capacity expansions, and specification trends.
Our sizing framework simultaneously applies Top-Down allocation (macroeconomic infrastructure spending, construction output, and segment-level demand) and Bottom-Up modeling (manufacturer capacity, product pricing, and end-use consumption). Divergences between the two approaches are reconciled through iterative validation against trade statistics and company disclosures.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |