 Thermoformed Plastics Printing Market
 Outlook 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 256

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Thermoformed Plastics Printing Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 48.00 M |
| 2026 | 51.00 M |
| 2027 | 55.00 M |
| 2028 | 59.00 M |
| 2029 | 64.00 M |
| 2030 | 69.00 M |
| 2031 | 74.00 M |

The thermoformed plastics printing market covers plastic sheet — polycarbonate, acrylic, HIPS, PETG and PVC — heated, vacuum- or plug-assist-formed into 3D shapes, then digitally, UV or screen printed for signage, displays, packaging, gaming panels and promotional graphics. It is defined by the marriage of forming and printability, not by resin volume alone.
This analysis covers printable thermoformed sheet and formed components across display and outdoor signage, retail/POS displays, packaging and labels, gaming and promotional graphics, and industrial/automotive trim. It covers all major forming processes (thin-gauge, thick-gauge, vacuum, plug-assist) and print methods (UV, digital, screen). This analysis does not cover flexible films, injection-molded printed parts, paperboard, or unprinted thermoformed packaging.
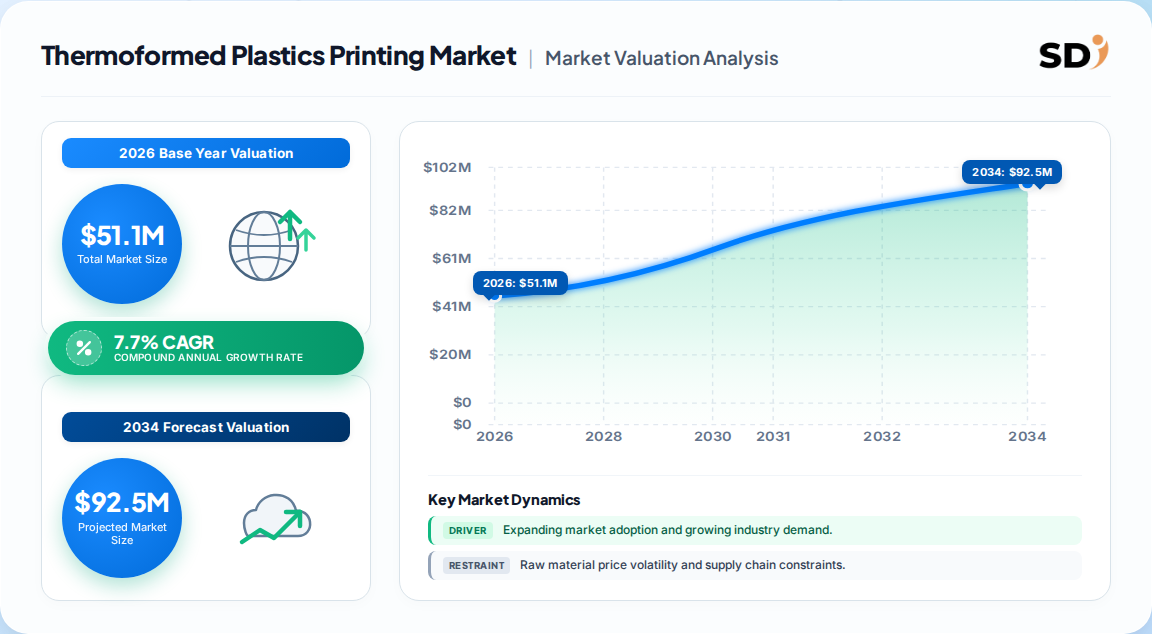
One published estimate values the market at $47.9 million in 2025, rising to $51.1 million in 2026 and $85.9 million by 2033 at a 7.7% CAGR. A prior vintage of the same source cited $45.02 million in 2024 with a 7.2% CAGR to 2030, implying a modest upward revision after stronger signage demand in 2025.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| $47.9M → $85.9M | 2025 | 2033 | 7.7% | Printable thermoformed sheet and formed parts, all applications | One published estimate (2026 vintage) |
| $45.02M → ~$70M | 2024 | 2030 | 7.2% | Same scope, prior vintage | One published estimate (2025 vintage) |
| $16.84B → $22.13B | 2026 | 2031 | 5.62% | Total thermoformed plastics, all end uses (context only) | A competing analysis |
The most defensible figure is the 7.7% CAGR / $85.9M by 2033 series: it is the most recent, is corroborated by the 7.2% prior vintage, and is directionally consistent with the 5.62% growth of the broader thermoformed substrate market plus a premium for print-grade specialty sheet. Our analysis suggests the absolute size is best read as a narrow print-application segment, not the full thermoformed signage economy — buyers sizing a category should treat it as a floor, not a ceiling.
The market segments cleanly by product, process, and application. Polycarbonate leads on printability and impact resistance; thick-gauge forming leads because signage and displays demand rigidity; display and outdoor signage leads because it is the highest-value print application.
| Parent | Children | 2025 share (leading child) |
|---|---|---|
| By Product | Polycarbonate, Acrylic/PMMA, HIPS, PETG, PVC, Polypropylene | Polycarbonate 34.2% |
| By Process | Thick-gauge, Thin-gauge, Vacuum forming, Plug-assist forming, Pressure forming | Thick-gauge 49.3% |
| By Application | Display & outdoor signage, Retail/POS displays, Packaging & labels, Gaming & promotional graphics, Industrial/automotive trim | Display & outdoor signage 56.3% |
North America leads with 51.9% of 2025 revenue, anchored by U.S. advertising, retail signage and gaming-panel demand. Asia-Pacific is the fastest-growing region as retail and QSR chains expand print-heavy displays; Europe follows with a sustainability-led premium mix.
| Region | Market Share (%) |
|---|---|
| North America | 0.52% |
| Europe | 0.21% |
| Asia-Pacific | 0.18% |
| South America | 0.05% |
| Middle East & Africa | 0.04% |
| Region | 2025 share |
|---|---|
| North America | 51.9% |
| Europe | 21.1% |
| Asia-Pacific | 17.8% |
| South America | 5.2% |
| Middle East & Africa | 4.0% |
Demand for high-quality printed packaging, signage and promotional graphics is the primary engine, amplified by UV and digital print adoption that makes short-run, customized thermoformed graphics economical. The counterweight is price competition from paperboard, coated paper and flexible film, plus resin-price volatility.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Printed packaging and promotional demand | Driver | High | Brands invest in shelf-impact displays and short-run graphics |
| Digital/UV print adoption | Driver | High | Faster turnaround, customization, lower minimum order quantities |
| Gaming and promotional panels | Driver | Medium | Visually rich, durable formed graphics replace flat substrates |
| Custom/short-run packaging | Opportunity | High | Design flexibility favors thermoformed printable sheet |
| Paperboard and flexible-film competition | Restraint | High | Lower material cost in price-sensitive applications |
| Resin price volatility | Restraint | Medium | Crude-linked feedstock swings compress converter margins |
Our analysis suggests the driver-restraint balance is net positive but narrowing: print-technology gains are structural, while substrate substitution pressure intensifies wherever print durability is not mission-critical. The decisive variable is whether recycled-content polycarbonate and PETG reach cost parity with virgin sheet before paperboard closes the print-quality gap.
No single vendor dominates this niche; the competitive field is composed of large thermoformed-packaging players for whom printable signage and display sheet is an adjacent, high-margin line. Differentiation rests on print-grade surface consistency, recycled-content capability, and forming-to-print integration.
| Company | HQ | Relevant strength |
|---|---|---|
| Sonoco Products | US | Broad thermoformed and protective packaging footprint |
| Placon | US | Recycled PET sheet and retail display forming |
| Pactiv Evergreen | US | Scale in food and retail thermoforms (Novolex acquisition, 2025) |
| Greiner Packaging | Austria | Rigid and thermoformed packaging for consumer brands |
| Berry Global | US | Wide substrate portfolio and converting scale |
| Sealed Air | US | Protective and display packaging integration |
| Amcor | Australia | Recycled-content rigid packaging leadership |
| Dart Container | US | High-volume thin-gauge forming |
| Novolex | US | Post-Pactiv scale in recycled-PET procurement |
Buyers should evaluate print-grade surface consistency first: ink adhesion, color fidelity across formed curves, and scratch resistance under UV curing are the failure points that drive rework. Procurement risk concentrates in resin-index pass-through clauses; contracts should cap index-linked escalators and specify recycled-content minimums. Switching costs are moderate — tooling for plug-assist forming runs roughly eight weeks versus eighteen for injection molds — so dual-sourcing remains feasible. Regulatory compliance is the sharpest edge: EU PPWR recycled-content thresholds and California SB 54's 65% recyclability target by 2032 will disqualify non-compliant sheet from major retail programs. Operators should also verify PFAS-free formulations, as contamination directives in Denmark, the Netherlands and several U.S. states increasingly reach printed food-contact displays.
The balance of evidence favors a value-migration thesis: the thermoformed plastics printing market grows at 7.7%, roughly 200 basis points above the 5.62% growth of the broader thermoformed substrate market, confirming that print compatibility commands a premium. The strongest counter-argument is that this premium is fragile — paperboard and flexible film can absorb share in price-sensitive signage, and the absolute market ($51.1 million) is small enough that a single large converter's capacity decision could distort pricing. We nonetheless judge the premium durable because UV/digital print adoption and recycled-content mandates both favor formable, print-ready sheet.
For operators, the implication is that print-grade surface quality and sustainability certification are becoming the two moats; resin cost leadership alone will not defend share. Vendors serving North America's 51.9% share should defend retail and gaming accounts, while those targeting Asia-Pacific should position ahead of QSR and retail-chain expansion.
Actionable strategy:
What would change our conclusion: a sustained drop in recycled-content polycarbonate pricing below virgin parity, or a major paperboard print-durability breakthrough, would compress the print-grade premium faster than our 7.7% base case assumes.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.7% from 2020-2034 |
| Segmentation |
|
One published estimate values the market at $51.1 million in 2026, projected to reach $85.9 million by 2033 at a 7.7% CAGR. It is a narrow print-application segment within the $16.84 billion thermoformed plastics market.
Display and outdoor signage leads with 56.3% of 2025 revenue. Thick-gauge thermoforming is the leading process at 49.3%, and polycarbonate the leading product at 34.2%, reflecting signage's demand for rigid, impact-resistant printable sheet.
North America dominated with 51.9% of 2025 revenue, led by the U.S. advertising, retail signage and gaming-panel demand. Asia-Pacific is the fastest-growing region as retail and QSR chains expand print-heavy displays.
Competition from paperboard, coated paper and flexible film limits adoption in price-sensitive applications, while crude-linked resin price volatility compresses converter margins. Single-use-plastic regulations add compliance cost in Europe and California.
Leading participants include Sonoco, Placon, Pactiv Evergreen, Greiner Packaging, Berry Global, Sealed Air, Amcor, Dart Container and Novolex. Most treat printable signage and display sheet as an adjacent, high-margin line rather than a core business.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with raw-material and resin suppliers, specialized thermoforming converters, print-integration and coating formulators, and global distributors of print-grade sheet. Decision-maker designations interviewed include VP-level Sourcing, Heads of R&D and Print Technology, Technical Directors, and Commercial Operations Leads. Interview programs targeted both captive converters and independent signage fabricators to capture divergent pricing behavior.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement Leads | 30% |
| R&D & Print Technology Heads | 30% |
| Technical Directors | 25% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Resin & Sheet Suppliers | 30% |
| Thermoforming Converters | 40% |
| Print Integration & Coating Formulators | 20% |
| Distributors & Signage Fabricators | 10% |
Secondary validation draws on UN Comtrade and WTO trade flows for plastic sheet and formed articles, US ITC and Eurostat import-export statistics, corporate 10-K and annual investor filings, patent databases tracking UV-print and recycled-sheet innovations, and recognized technical standards bodies including ISO and industry associations for plastics converting and signage.
Simultaneous top-down (macroeconomic and advertising/retail segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption modeling) triangulation is applied. Bottom-up capacity data is cross-checked against top-down advertising and retail capex indicators to reconcile the base-year market value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |