 Us Pre Engineered Metal Building Market
US Pre Engineered Metal Building Market 2026 Outlook
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 197

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Pre Engineered Metal Building Market
Khageshwar Rongkali
Senior Analyst

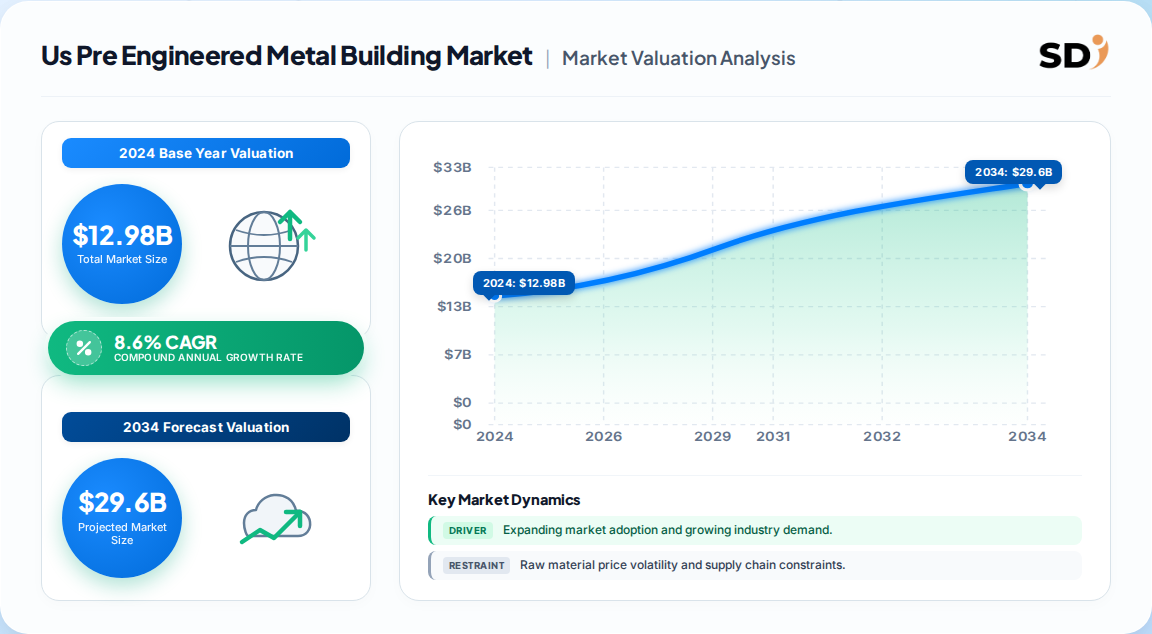
| Year | Market Size |
|---|---|
| 2024 | 12.98 B |
| 2025 | 14.10 B |
| 2026 | 15.31 B |
| 2027 | 16.63 B |
| 2028 | 18.06 B |
| 2029 | 19.61 B |
| 2030 | 21.30 B |

The U.S. pre-engineered metal building market comprises factory-fabricated structural steel systems—primary and secondary framing, roof and wall panels, and accessories—engineered for rapid on-site assembly. It serves commercial, industrial, agricultural, and institutional construction, delivering cost, speed, and design flexibility versus conventional stick-built structures.
This report covers U.S. demand for pre-engineered metal building systems across eight application segments: office, warehouse, healthcare, education, recreational, manufacturing, agriculture, and lodging & restaurants. It spans structural framing, insulated and uninsulated wall/roof systems, and accessory components. This analysis does not cover conventional structural steel fabrication, modular volumetric construction, or non-steel prefabricated building systems.
Two credible published estimates place the U.S. market between USD 12.98 billion and USD 13.1 billion for 2024, with a long-range projection to USD 27.10 billion by 2033 at an 8.6% CAGR.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 12.98 billion | 2024 | 2033 | 8.6% | Pre-engineered metal building systems, U.S. only | One published market estimate |
| USD 13.1 billion | 2024 | 2030 | Not stated | Prefab metal building manufacturing, NAICS 332311, U.S. | Industry census benchmark |
| USD 40.56 billion (global) | 2024 | 2035 | 4.62% | Global pre-engineered metal buildings, all regions | A competing analysis |
Our analysis suggests the USD 12.98 billion figure is the most defensible U.S. baseline because it aligns closely with the independent NAICS 332311 manufacturing census, which captures producer-level revenue rather than installed project value. The global estimate implies a U.S. share of roughly 30–32%, consistent with North America's position as the largest regional market.
Segmentation follows application demand, with manufacturing dominating revenue and commercial applications rising fastest as design versatility improves.
| Parent segment | Children |
|---|---|
| Application | Office, Warehouse, Healthcare, Education, Recreational, Manufacturing, Agriculture, Lodging & Restaurants |
| Building type | Industrial, Commercial, Institutional, Residential |
| Roof type | Single slope, Multiple slopes, Curved, Custom |
| Wall type | Insulated metal panels, Sandwich panels, Tilt-up panels |
Manufacturing's 34.0% share reflects the need for wide spans, high clear heights, and heavy load-bearing capacity. Agriculture is the second-fastest application at 8.8% CAGR, driven by controlled-environment and cold-storage construction.
Texas leads U.S. demand with a 15.6% revenue share in 2024, while Arkansas is the fastest-growing state market, reflecting industrial migration into the South and West.
| Region | Market Share (%) |
|---|---|
| South | 0.34% |
| West | 0.26% |
| Midwest | 0.22% |
| Northeast | 0.18% |
Economic development incentives, lower land costs, and logistics proximity are pulling warehouse and manufacturing investment into Sun Belt states. Our analysis suggests the South will sustain above-market growth as nearshoring accelerates along the Texas–Mexico corridor and e-commerce fulfillment networks densify.
Growth is driven by cost efficiency, off-site construction adoption, sustainability requirements, and warehousing demand; it is restrained by transport risk and steel tariff exposure.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Cost efficiency | Driver | Strong | Up to 30% lower cost than conventional structures |
| Sustainability mandates | Driver | Strong | Recyclable steel, energy-efficient envelopes |
| E-commerce warehousing | Driver | Strong | Fulfillment and cold-storage capacity buildout |
| Off-site construction adoption | Driver | Moderate | Faster erection, reduced site labor |
| Transportation damage risk | Restraint | Moderate | Module deformation raises repair/replacement costs |
| Steel tariffs | Restraint | Strong | Est. USD 640 million cost impact on manufacturers |
The balance of evidence favors growth. Manufacturing reshoring and warehouse demand are structural, multi-year catalysts, while tariff and transport risks are manageable through supply-chain engineering. Still, steel price volatility could compress fabricator margins if contracts lack escalation clauses.
The market is fragmented and includes national building-system manufacturers with vertically integrated design, engineering, and fabrication capabilities.
| Company | Positioning | Differentiator |
|---|---|---|
| Nucor Corporation | National steel and building systems | Vertically integrated steel supply |
| BlueScope Steel | Global coated steel and buildings | Coated steel and panel technology |
| Butler Manufacturing | Engineered building systems | Brand heritage and engineering depth |
| American Buildings Company | Commercial and industrial systems | Broad product portfolio |
| General Steel Corporation | Custom steel buildings | Direct-to-buyer custom design |
| MBCI | Metal roof and wall systems | Envelope and panel specialization |
Competitive moats rest on engineering optimization, integrated design systems that balance standardization with customization, and installation support networks. Our analysis suggests vertical steel integration is the strongest structural advantage in a tariff-exposed input environment.
Buyers should prioritize engineering certification, wind and snow load compliance, and envelope energy performance when selecting a pre-engineered system. Procurement risk concentrates in transportation: damaged modules can trigger significant replacement costs and schedule delays, so contract terms should allocate freight risk explicitly.
Switching costs between manufacturers are moderate because systems are largely non-proprietary, but anchor-bolt layouts, panel profiles, and warranty terms create lock-in at the component level. Regulatory compliance with local building codes, fire ratings, and energy standards must be validated early. Buyers should also confirm tariff exposure pass-through clauses and steel escalation terms before signing.
The balance of evidence favors a constructive outlook: an 8.6% CAGR through 2033 is credible given manufacturing reshoring, warehouse buildout, and sustainability tailwinds. The strongest counter-argument is tariff-driven steel cost inflation, which could compress margins and delay projects if fabricators cannot pass costs through.
Our analysis suggests the market's center of gravity is shifting toward the South and toward manufacturing applications. Vendors with transport-optimized modular designs and tariff-hedged supply will outperform. The full report provides state-level forecasts and sub-segment modeling needed for precise capital allocation.
Actionable strategy:
Evidence that would change this conclusion: sustained steel price declines combined with accelerated reshoring incentives would push growth above 10%; conversely, prolonged tariff escalation and freight disruption would warrant a downward revision.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.6% from 2020-2034 |
| Segmentation |
|
The U.S. market was estimated at USD 12.98 billion in 2024 and is projected to reach USD 27.10 billion by 2033, growing at an 8.6% CAGR over the 2025–2033 forecast period.
Manufacturing accounted for the largest revenue share at 34.0% in 2024 and is also the fastest-growing application, with a projected 9.6% CAGR through 2033.
Texas dominated with a 15.6% revenue share in 2024, while Arkansas is the fastest-growing state market, reflecting industrial migration into the South and West.
Transportation damage to prefabricated modules and steel tariff exposure—estimated at USD 640 million in cost impact—are the principal restraints on U.S. market expansion.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applied a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including steel and coil suppliers, specialized building-system fabricators, panel and envelope producers, engineering and erection contractors, and regional distributors. Decision-maker designations interviewed included VP of Procurement, Head of Engineering, Technical Directors, and Commercial Operations Leads, ensuring coverage of both supply-side capacity and demand-side specification behavior.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Procurement & Sourcing | 35% |
| Heads of Engineering | 30% |
| Technical Directors | 22% |
| Commercial Operations Leads | 13% |
| Company Type | Representation (%) |
|---|---|
| Steel & Coil Suppliers | 30% |
| Building-System Fabricators | 40% |
| Panel & Envelope Producers | 18% |
| Distributors & Erectors | 12% |
Secondary validation drew on official multilateral trade databases (UN Comtrade, US ITC), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies and industry associations relevant to steel building systems and construction codes.
Market sizing triangulated a top-down macroeconomic and industry-segment allocation against a bottom-up model of manufacturer capacity, product pricing, and end-use consumption. Forecasts applied historical CAGR, regression analysis, and demand elasticity to reconcile the two approaches.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | State-level share breakdown | Trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |