 Us Enzymes Market
US Enzymes Market Size, Share & Forecast to 2030
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 211

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Enzymes Market
Khageshwar Rongkali
Senior Analyst

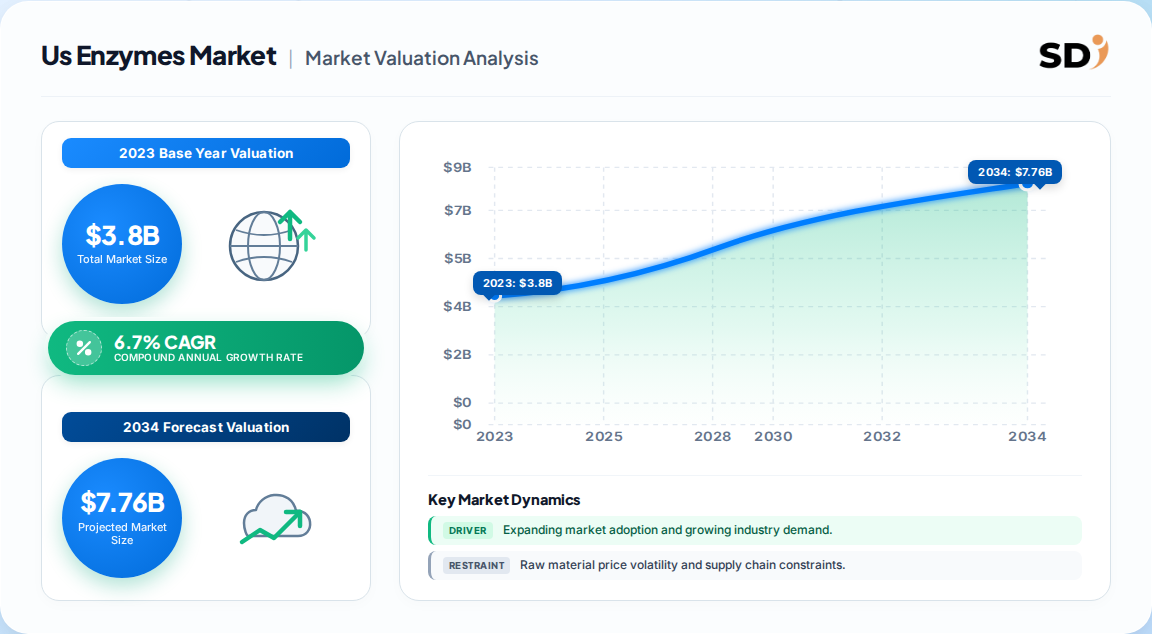
| Year | Market Size |
|---|---|
| 2023 | 3.800 B |
| 2024 | 4.050 B |
| 2025 | 4.330 B |
| 2026 | 4.620 B |
| 2027 | 4.930 B |
| 2028 | 5.260 B |
| 2029 | 5.610 B |

The U.S. enzymes market comprises the commercial production and sale of biological catalysts—largely microbial carbohydrases, proteases, and lipases—used across food and beverage processing, animal feed, biofuels, detergents, textiles, pharmaceuticals, and diagnostics within the United States. It spans both high-volume industrial grades and high-specificity specialty grades sold to regulated end-use sectors.
This report covers U.S. revenue for industrial and specialty enzymes by product, type, source, and end-use application, with 2023 as the base year and forecasts through 2030. It addresses formulated enzyme products sold to food and beverage, animal feed, biofuel, detergent, textile, pulp and paper, pharmaceutical, diagnostic, and wastewater treatment customers.
This analysis does not cover enzyme-based finished consumer products (such as dietary supplements sold at retail), recombinant therapeutic proteins, fermentation equipment, or industrial biocatalysts outside the enzyme classification. Adjacent markets such as specialty chemicals, probiotics, and contract fermentation services are referenced only as context.
One widely cited industry estimate places the U.S. enzymes market at USD 3.80 billion in 2023, growing at 6.7% CAGR through 2030. A competing global benchmark implies a broader USD 14.38 billion worldwide enzyme market in 2025 at 6.8% CAGR, which, applied to the U.S. share, is directionally consistent.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 3.80 Billion | 2023 | 2030 | 6.7% | U.S. enzyme revenue, all product and type segments | One published U.S.-focused industry estimate |
| USD 14.38 Billion (global) | 2025 | 2035 | 6.8% | Global commercial and industrial enzyme formulations | A competing global market analysis |
| USD 2.1 Billion (technical enzymes, global) | 2025 | 2035 | 4.6% | Technical/industrial enzyme segments only | A separate technical-enzyme benchmark |
The U.S.-specific figure is the most defensible anchor for domestic planning because it isolates the geography buyers actually procure in. The global benchmarks are useful for cross-checking growth direction but dilute U.S. biofuel and biopharma intensity. Our analysis suggests the 6.7% CAGR is conservative if cellulosic ethanol capacity and specialty pharma enzyme demand accelerate; the technical-enzyme 4.6% figure reflects a narrower, slower industrial-only basket and should not be substituted for the total market.
Segmentation follows four non-geographic axes: product chemistry, enzyme type, biological source, and end-use application. Product and source concentration are the most commercially consequential for procurement planning, while type and application drive margin structure and regulatory pathway.
| Parent segment | Children | 2023 share signal |
|---|---|---|
| By Product | Carbohydrase, Proteases, Lipases, Polymerases & Nucleases, Others | Carbohydrase 43.7% |
| By Type | Industrial, Specialty | Industrial 54% |
| By Source | Microorganisms, Animals, Plants | Microorganisms 80.4% |
| By Application | Food & Beverages, Animal Feed, Biofuels, Detergents, Textiles, Pulp & Paper, Pharmaceuticals & Diagnostics, Wastewater Treatment | Biofuel and food lead industrial demand |
Analytical read: The dominance of carbohydrase and microbial sourcing means buyer risk is concentrated in a narrow fermentation and strain-engineering supply base. Specialty enzymes, though smaller today, carry higher per-unit value and faster growth, making them the segment where differentiation and pricing power will be won.
No public source in the reference set reports a verified state- or census-region-level enzyme revenue split, so a definitive regional share table cannot be responsibly constructed. Geography is therefore best read through the demand footprint of the end-use sectors that consume enzymes rather than through supplier headquarters.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.24% |
| Midwest | 0.22% |
| South | 0.34% |
| West | 0.2% |
Our analysis suggests the Midwest's ethanol-linked carbohydrase demand is the single largest geographic pull, but it is also the most policy-sensitive. Buyers with Midwest biofuel exposure should hedge against Renewable Fuel Standard adjustments, while Northeast specialty buyers should prioritize vendor qualification depth over unit price.
Growth is being pulled by biofuel throughput, food-system industrialization, and specialty biopharma manufacturing, while supply concentration and regulatory fragmentation cap the pace of expansion.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Biofuel and bioethanol processing | Driver | High — U.S. capacity near 18.5B gal/yr across 191 plants | Amylase and cellulase volumes scale directly with ethanol throughput |
| Food & beverage industrialization | Driver | High — convenience food and dairy/bakery demand | Enzymes improve texture, shelf life, and processing yield |
| Specialty pharma and diagnostics | Driver | Moderate — specialty growing faster than industrial | High-specificity enzymes for drug synthesis and diagnostics |
| AI-guided protein engineering | Driver | Moderate — directed evolution plus ML screening | Widens addressable applications and temperature/pH tolerance |
| Geographic supply concentration | Restraint | High — Denmark alone exported USD 1.79B of HS 3507 in 2024 | Import-dependent buyers face procurement risk and longer cycles |
| Regulatory fragmentation | Restraint | Moderate — GRAS, EU Positive List, China frameworks | Delayed market entry; favors larger incumbents |
The balance of evidence favors continued 6–7% expansion over the forecast window. Biofuel demand is quasi-structural: ethanol producers buy enzymes as operating inputs, not discretionary additives, which creates repeat procurement cycles even in soft economic years. The credible counter-argument is that biofuel policy reform or ethanol capacity stagnation would remove the largest single demand pillar, and that cross-border trade growth lagging market growth (4.9% trade growth in 2024) signals localization that could strand export-oriented capacity.
The U.S. enzyme market is moderately concentrated, with Novonesis, IFF/Danisco, and DSM controlling the largest positions, followed by BASF and Kerry, while advanced enzyme specialists and distributors fill specialty and regional niches.
| Company | Strategic position | Primary moat |
|---|---|---|
| Novonesis (Novozymes) | Global leader, ~19% of global enzyme revenue | Fermentation scale, strain library, biofuel relationships |
| IFF / Danisco | Top-5 global player | Food enzyme portfolio and application expertise |
| DSM | Top-5 global player | Industrial and specialty breadth, pharma-grade capability |
| BASF | Top-5 global player | Chemical-enzyme integration and global distribution |
| Kerry Group | Top-5 global player | Food and beverage application integration |
| Advanced Enzyme Technologies | Specialist challenger | Niche specialty and nutraceutical enzyme focus |
Differentiation rests on three moats: fermentation capacity and yield economics, proprietary engineered strains with regulatory dossiers, and application-level technical service at plant scale. Small producers can compete on technical performance but frequently lose on qualification timelines and multi-jurisdictional authorization burden. Our analysis suggests consolidation pressure will intensify in specialty grades, where dossier investment is highest relative to revenue.
Enzyme procurement is not a commodity purchase. Buyers should evaluate suppliers on activity consistency, lot-to-lot variability, and technical service depth before unit price, because a failed enzyme batch can halt an entire production line. Qualification cycles for new suppliers in food and pharma applications typically run months and require toxicology and application data, which creates meaningful switching costs.
Regulatory compliance is mission-critical and jurisdiction-specific. In the U.S., enzymes are regulated as direct or secondary direct additives or GRAS under CFR 21 depending on use; in the EU the Positive List framework is targeting finalization by 2028; China maintains a parallel framework. Products approved for one end-use are not automatically portable to another.
Supply risk deserves board-level attention. With Denmark alone accounting for USD 1.79 billion of global enzyme exports in 2024, U.S. buyers of specialized grades face concentrated single-source exposure. Dual-sourcing is expensive because it requires duplicate validation, but for mission-critical biofuel or pharma enzyme lines it is increasingly justified. The gap: precise sub-segment price forecasting and vendor capacity data require the full report's bottom-up modeling.
The balance of evidence favors a constructive view on the U.S. enzymes market through 2030: a 6.7% CAGR is well supported by biofuel throughput, food processing demand, and fast-growing specialty applications, and the market's 29% share of global revenue gives it structural gravity. The strongest counter-argument is policy and supply concentration risk—biofuel mandate changes and single-region fermentation dependence could both compress growth below trend. Neither, in our judgment, is sufficient to overturn the base case, but both justify a hedging posture.
On competition, we expect moats to widen around regulatory dossiers and application technical service rather than around raw fermentation scale. Specialty enzyme growth outpaces industrial precisely where qualification burden is highest, which structurally advantages Novonesis, IFF, DSM, and BASF and constrains challenger share gains. Distributors will retain value in fragmented mid-market food and textile accounts but face margin pressure where suppliers move direct.
Actionable strategy:
The evidence that would change this conclusion: a material reduction in U.S. fuel ethanol capacity, a faster-than-expected EU Positive List finalization that fragments U.S.–EU formulation portability, or a step-change in AI enzyme engineering that lowers entry barriers for challengers. Absent these, the 6.7% trajectory holds and the strategic premium sits with differentiated, compliance-ready suppliers.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.7% from 2020-2034 |
| Segmentation |
|
The U.S. enzymes market was estimated at USD 3.80 billion in 2023 and is forecast to grow at a 6.7% CAGR to 2030, reaching roughly USD 5.95 billion. It represents about 29% of global enzyme revenue.
Industrial enzymes held a 54% revenue share in 2023, led by carbohydrase at 43.7% of product revenue and microorganism-sourced enzymes at 80.4% of source revenue. Specialty enzymes are growing faster.
Biofuel and bioethanol processing, food and beverage industrialization, animal feed, and specialty pharmaceutical and diagnostic applications are the primary growth drivers. Protein engineering is widening the addressable application set.
Novonesis (Novozymes), IFF/Danisco, DSM, BASF, and Kerry Group lead the market, with Novonesis holding roughly 19% of global enzyme revenue. The top five players collectively hold around 40% global share.
Geographic supply concentration, particularly Denmark's dominance in enzyme exports, plus fragmented U.S., EU, and China regulatory pathways create procurement and qualification risk. Buyers should dual-source mission-critical grades.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the enzyme value chain, including raw material and fermentation input suppliers, specialized enzyme producers, contract formulators and blenders, and global distributors serving U.S. end markets. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring both technical and commercial validity.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory Affairs Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Enzyme Producers & Fermentation Operators | 45% |
| Contract Formulators & Blenders | 30% |
| Industrial Distributors & Traders | 25% |
Secondary benchmarking draws on official multilateral trade and standards databases, including UN Comtrade (HS 3507 enzyme trade flows), WTO tariff data, U.S. International Trade Commission filings, and Eurostat. Corporate annual filings, 10-K statements, investor presentations, patent databases, and recognized non-profit technical standards and industry associations were reviewed to validate capacity, revenue, and innovation signals.
Market sizing triangulates Top-Down allocation from macroeconomic and industrial segment output against Bottom-Up manufacturer capacity, product pricing, and end-use consumption modeling. Biofuel throughput, food processing volumes, and pharma manufacturing activity serve as demand anchors, with regression-based elasticity applied across the forecast horizon.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |