 Musk Aroma Chemicals Market
 Size, Share & 2035 Forecast
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 258

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Musk Aroma Chemicals Market
Khageshwar Rongkali
Senior Analyst

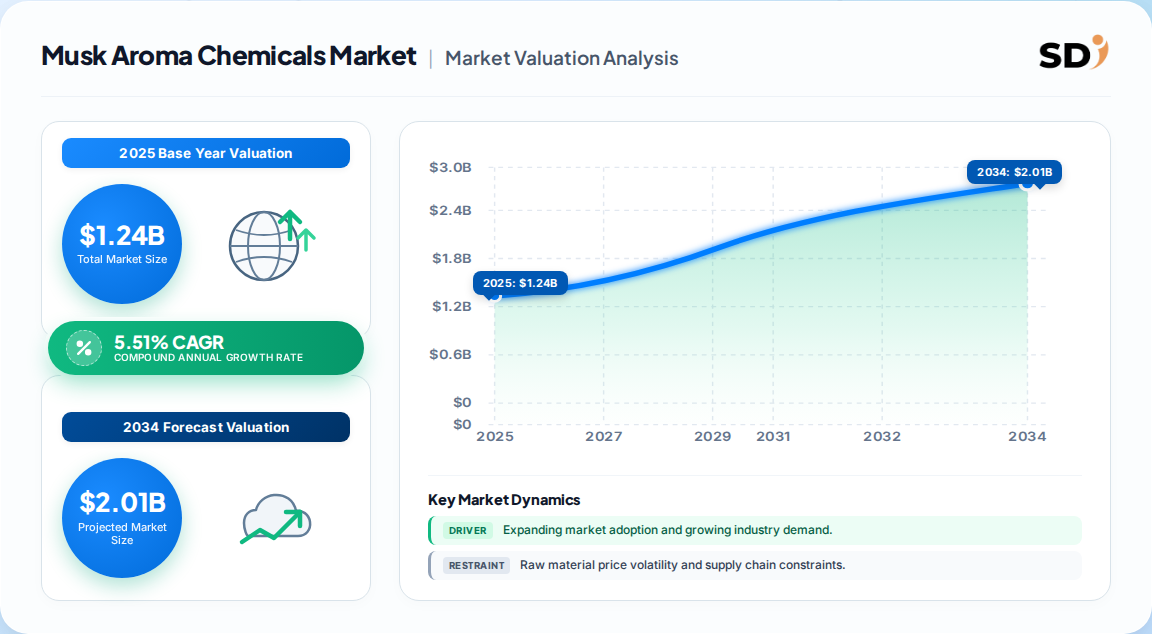
| Year | Market Size |
|---|---|
| 2025 | 1.240 B |
| 2026 | 1.310 B |
| 2027 | 1.380 B |
| 2028 | 1.460 B |
| 2029 | 1.540 B |
| 2030 | 1.630 B |
| 2031 | 1.720 B |

Musk aroma chemicals are high-value fragrance ingredients used as long-lasting base notes and fixatives in perfumes, cosmetics, soaps, detergents, and household products. The industry has shifted decisively from animal-derived musk toward synthetic and biotechnology-based molecules that replicate musky scent profiles while meeting ethical, safety, and sourcing standards.
This analysis covers the global market for musk aroma chemicals by source (natural, synthetic, bio-based), musk chemistry type (macrocyclic, polycyclic, nitro, biotech), application (fragrance, personal care, homecare, food, others), end user, and region. It quantifies value in USD across a 2025 base year and 2026–2035 horizon. This analysis does not cover finished fragrance compounding services, adjacent aroma chemical families (amber, woody, floral isolates), or essential oil distillation economics except where they directly influence musk pricing and substitution.
Published estimates diverge by up to 60% on base-year value, driven primarily by whether bio-based and biotech musks are counted inside the synthetic bucket and whether bulk aroma chemical intermediates are included. The table below reconciles the leading published positions.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 1243.33 Million | 2025 | 2035 | 5.51% | Synthetic + natural + bio-based, full application set | One published estimate (Market.us) |
| 1213.18 Million | 2024 | 2035 | 4.60% | Source-split natural/synthetic, broad applications | A competing analysis (MRFR) |
| 779.5 Million | 2025 | 2033 | 5.7% | Narrower chemical-ingredient scope, excludes some intermediates | A competing analysis (Grand View) |
| 180.08 Million | 2024 | 2035 | 4.95% | Single-application narrow definition | A competing analysis (Decisions Advisors) |
Our analysis favors the 1243.33 Million base and 5.51% CAGR as the most defensible, because it explicitly separates bio-based/biotech musks and aligns with the observed shift away from animal-derived supply under CITES Appendix I/II constraints. The 779.5 Million figure likely undercounts captive and bulk intermediate volumes, while the 180.08 Million figure appears to reflect a single-application slice rather than the full market.
Segmentation matters because margin pools differ sharply: macrocyclic and bio-based musks command premium pricing, while polycyclic and nitro musks compete primarily on cost in detergents and homecare.
| Parent Segment | Children |
|---|---|
| By Source | Natural Musk, Synthetic Musk, Bio-Based / Biotech Musk |
| By Musk Type | Macrocyclic Musks, Polycyclic Musks, Nitro Musks, Bio-Based / Biotech Musks |
| By Application | Fragrances & Fine Perfumes, Cosmetics & Personal Care, Household Products & Detergents, Food & Beverages, Others |
| By End User | Fragrance Houses, Personal Care Brands, Household Products Companies, Others |
| By Form | Liquid, Powder |
Asia Pacific leads the global musk aroma chemicals market with roughly 38% of consumption value in 2025, supported by expanding beauty and personal care output, rising disposable incomes, and rapid urbanization in China, India, and Japan.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.38% |
| Europe | 0.24% |
| North America | 0.22% |
| Latin America | 0.09% |
| Middle East & Africa | 0.07% |
Europe is the fastest-growing mature region, anchored by the perfumery clusters of France, Germany, and Switzerland and by stringent EU fragrance regulation that rewards compliant, biodegradable molecules. This divergence implies a two-speed market: volume growth in Asia Pacific and value growth in Europe.
Growth is best understood as a tug-of-war between premiumization demand and an escalating regulatory and raw-material cost base. The table isolates mechanism and evidence strength for each factor.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Premium & long-lasting fragrance demand | Driver | High | Musk as fixative extends scent longevity, justifying premium pricing |
| Personal care & homecare expansion | Driver | High | Deodorants, lotions, detergents require consistent scent profiles |
| Sustainability & bio-based shift | Driver | Medium-High | Clean-label positioning and renewable feedstock differentiation |
| Regulatory allergen labeling (EU 2023/1545) | Restraint | High | 56 new allergen labels raise testing, traceability, and reformulation costs |
| Polycyclic and nitro restrictions (AHTN limits) | Restraint | High | Concentration caps constrain use in fine fragrance and rinse-off |
| Natural musk supply limits | Restraint | High | CITES Appendix I/II listing restricts animal-derived supply |
The balance favors growth, but the composition of growth is shifting toward compliant synthetic and bio-based molecules. Our analysis suggests the restraint column is under-priced by volume-focused forecasts: reformulation costs are front-loaded, so margin compression may appear 12–18 months before volume slowdowns become visible.
The market is moderately consolidated, led by multinational fragrance houses with proprietary molecules, deep toxicology capability, and long-standing relationships with global consumer goods companies.
| Company | HQ | Strategic Position | Moat |
|---|---|---|---|
| Givaudan | Switzerland | Global fragrance leader | Proprietary molecules, R&D scale |
| DSM-Firmenich | Switzerland | Musk and ingredient innovation | Habanolide biodegradable musk capacity |
| Symrise | Germany | Broad aroma chemical portfolio | Cost-efficient synthesis, distribution |
| IFF | USA | Fine fragrance and personal care | Formulation expertise, brand relationships |
| Takasago | Japan | Specialty aroma chemicals | Regional strength in Asia Pacific |
| Robertet | France | Natural and premium ingredients | Natural sourcing heritage |
| MANE | France | Fragrance compounding | Mid-tier cost competitiveness |
| PFW Aroma Chemicals | Netherlands | Specialty musk molecules | Niche chemistry focus |
Differentiation rests on three moats: proprietary molecule IP, regulatory and toxicology infrastructure, and secured feedstock for bio-based routes. Mid-tier producers compete on price and specialized offerings, creating a dynamic balance between innovation and cost efficiency. DSM-Firmenich's 2024 Castets, France expansion for biodegradable Habanolide is a clear signal that capacity leadership in sustainable musks is becoming the decisive competitive lever.
Selection criteria are shifting from pure cost-per-kilo toward compliance-ready documentation, biodegradability profiles, and supply reliability. Buyers procuring musk for EU-exposed products should require full allergen disclosure above 0.001% in leave-on and 0.01% in rinse-off formulations, with non-compliant inventory only marketable until July 31, 2026. AHTN concentration caps (2.5% fine fragrance, 0.5% fragrance cream, 1% certain hydroalcoholic products, 0.2% specified rinse-off) constrain polycyclic substitution flexibility.
Procurement risk concentrates in two areas: single-source dependence on macrocyclic capacity and feedstock volatility for petrochemical intermediates. Switching costs are moderate for commodity polycyclic musks but high for macrocyclic and bio-based molecules, where requalification timelines and sensory re-validation run 6–12 months. Operators should also monitor the IFRA 52nd Standards Amendment consultation, which proposes 51 new restriction standards and 18 revisions, as a leading indicator of reformulation workload.
The balance of evidence favors a compliance-led growth thesis over a pure volume thesis. The market will grow at roughly 5.5% in value, but the growth is increasingly concentrated in molecules that clear regulatory and sustainability hurdles. The strongest counter-argument is that bio-based musks remain capacity-constrained and cost-premium, which could cap near-term substitution and preserve polycyclic dominance longer than sustainability narratives suggest. We judge this a timing risk rather than a directional one.
Our second-order read is that the 62–86% synthetic share range across published estimates reflects definitional ambiguity around bio-based musks, not genuine disagreement on demand. As bio-based volumes scale, that ambiguity resolves in favor of suppliers who can document renewable feedstock provenance. This implies consolidation pressure on mid-tier producers lacking green chemistry capability.
What would change our conclusion: a step-change in natural musk supply legitimacy, or a regulatory rollback of allergen labeling thresholds, would shift value back toward lower-cost polycyclic and natural routes. Precise sub-segment forecasting and vendor-level capacity mapping require the full report.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.51% from 2020-2034 |
| Segmentation |
|
The global musk aroma chemicals market was valued at 1243.33 Million in 2025. It is projected to reach 2124.97 Million by 2035, growing at a 5.51% CAGR, with Asia Pacific holding roughly 38% of consumption.
Asia Pacific leads with about 38% of global value, driven by China, India, and Japan. Europe is the fastest-growing mature region, supported by premium perfumery and stringent compliance-driven reformulation.
The market splits into macrocyclic, polycyclic, nitro, and bio-based/biotech musks. Macrocyclic musks lead at roughly 38% share due to refined scent quality and suitability for premium formulations.
Givaudan, DSM-Firmenich, Symrise, IFF, Takasago, Robertet, MANE, and PFW Aroma Chemicals lead. Differentiation rests on proprietary molecules, regulatory infrastructure, and secured bio-based feedstock.
Demand is driven by premium long-lasting fragrance, personal care and homecare expansion, and sustainability-led bio-based innovation. Regulatory allergen labeling and polycyclic restrictions are the main restraints.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, with structured interviews and expert consultations forming the evidentiary core. We conducted in-depth interviews across the value chain, including raw material and intermediate suppliers, specialized musk producers, contract formulators and blenders, global fragrance distributors, and end-use brand procurement teams. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D and Fragrance Development, Technical Directors, Regulatory Affairs Managers, and Commercial Operations Leads. Interviews probed capacity availability, molecule qualification timelines, allergen disclosure readiness, and pricing expectations across macrocyclic, polycyclic, and bio-based musk families.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Fragrance Development Heads | 35% |
| Procurement & Sourcing Directors | 30% |
| Regulatory & Quality Leads | 25% |
| Commercial Operations Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Intermediate Suppliers | 30% |
| Specialized Musk Producers | 30% |
| Formulators & Blenders | 25% |
| Distributors & Traders | 15% |
We validated interview findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K, SEC filings), patent databases, and recognized technical standards and industry association publications. Regulatory documentation from the European Chemicals Agency and IFRA standards consultations provided the compliance backbone for molecule-level assessment.
Market sizing triangulates top-down macroeconomic and industry segment allocation against bottom-up manufacturer capacity, product pricing, and end-use consumption modeling. Divergent published estimates were reconciled through explicit scope definition, particularly around bio-based and bulk intermediate inclusion.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |