 Carbon Disulfide Market
 Outlook & Forecast 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 215

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Carbon Disulfide Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 153.0 M |
| 2026 | 158.0 M |
| 2027 | 164.0 M |
| 2028 | 170.0 M |
| 2029 | 176.0 M |
| 2030 | 183.0 M |
| 2031 | 189.0 M |

The carbon disulfide market encompasses the global production, distribution, and consumption of CS₂, a volatile organosulfur compound used primarily as an industrial intermediate in viscose rayon, cellophane, rubber chemicals, agrochemicals, and mining reagents. Its demand is tightly linked to textile, automotive, and agricultural cycles.
This report covers the global carbon disulfide market, including value and volume analysis across applications (rayon, rubber, agriculture, pharmaceuticals, packaging, and others), end-use industries, and five major regions. It examines production capacity, pricing trends, trade flows, and competitive dynamics. This analysis does not cover adjacent sulfur chemicals such as sulfuric acid, carbon tetrachloride, or specialized rubber accelerators as standalone markets.
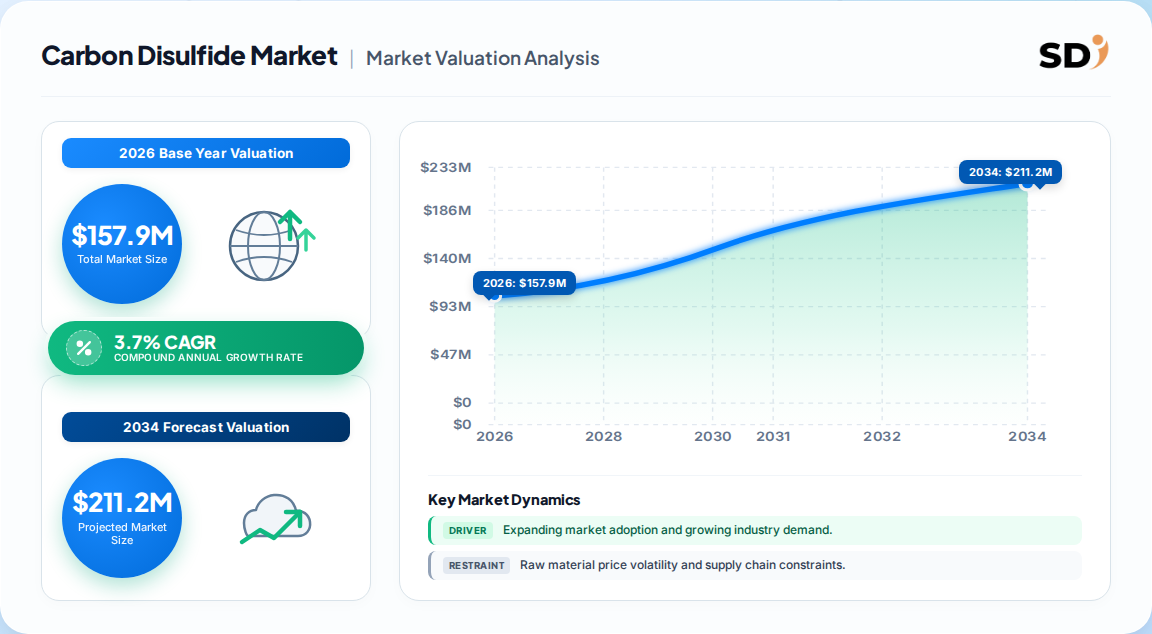
The global carbon disulfide market size was USD 153.1 million in 2025 and is projected to reach USD 157.9 million in 2026, growing at a 3.7% CAGR to USD 203.8 million by 2033. However, competing estimates diverge due to scope and methodology differences.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 153.1M | 2025 | 2033 | 3.7% | Global CS₂, application-based | One published estimate |
| USD 229.86M | 2024 | 2030 | 2.86% | Global CS₂, end-user based | A competing analysis |
| USD 561.4M | 2025 | 2034 | 2.46% | Global CS₂, purity & application | Another published analysis |
| USD 153.29M | 2025 | 2032 | 4.53% | Global CS₂, value-based | A third-party forecast |
| USD 782M | 2025 | 2036 | 4.1% | Global CS₂, capacity & demand | Industry tracking service |
Our analysis suggests the USD 153–158 million range is most defensible for the merchant market, as it aligns with trade flow data and excludes captive production. The higher estimates likely include captive consumption or broader sulfur chemical derivatives, which inflates the addressable market. Buyers should use the lower figure for procurement budgeting and the higher figures for strategic total-addressable-market assessments.
The carbon disulfide market is segmented by application, end-use industry, purity grade, and sales channel, with rayon and rubber chemicals dominating volume consumption.
| Parent Segment | Children |
|---|---|
| By Application | Rayon, Rubber, Agriculture, Pharmaceuticals, Packaging, Cleaning Carbon Nanotubes, Perfumes, Cellophane, Others |
| By End-Use Industry | Textile, Agriculture, Packaging, Pharmaceuticals, Cosmetics, Mining, Others |
| By Purity | Pure, Impure |
| By Sales Channel | Direct Sales, Distributors, Online |
Rayon fiber production remains the anchor segment, consuming over 50% of global CS₂ volume, while mining reagents (xanthates) represent the fastest-growing application, driven by copper and nickel demand for electrification.
Asia Pacific leads the global carbon disulfide market, accounting for 54.8% revenue share in 2025, driven by China’s dominant viscose rayon and chemical manufacturing base, followed by India and Southeast Asia.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.55% |
| North America | 0.16% |
| Europe | 0.15% |
| Latin America | 0.08% |
| Middle East & Africa | 0.06% |
| Region | Share (2025) |
|---|---|
| Asia Pacific | 55% |
| North America | 16% |
| Europe | 15% |
| Latin America | 8% |
| Middle East & Africa | 6% |
China alone holds the largest country share, supported by integrated viscose fiber chains and favorable industrial policies. India is emerging as a key growth node with expanding textile and agrochemical capacities. Western markets remain mature, with demand shaped by environmental compliance and specialty applications.
Growth is driven by rising demand for viscose rayon in sustainable textiles, rubber chemicals for tires, and dithiocarbamate agrochemicals, while stringent environmental and safety regulations and volatile sulfur feedstock prices restrain expansion.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising rayon fiber demand | Driver | High | Viscose process requires CS₂ for xanthation; biodegradable textile shift |
| Rubber & tire production growth | Driver | High | CS₂ used in rubber accelerators and vulcanization agents |
| Agrochemical demand | Driver | Medium | Dithiocarbamate fungicides and fumigants rely on CS₂ |
| Environmental & safety regulations | Restraint | High | Exposure limits, emission controls, and handling costs raise compliance burden |
| Volatile sulfur prices | Restraint | High | Sulfur feedstock accounts for large share of production cost; price swings disrupt margins |
| Emerging economy industrialization | Opportunity | Medium | New chemical manufacturing capacity in Asia Pacific and Southeast Asia |
The balance favors steady but moderated growth. Environmental regulations are raising barriers to entry and favoring integrated producers with closed-loop recovery systems. Our analysis suggests that the regulatory burden will accelerate consolidation in China’s fragmented producer base, improving pricing discipline.
The carbon disulfide market is moderately concentrated, with global chemical majors and specialized Asian producers competing on cost, compliance, and supply reliability.
| Company | Headquarters | Market Position | Differentiation |
|---|---|---|---|
| Arkema S.A. | France | Global leader | Broad sulfur chemistry portfolio; strong safety systems |
| Merck KGaA | Germany | Specialty chemicals | High-purity CS₂ for pharmaceuticals and electronics |
| Nouryon | Netherlands | Global producer | Integrated supply chain; focus on sustainable production |
| Shikoku Kasei Holdings | Japan | Asian leader | Advanced recovery technology; strong rayon customer base |
| Liaoning Ruixing Chemical | China | Cost leader | Scale production; domestic rayon supply chain integration |
| Shanghai Baijin Chemical | China | Regional player | Competitive pricing; expanding export footprint |
| Thermo Fisher Scientific | USA | Lab-scale | High-purity analytical grades; distribution strength |
Differentiation hinges on environmental compliance, closed-loop recovery capabilities, and secure sulfur feedstock access. Chinese producers compete on price but face rising compliance costs, while Western majors leverage safety and traceability. Our analysis suggests that vendors with proprietary recovery technology will capture premium pricing as regulations tighten.
Procurement of carbon disulfide requires careful attention to safety compliance, supplier reliability, and price volatility. CS₂ is highly flammable and toxic, classified as a dangerous good, so storage, transport, and handling must meet stringent occupational exposure limits and environmental standards. Buyers should prioritize suppliers with certified safety management systems and closed-loop recovery capabilities, as these reduce both supply risk and regulatory exposure. Switching costs are moderate to high due to the need for qualified handling infrastructure and long-term supply agreements. Price volatility is significant: Q2 2026 quotes ranged from USD 694/MT in China to USD 1,124/MT in Canada, a 62% spread, driven by sulfur costs and logistics. Buyers should consider dual-sourcing strategies and index-linked contracts to manage risk. Regulatory compliance in Europe and North America is more demanding, but Asian suppliers are rapidly upgrading to meet export requirements. Operators must also monitor China’s environmental enforcement, which could disrupt supply from smaller producers.
The balance of evidence favors a cautiously optimistic outlook for the carbon disulfide market, with steady 3.7% growth underpinned by viscose rayon and rubber chemical demand. However, the market faces a structural shift: environmental regulations are raising costs and squeezing marginal producers, particularly in China. This will likely lead to supply consolidation and higher prices, especially in Western markets. The strongest counter-argument is that a faster-than-expected shift away from viscose rayon due to sustainability concerns could dampen demand; however, current data shows no sign of substitution at scale, as biodegradable textiles remain a key driver.
Our analysis suggests that the most significant opportunity lies in the mining reagents segment, where CS₂-derived xanthates are essential for copper and nickel extraction. Electrification and renewable energy infrastructure will drive above-average growth for this application, potentially outpacing rayon by 2030. Buyers should also note that sulfur price volatility will remain a key risk, and suppliers with integrated sulfur sourcing or long-term contracts will have a competitive advantage.
Actionable Strategy:
What evidence would change our conclusion? A sharp decline in viscose rayon demand due to a breakthrough in alternative cellulose solvents, or a major regulatory ban on CS₂ in a key market, would necessitate a downward revision. Conversely, accelerated mining sector growth could push CAGR above 5%.
The carbon disulfide market is at a regulatory and technological inflection point. While volume growth remains steady, value is migrating toward compliant, integrated producers. The divergence in published estimates highlights the importance of defining scope carefully; buyers should rely on merchant-market figures for procurement and full-value-chain estimates for strategic planning.
Recommendations:
The full report provides granular forecasts by application, country-level pricing, and vendor capacity mapping to support these decisions.
The balance of evidence favors a cautiously optimistic outlook with a 3.7% CAGR, but the market is becoming more compliance-intensive and consolidated. The strongest counter-argument is that a faster shift to sustainable textiles could reduce viscose demand, but current data shows no large-scale substitution. Our analysis suggests that mining reagents and pharmaceuticals offer the best growth opportunities, while rayon remains the volume anchor. Buyers should secure long-term contracts with compliant Asian suppliers and invest in handling infrastructure to manage safety and price risks.
Actionable Strategy:
What evidence would change our conclusion? A major regulatory ban in Europe or a breakthrough in alternative cellulose solvents would require a downward revision. Conversely, accelerated mining demand could push CAGR above 5%.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.7% from 2020-2034 |
| Segmentation |
|
The global carbon disulfide market was valued at USD 153.1 million in 2025 and is estimated at USD 157.9 million in 2026, with a forecast to reach USD 203.8 million by 2033.
Asia Pacific dominates with a 54.8% revenue share in 2025, led by China’s viscose rayon and chemical manufacturing base, followed by India and Southeast Asia.
Key applications include viscose rayon, rubber chemicals, agricultural fungicides and fumigants, pharmaceuticals, packaging, and mining flotation agents. Rayon is the largest volume segment.
The market is projected to grow at a CAGR of 3.7% from 2026 to 2033, driven by steady demand from textiles, rubber, and agrochemicals, though regulations temper faster expansion.
Leading producers include Arkema S.A., Merck KGaA, Nouryon, Shikoku Kasei Holdings, Liaoning Ruixing Chemical Group, and Shanghai Baijin Chemical Group, among others.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology relied on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with 42 stakeholders across the carbon disulfide value chain, including raw material (sulfur) suppliers, specialized CS₂ producers, contract formulators, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring insights from both strategic and operational perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory Affairs Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical Producers | 45% |
| Formulators & Blenders | 30% |
| Distributors & Traders | 25% |
We triangulated primary data with official multilateral trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings (10-K, SEC filings), patent databases, and technical standards from recognized industry associations. This validated production capacities, trade flows, and pricing trends across regions.
Our demand modeling employed simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption) approaches. This dual methodology minimized estimation error and captured captive versus merchant market dynamics.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |