 Glass Bonding Adhesives Market
: 2026 Size, Share & Forecast
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 213

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Glass Bonding Adhesives Market
Khageshwar Rongkali
Senior Analyst

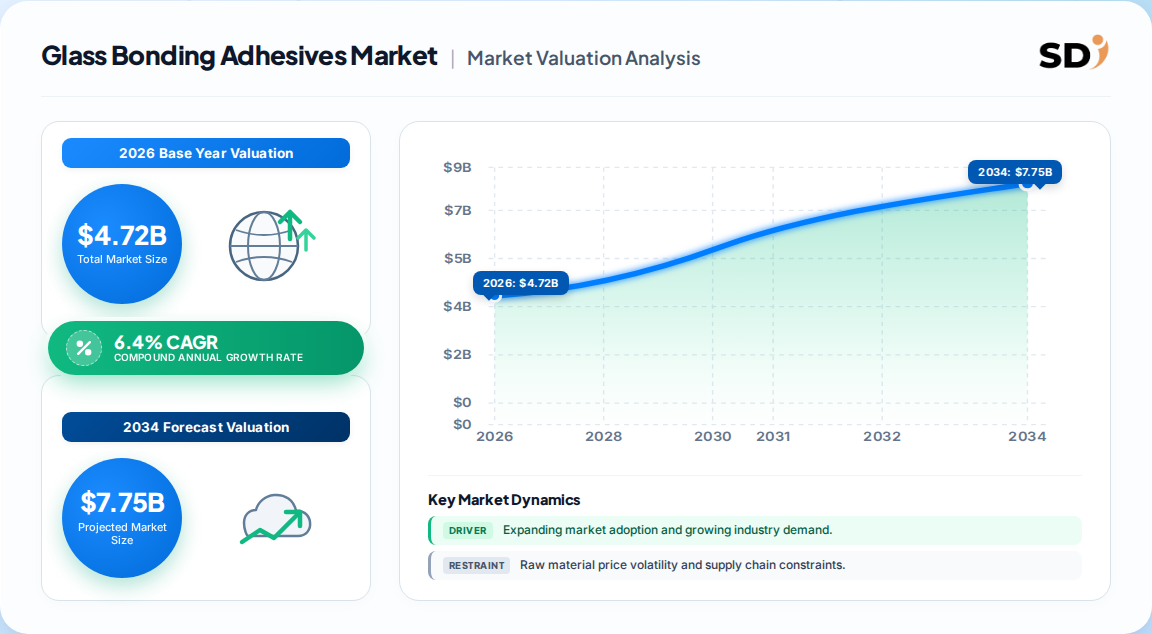
| Year | Market Size |
|---|---|
| 2024 | 4.280 B |
| 2025 | 4.460 B |
| 2026 | 4.720 B |
| 2027 | 5.020 B |
| 2028 | 5.340 B |
| 2029 | 5.680 B |
| 2030 | 6.040 B |

Glass bonding adhesives are specialized formulations—epoxy, silicone, polyurethane, UV-cured, and modified silane—engineered to bond glass to glass, metal, or plastic while maintaining optical clarity, structural integrity, and thermal-cycling resilience. They are mission-critical in automotive glazing, frameless façades, Mini-LED displays, and medical diagnostics.
This analysis covers the global glass bonding adhesives market across five product families and six end-user industries, with a 2020–2035 historical and forecast window. It includes value (USD) sizing, segment share, regional distribution, vendor positioning, and regulatory drivers.
This analysis does not cover adjacent categories such as general-purpose construction sealants, non-optical structural epoxies, thermal interface materials, or glass-manufacturing process chemicals. Precision adhesives for semiconductor wafer bonding are excluded unless used in display assembly.
The market is valued at roughly USD 4.72 billion in 2026, but published estimates diverge meaningfully—reflecting different base years, product taxonomies, and end-use allocations.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 4.45B → 5.86B | 2026 | 2031 | 5.68% | Epoxy, silicone, PU, UV-cured; six end uses | One published estimate |
| USD 4.60B → 8.95B | 2025 | 2034 | 7.7% | PU, modified silanes, silicone, acrylate; broader end-use set | Competing analysis |
| USD 4.72B → 7.99B | 2026 | 2035 | 6.0% | Epoxy, silicone, PU, UV-cured; six end uses | Alternate published estimate |
Our analysis suggests the 6.0–6.5% band is most defensible for strategic planning. The 7.7% figure assumes accelerated electronics penetration that has not yet materialized in quarterly adhesive shipment data. The 5.68% estimate may underweight LED/UV conversion tailwinds.
Segmentation splits by chemistry (which governs cure speed and optical properties) and by end-use industry (which governs qualification cycles and volume).
| Parent Segment | Children |
|---|---|
| By Type | Epoxy, Silicone, Polyurethane, UV-Cured, Modified Silanes, Acrylate, Others |
| By End-User Industry | Automotive & Transportation, Electrical & Electronics, Building & Construction, Furniture, Healthcare, Aerospace, Others |
UV-cured systems hold the largest product share (~30–32%) because flash curing compresses takt times. Silicone is the fastest-growing chemistry, projected near 7% CAGR, on structural façade and EV glazing demand. Automotive leads end-use at 35–37% share; electronics is the fastest-growing end use at ~6.8% CAGR.
Asia-Pacific leads the global market with approximately 44.6% revenue share in 2025, and is also the fastest-growing region, forecast near 6.5% CAGR through the horizon.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.45% |
| North America | 0.22% |
| Europe | 0.22% |
| South America | 0.06% |
| Middle East & Africa | 0.05% |
Asia-Pacific's lead rests on vehicle output in China, display assembly across India and ASEAN, and China's dominance in frameless curtain-wall construction. North America (~22.4%) and Europe (~21.8%) are near-parity, but the former is being reshaped by CHIPS Act-funded display and EV supply chains, while the latter is driven by the Energy Performance of Buildings Directive.
The net growth impulse is strongly positive, with ADAS/HUD integration and EV lightweighting adding the largest incremental CAGR points.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| ADAS & HUD integration | +1.2% CAGR | High (EU 2019/2144) | Bonded brackets and wedges replace clips |
| EV lightweighting & panoramic roofs | +0.9% CAGR | High | Bonded glass roofs replace steel panels |
| Frameless façades (APAC) | +1.1% CAGR | Medium-High | Structural silicone transfers wind loads |
| Mini/Micro-LED assembly | +0.8% CAGR | High | Sub-millimeter die placement, low outgassing |
| VOC/mercury mandates | +0.6–0.9% CAGR | High | Shift to UV/LED curing |
| Raw material & energy volatility | −0.4% CAGR | Medium | Epoxy/silicone feedstock economics |
| Diisocyanate & PFAS restrictions | −0.3% CAGR | Medium | PU grade reformulation costs |
| Long OEM qualification cycles | −0.2% CAGR | High | 12–24 month requalification timelines |
Our analysis suggests the driver stack outpaces restraints by roughly 3:1, but the restraint mix is shifting toward regulatory complexity rather than demand weakness—a structurally different risk profile than the 2018–2022 period.
The market is medium-concentration, with five to seven global players controlling a substantial share alongside regional specialists.
| Company | HQ | Strategic Positioning | Moat |
|---|---|---|---|
| Henkel AG & Co. KGaA | Germany | Broadest portfolio across auto, electronics, industrial | Global qualification footprint, brand |
| Sika AG | Switzerland | Structural glazing and automotive OEM leader | Sikasil/PowerCure tech, 25-year façade warranties |
| 3M | USA | Optical clarity and electronics assembly | VHB/OCA adjacent IP, display OEM ties |
| H.B. Fuller | USA | Industrial assembly and construction | Cost-competitive formulation scale |
| Dymax Corporation | USA | UV/light-cure specialist | Fast-cure chemistry, medical ISO 10993 |
| Arkema | France | Modified silanes (Sartomer/Bostik) | Silane chemistry IP |
| Dow | USA | Silicone and hybrid systems | Vertically integrated siloxane supply |
Differentiation is increasingly built on regulatory documentation and dispensing integration, not just adhesive performance. Vendors offering adhesive-as-a-service models with dosing telemetry are capturing share in high-takt electronics lines. The strongest counter-argument to consolidation is that regional façade specialists in China and India retain structural-silicone share through local code approvals.
Buyers should prioritize optical clarity, outgassing limits, and thermal cycling resilience—but the real differentiator is qualification burden. A single adhesive change on an automotive glazing line can trigger 12–24 months of requalification, making switching costs disproportionately high relative to unit price.
Procurement risk concentrates in three areas. First, diisocyanate and PFAS restrictions are forcing polyurethane and fluorosurfactant reformulations, creating supply continuity risk for legacy grades. Second, UV/LED curing conversion requires new photoinitiator packages, which means dual-sourcing during transition. Third, structural façade warranties of 20–25 years expose buyers to formulation discontinuation risk; contract terms should include formulation-lock clauses.
Regulatory compliance is non-negotiable: California Rule 1168, EU Green Deal VOC caps, EU 2019/2144 ADAS requirements, and the Minamata Convention's mercury phase-down all shape formulation choices. Operators should audit supplier compliance documentation annually and require ISO 10993 certification for any healthcare-adjacent grade.
The balance of evidence favors a moderating growth trajectory near 6.0–6.5% CAGR, not the 7.7% upper estimate. Demand fundamentals are robust—ADAS penetration is regulatory, not discretionary—but qualification bottlenecks and regulatory reformulation costs cap how fast volume can convert to revenue. The strongest counter-argument is that electronics could surprise to the upside as Mini-LED and micro-transfer printing scale; if that happens, the 7.7% estimate becomes defensible.
Our analysis suggests the most important second-order effect is margin migration from chemistry to service. As adhesive performance converges, vendors that bundle dispensing hardware, cure verification, and compliance documentation will defend pricing. Pure-formulation suppliers face compression as OEMs multi-source to de-risk supply.
Actionable Strategy:
The evidence that would change our conclusion: faster-than-expected micro-LED adoption (>15% of premium displays by 2028) or a regulatory rollback on PFAS that relieves PU reformulation pressure.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.4% from 2020-2034 |
| Segmentation |
|
The market is estimated at USD 4.72 billion in 2026, with one published estimate projecting USD 8.95 billion by 2034 and a competing analysis at USD 7.99 billion by 2035. The base-year values cluster tightly between USD 4.45 and 4.72 billion.
Asia-Pacific leads with approximately 44.6% revenue share in 2025 and is also the fastest-growing region. China's vehicle output, India-ASEAN electronics assembly, and frameless curtain-wall construction underpin regional leadership.
Silicone adhesives are the fastest-growing chemistry at roughly 7% CAGR, driven by structural façade and EV glazing demand. Electrical and Electronics is the fastest-growing end-use segment at approximately 6.8% CAGR.
Henkel, Sika, 3M, H.B. Fuller, Dymax, Arkema, and Dow anchor the competitive landscape. The market is medium-concentration, with differentiation shifting toward dispensing integration and regulatory documentation rather than adhesive performance alone.
ADAS and HUD integration in automotive glazing, EV lightweighting with panoramic roofs, Mini-LED display assembly, and stringent VOC and mercury-reduction mandates collectively add roughly 3 percentage points to baseline CAGR.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material and siloxane suppliers, specialized adhesive formulators, contract blenders, and global industrial distributors across automotive, electronics, construction, and medical channels. Decision-makers interviewed include VP-level Sourcing leads, Heads of Adhesive R&D, Technical Directors for Glazing and Display Assembly, and Commercial Operations Leads at tier-one suppliers. Fieldwork captured qualification timelines, formulation transition costs, and dispensing integration requirements that published data cannot reveal.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Technical & Quality Managers | 25% |
| Regulatory Affairs Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Silicone Producers | 30% |
| Adhesive Formulators & Blenders | 40% |
| Industrial Distributors & Traders | 20% |
| OEM Procurement & Engineering | 10% |
Secondary validation draws on UN Comtrade and WTO trade flows for adhesive and silicone precursor codes, US ITC and Eurostat shipment data, corporate 10-K and annual investor filings from listed adhesive producers, patent databases for UV-cure and silane chemistry, and technical standards from ASTM (C1184, C1401, C920) and ISO 10993 for medical-grade compliance. Regulatory filings under EU 2019/2144, California Rule 1168, and the Minamata Convention inform the regulatory driver framework.
Sizing runs in parallel: Top-down allocation from macroeconomic construction, automotive, and electronics output, and bottom-up consumption modeling per vehicle, per façade square meter, and per display unit. Pricing benchmarks are reconciled against distributor quotes and formulator disclosures.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |