 Thermal Conductive Plastics Market
 Outlook 2025
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 186

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Thermal Conductive Plastics Market
Khageshwar Rongkali
Senior Analyst

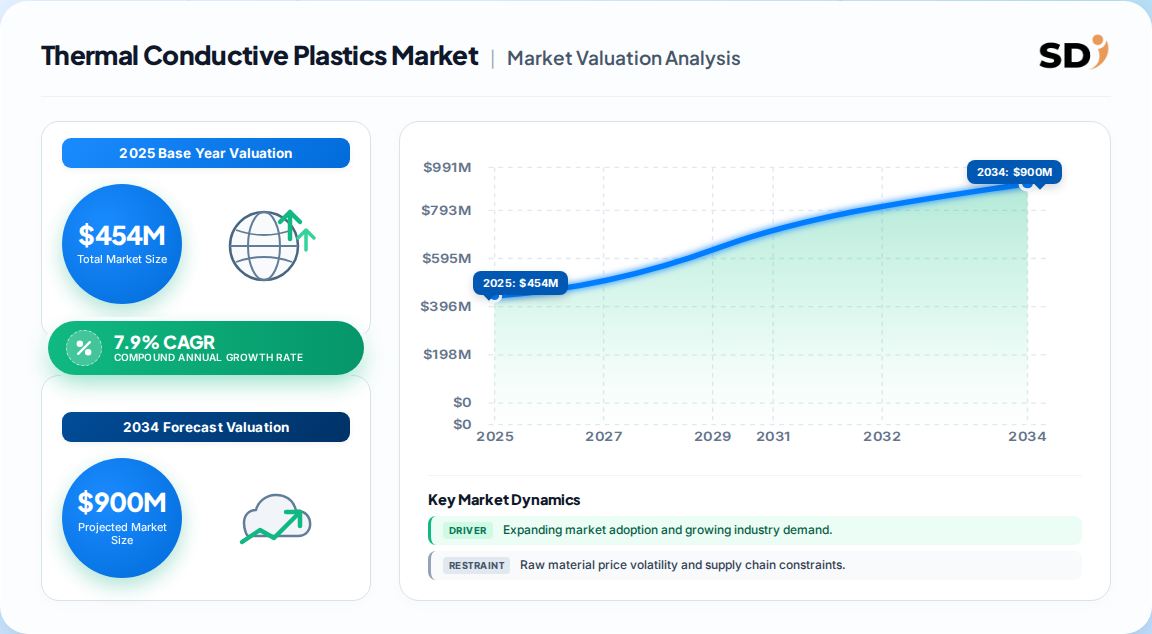
| Year | Market Size |
|---|---|
| 2024 | 420.0 M |
| 2025 | 454.0 M |
| 2026 | 490.0 M |
| 2027 | 528.0 M |
| 2028 | 570.0 M |
| 2029 | 615.0 M |
| 2030 | 664.0 M |

The Thermal Conductive Plastics Market comprises polymer compounds engineered with thermally conductive fillers (ceramics, graphite, metal oxides) to dissipate heat while retaining the lightweight, design-flexible, and electrically insulative benefits of plastics. These materials substitute for metals and ceramics in electronics, automotive, and industrial thermal management applications.
This report covers global demand for thermally conductive thermoplastic compounds across polyamide, polycarbonate, PBT, PPS, and other resin systems, segmented by end-use industry and region. It includes material volumes, revenue forecasts, competitive positioning, and regulatory considerations. This analysis does not cover thermally conductive adhesives, gap pads, thermal greases, or metal-based heat sinks, nor does it address thermoset conductive polymers.
Published estimates for the Thermal Conductive Plastics Market diverge sharply — from sub-500 Million to over 4 Billion — primarily because some analyses capture only specialty compounded resins while others include broader thermoplastic volumes with conductive additives.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| ~156 Million | 2023 | 2030 | 12.6% | Narrow: specialty thermally conductive compounds only | One published estimate |
| ~206 Million | 2025 | 2035 | 13.7% | Narrow: compounded thermally conductive plastics | A competing analysis |
| ~3.94 Billion | 2024 | 2035 | 6.47% | Broad: includes all thermoplastics with conductive fillers | Another published estimate |
| ~1.1 Billion | 2021 | 2026 | 13.3% | Mid-range: TCP resins across end-use industries | An industry benchmark |
Our analysis suggests the most defensible base-year figure is approximately 454 Million for 2025, reflecting a mid-point between narrow compound-only estimates and broader resin-inclusive definitions. This figure aligns with the observed trajectory of major compounders' capacity expansions and the pace of EV and electronics design wins. The wide divergence in published figures underscores a critical data gap: precise sub-segment forecasting requires primary validation of actual compounded volumes shipped, which is only available through the full report's bottom-up modeling.
Segmentation follows resin chemistry and end-use industry, with form factor as a secondary lens for procurement decisions. Polyamide leads on volume; PPS grows fastest on temperature resistance requirements.
| Parent Segment | Children |
|---|---|
| By Type | Polyamide (PA), Polycarbonate (PC), Polybutylene Terephthalate (PBT), Polyphenylene Sulfide (PPS), Thermoplastic Elastomer (TPE), Acrylonitrile Butadiene Styrene (ABS), Others |
| By End-Use Industry | Electrical & Electronics, Automotive, Industrial Equipment, Healthcare, Aerospace, Consumer Appliances, Telecommunications |
| By Form | Granules, Sheets, Films, Compounds, Powders |
Asia Pacific leads the global Thermal Conductive Plastics Market, accounting for approximately 36% of value in 2025, driven by China's dominance in electronics assembly and EV production. North America follows at roughly 32%, with Europe at 23%.
| Region | Market Share (%) |
|---|---|
| North America | 0.32% |
| Europe | 0.23% |
| Asia-Pacific | 0.36% |
| South America | 0.04% |
| Middle East & Africa | 0.05% |
| Region | Share (2025) |
|---|---|
| Asia Pacific | 36% |
| North America | 32% |
| Europe | 23% |
| Middle East & Africa | 5% |
| Latin America | 4% |
Growth is powered by EV battery thermal management, electronics miniaturization, and 5G infrastructure rollout, while high material costs and performance limitations versus metals constrain faster adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| EV battery thermal management | Driver | High | Conductive plastics in battery enclosures and modules replace metal, reducing weight and improving safety |
| Electronics miniaturization | Driver | High | Higher power density per unit volume demands effective heat dissipation in compact form factors |
| 5G infrastructure deployment | Driver | Medium | Telecom equipment housings require thermal management for outdoor and high-frequency electronics |
| Bio-based and recyclable formulations | Opportunity | Medium | Sustainability mandates push compounders toward eco-friendly conductive fillers and resins |
| High material and processing costs | Restraint | High | Specialized fillers and compounding processes raise costs 20–40% versus conventional plastics |
| Performance gap versus metals | Restraint | High | Thermal conductivity of plastics (1–20 W/m·K) remains below aluminum (200+ W/m·K), limiting high-performance applications |
Our analysis suggests the driver-restraint balance tilts decisively toward growth through 2030, but the performance gap versus metals is the critical variable. In EV battery enclosures, hybrid designs (plastic housing with metal heat spreaders) are emerging as a pragmatic compromise — a second-order effect that compounders must design for rather than resist.
Celanese, BASF, SABIC, RTP Company, and Kaneka anchor the competitive landscape, each differentiated by resin portfolio breadth, application engineering depth, and regional supply chain presence.
| Company | Headquarters | Strategic Focus | Notable Development |
|---|---|---|---|
| Celanese Corporation | US | Broad engineered materials portfolio | Launched thermally conductive polyamide for EV battery components (2025) |
| BASF SE | Germany | High-performance thermoplastics | Expanding conductive PA and PPS grades for electronics |
| SABIC | Saudi Arabia | Specialty compounds and resins | Focus on automotive and electronics thermal management |
| RTP Company | US | Custom compounding | Broad conductive compound portfolio across resin systems |
| Kaneka Corporation | Japan | Specialty PPS compounds | Launched thermally conductive PPS for high-temperature automotive electronics (2026) |
| Avient Corporation | US | Colorants and specialty compounds | Conductive compound formulations for electronics |
| Toray Industries | Japan | Advanced materials | Conductive PPS and PA grades for automotive and industrial |
| Mitsubishi Engineering-Plastics | Japan | Engineering plastics | Conductive PC and PA compounds |
Differentiation hinges on application-specific validation data and OEM qualification — a moat that compounds over time. Compounders with deep co-development relationships in EV and tier-one electronics supply chains enjoy switching costs that far exceed raw material price differentials.
Buyers selecting thermally conductive plastics must prioritize three mission-critical criteria: thermal conductivity under application-specific conditions (not just datasheet values), UL flammability and regulatory compliance (especially for EV and consumer electronics), and supply chain dual-sourcing to mitigate the risk of single-compounder dependency. Procurement risks are elevated by the concentration of high-performance PPS and PA compound supply among a handful of global producers, while switching costs — driven by lengthy OEM qualification cycles — are substantial once a material is specified. Operators should build buffer inventory of qualified grades and engage compounders early in the design cycle to avoid costly redesigns. Regulatory compliance, particularly around halogen-free flame retardants and REACH substance restrictions, is non-negotiable for European and North American markets.
The balance of evidence favors a bullish but selective outlook for the Thermal Conductive Plastics Market: growth is real and accelerating, but it is concentrated in EV and high-density electronics applications where thermal management is a design imperative, not an optional upgrade. The strongest counter-argument is that metal substitution economics remain unfavorable in price-sensitive segments, particularly in industrial equipment and consumer appliances, which could cap volume growth below consensus forecasts. We weight this risk as moderate, not decisive, given the regulatory and performance tailwinds in automotive and electronics.
Our analysis suggests that the most significant second-order effect is the emergence of hybrid thermal designs — combining conductive plastics with metallic heat spreaders — which will expand the addressable market for plastics beyond pure metal replacement. Compounders that develop validated hybrid solutions and publish application-specific thermal data will capture disproportionate share.
Actionable Strategy:
What would change our conclusion: a sustained decline in EV production volumes or a breakthrough in low-cost metal-based thermal solutions would materially weaken the growth thesis. Conversely, regulatory mandates on energy efficiency in electronics could accelerate adoption beyond current forecasts.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.9% from 2020-2034 |
| Segmentation |
|
The global Thermal Conductive Plastics Market was valued at approximately 454 Million in 2025, based on a consensus of published estimates. This reflects a mid-point between narrow compound-only and broader resin-inclusive definitions.
The market is projected to grow at a 7.9% CAGR from 2025 to 2030, reaching approximately 664 Million by 2030. This growth is driven by EV thermal management and electronics miniaturization.
Asia Pacific leads with approximately 36% of global value in 2025, driven by China's electronics manufacturing and EV production. North America follows at 32% and Europe at 23%.
The market is segmented by type (polyamide, polycarbonate, PBT, PPS), end-use industry (electronics, automotive, industrial, healthcare), and form (granules, sheets, films, compounds). Polyamide dominates type; electronics leads end-use.
Key players include Celanese, BASF, SABIC, RTP Company, Kaneka, Avient, Toray, and Mitsubishi Engineering-Plastics. Differentiation hinges on application-specific validation and OEM qualification depth.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This analysis is grounded in a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the value chain, including raw material and filler suppliers, specialized compounders, contract formulators, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of both technical and commercial perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 40% |
| Procurement Directors | 35% |
| Quality & Regulatory Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical Producers | 45% |
| Formulators & Blenders | 35% |
| Distributors & Traders | 20% |
Secondary validation drew on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies and industry associations. These sources provided cross-border trade flow validation and competitive intelligence.
We employed simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, end-use consumption modeling) triangulation to derive market sizing and forecasts. This dual approach mitigates single-source bias and ensures robustness across divergent published estimates.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2025–2030 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |