 Fiber Optic Fire Heat Detectors Market
 2025 Guide
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 206

Khageshwar Rongkali

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Fiber Optic Fire Heat Detectors Market
Khageshwar Rongkali
Senior Analyst
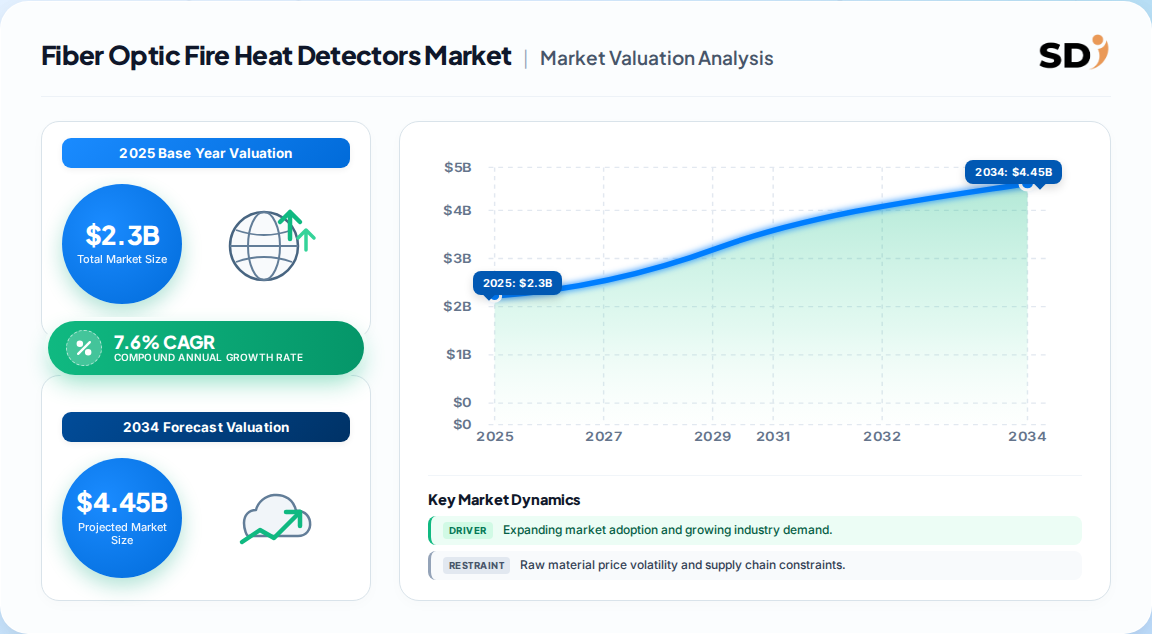
| Year | Market Size |
|---|---|
| 2025 | 2.300 B |
| 2026 | 2.470 B |
| 2027 | 2.660 B |
| 2028 | 2.860 B |
| 2029 | 3.080 B |
| 2030 | 3.320 B |
| 2031 | 3.570 B |

The fiber optic fire heat detectors market covers systems that use optical fiber as a continuous sensing element to detect temperature anomalies and fire events along entire cable runs. Unlike point detectors, these distributed systems deliver real-time, meter-level localization across kilometers, serving tunnels, pipelines, data centers, and industrial plants.
This analysis covers distributed temperature sensing (DTS), distributed acoustic sensing (DAS), and fiber Bragg grating (FBG) fire/heat detection systems across oil and gas, tunnels and transportation, power utilities, data centers, commercial buildings, and industrial manufacturing, globally from 2024 to 2033. This analysis does not cover conventional point smoke/heat detectors, aspirating smoke detection, or standalone structural-health-monitoring fiber services outside fire-safety use cases.
Leading published estimates diverge on the base year but converge on a mid-to-high single-digit CAGR, implying structural demand growth rather than a cyclical spike. The table below reconciles the two most-cited benchmark sets.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.9B → USD 3.1B | 2024 | 2030 | 7.8% | Fiber optic fire and heat detectors, DTS/DAS/FBG, global | One published estimate (Strategic Market Research-type) |
| USD 2.3B → USD 4.1B | 2025 | 2033 | 7.6% | Fiber optic fire and heat detectors, by type/application, global | A competing analysis (Grand View-style) |
| USD 0.18B (MEA only) | 2025 | 2030 | 5.7% | MEA fiber optic heat detector + system integrator | Regional trade-release benchmark |
Our analysis suggests the USD 2.3B (2025) figure is the more defensible base: it aligns with broader fire-detector market scale (~USD 16.8B in 2025) at an implied ~14% fiber share, which is consistent with DTS penetration in high-risk verticals. The lower USD 1.9B estimate likely excludes system-integration and software revenue—a definitional gap that materially changes vendor-addressable spend.
The market segments along three buyer-relevant axes—technology, application, and end user—each mapping to distinct risk profiles and procurement logic.
| Parent | Children |
|---|---|
| By Product Type | DTS, DAS, FBG |
| By Application | Oil & Gas Facilities, Tunnels & Transportation Infrastructure, Energy & Power Utilities, Data Centers & Commercial Buildings, Industrial Manufacturing |
| By End User | Oil & Gas Operators, Public Infrastructure Authorities, Power & Utility Companies, Data Center Operators, Industrial Facilities |
DTS dominates because it balances long-distance coverage with cost per kilometer; DAS is ascending where multi-parameter (acoustic + thermal) sensing is required, particularly in pipelines and perimeter security.
North America leads with roughly 32% revenue share in 2025, but Asia Pacific is the fastest-growing region as metro, tunnel, and industrial infrastructure programs scale. Europe remains the regulatory bellwether for tunnel safety mandates.
| Region | Market Share (%) |
|---|---|
| North America | 0.32% |
| Europe | 0.26% |
| Asia-Pacific | 0.28% |
| Latin America | 0.06% |
| Middle East & Africa | 0.08% |
The divergence matters: North America buys on risk and uptime, Europe on compliance, and Asia Pacific on project volume—three different go-to-market motions.
Growth is driven by infrastructure complexity, tightening fire-safety regulation, and the rising cost of downtime—while high installation cost and skilled-labor scarcity restrain adoption in cost-sensitive segments.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising infrastructure investment (tunnels, metros, energy) | Driver | High | Mandates continuous linear coverage over point sensors |
| Tightening fire-safety regulation (EU, Middle East) | Driver | High | Compliance frameworks favor linear heat detection |
| Data-center uptime economics | Driver | High | Proactive, non-regulatory buying to avoid downtime |
| AI/IIoT integration and false-alarm reduction | Driver | Medium | Improves ROI, enables predictive maintenance |
| High initial installation and integration cost | Restraint | High | Limits SME and mid-sized facility adoption |
| Skilled-labor scarcity in developing regions | Restraint | Medium | Slows calibration, commissioning, and maintenance |
| Supply-chain dependency on specialty optical components | Restraint | Medium | Procurement delays affect project timelines |
Our analysis suggests the restraint balance is softening: falling interrogation-unit costs and plug-and-play retrofits are lowering the adoption barrier, while insurance incentives quietly expand the addressable base beyond regulation-driven buyers.
The vendor field is specialized and trust-driven—buyers select proven deployments over lowest price, and competitive moats are built on project references, harsh-environment credibility, and integration capability.
| Vendor | Primary strength | Typical stronghold |
|---|---|---|
| AP Sensing GmbH | Premium DTS, long-distance precision | European tunnels, rail |
| Halliburton (Sensornet) | Oil & gas domain expertise | Pipelines, offshore, refineries |
| Siemens AG | End-to-end infrastructure integration | Tunnels, metros, smart city |
| Schneider Electric | Facility and energy-management integration | Data centers, commercial |
| Bandweaver Technologies | Hybrid DTS/DAS multi-parameter sensing | Transportation, perimeter security |
| Luna Innovations | Advanced R&D-grade sensing | Aerospace, defense, niche precision |
| Yokogawa Electric | Sensing-plus-control integration | Chemical, process industries |
Differentiation hinges less on hardware specs and more on integration into SCADA/BMS, false-alarm performance, and long-term service networks—the factors that decide repeat public-sector contracts.
Selection should prioritize continuous coverage, false-alarm performance, and integration with existing control systems over headline price—because in mission-critical environments the cost of a missed event dwarfs the system premium. Procurement risk concentrates in three areas: retrofit complexity in legacy facilities, calibration and commissioning skill gaps, and vendor lock-in via proprietary interrogation units and analytics platforms. Buyers should demand open protocols, documented reference deployments in comparable environments, and total-cost-of-ownership modeling that includes maintenance and false-alarm-induced downtime. Regulatory compliance (tunnel safety codes, industrial fire standards) is increasingly a floor, not a differentiator, so forward-looking operators should evaluate predictive-maintenance and digital-twin integration as the real long-term value driver. Switching costs are high post-installation, making upfront due diligence on vendor roadmap and service footprint essential.
The balance of evidence favors a structural, regulation-and-uptime-driven growth story rather than a cyclical one. The definitional gap between the two leading estimates (USD 1.9B vs USD 2.3B base) should not obscure the consensus: mid-to-high single-digit CAGR through the early 2030s, with data centers and Asia Pacific infrastructure as the incremental growth engines. The strongest counter-argument is that high installation cost and integration complexity could cap adoption in mid-market industrial facilities—precisely where price sensitivity is highest and where conventional detection still dominates.
Our judgment is that this restraint is real but narrowing: plug-and-play interrogation units, ruggedized cabling, and AI-driven false-alarm reduction are steadily improving the retrofit economics. The more consequential risk is commoditization of DTS hardware, which would shift value capture toward software, analytics, and integration services—favoring vendors like Siemens, Schneider, and Yokogawa with platform positions over pure-play sensor suppliers.
Actionable strategy:
Evidence that would change this conclusion: a sustained drop in DTS unit pricing without corresponding software attach, or a regulatory rollback in European tunnel-safety mandates, would materially weaken the premium-vendor thesis.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.6% from 2020-2034 |
| Segmentation |
|
The market was valued at approximately USD 2.3 billion in 2025, with forecasts reaching USD 4.1 billion by 2033 at a 7.6% CAGR. An alternative estimate places the 2024 base at USD 1.9 billion, reflecting different scope definitions around system integration revenue.
North America leads with roughly 32% revenue share in 2025, driven by oil and gas, data center, and utility adoption. Asia Pacific is the fastest-growing region, fueled by metro, tunnel, and industrial infrastructure expansion.
Distributed Temperature Sensing (DTS) dominates, holding approximately 62% of 2024 revenue. It provides continuous long-distance temperature monitoring ideal for tunnels, pipelines, and cable trays, while DAS and FBG serve specialized multi-parameter and point-sensing roles.
Key vendors include AP Sensing, Halliburton (Sensornet), Siemens, Schneider Electric, Bandweaver Technologies, Luna Innovations, and Yokogawa. Competition is trust-driven, with proven deployments and integration capability mattering more than price.
Growth is driven by rising infrastructure investment in tunnels and metros, tightening fire-safety regulation in Europe and the Middle East, data-center uptime economics, and AI/IIoT integration reducing false alarms. High installation cost and skilled-labor scarcity remain key restraints.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split, with in-depth interviews conducted across the value chain: optical fiber and component suppliers, specialized sensing-system manufacturers, system integrators and EPC contractors, and global distributors. We engaged decision-makers including VP-level Sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads, capturing both procurement logic and technical deployment realities.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement | 30% |
| Heads of R&D | 25% |
| Technical Directors | 25% |
| Commercial Operations Leads | 20% |
| Company Type | Representation (%) |
|---|---|
| Optical Fiber & Component Suppliers | 30% |
| Sensing-System Manufacturers | 35% |
| System Integrators & EPCs | 20% |
| Global Distributors | 15% |
We triangulate against official multilateral sources including UN Comtrade, WTO trade statistics, US ITC data, and Eurostat; corporate annual filings (10-K, SEC disclosures, investor presentations); patent databases for technology-landscape mapping; and recognized technical standards bodies and industry associations relevant to fire safety and fiber sensing.
We run simultaneous Top-Down (macroeconomic and industry-segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption) models, reconciling divergences through a validation matrix before finalizing estimates.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
