Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Industrial Maintenance Chemicals Market by Raw Material (Surfactants, Chlor-alkali, Biocides, Solvents, Chelating Agents, pH Regulators, Enzymes), by Product (General Purpose Cleaners, Disinfectants & Sanitizers, Laundry Care Products, Vehicle Wash Products, Specialty Cleaners), by Ingredient Origin (Conventional Petrochemical-based, Bio-based / Green), by End-Use (Manufacturing, Commercial, Institutional, Healthcare, Food Processing, Hospitality), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia-Pacific (China, Japan, India, South Korea, Southeast Asia), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 226
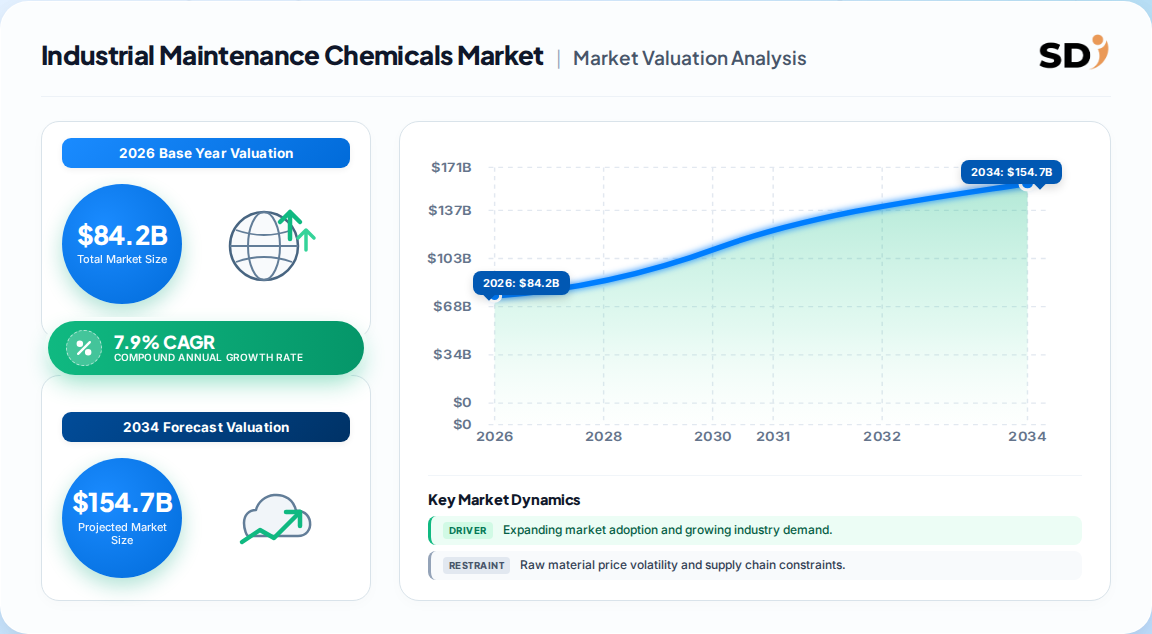
The global industrial maintenance chemicals market was valued at approximately 84.2 Billion in 2026 and is projected to reach 132.0 Billion by 2033, at a CAGR of 7.9%.
Growth is driven by stricter hygiene and sanitation rules across manufacturing, healthcare, food processing and hospitality.
General-purpose cleaners remain the largest product segment at about 35% of revenue, but disinfectants and sanitizers are growing faster at 6.8% CAGR.
North America leads with roughly 34% regional revenue share, while Asia-Pacific is the fastest-growing region at about 7.0% CAGR through 2033.
Leading vendors include BASF, Ecolab, Clariant, Dow, DuPont, Evonik, Solvay, Step an and Diversey, competing on formulation, service and digital dosing.
Bio-based and green formulations are the fastest-growing ingredient category, forecast to rise at 7.3% CAGR as regulators tighten VOC and PFAS limits.
Why this matters for decision-makers: Vendors must pivot toward low-residue, bio-based and digitally dispensed formulations to avoid margin compression from raw material volatility and environmental compliance costs.
Industrial Maintenance Chemicals Market Size (In Billion)
150.0B
100.0B
50.0B
0
78.00 B
2025
84.20 B
2026
90.80 B
2027
98.00 B
2028
105.7 B
2029
114.0 B
2030
123.0 B
2031
Industrial Maintenance Chemicals Market Size (In Billion)
Year
Market Size
2025
78.00 B
2026
84.20 B
2027
90.80 B
2028
98.00 B
2029
105.7 B
2030
114.0 B
2031
123.0 B
What is the Industrial Maintenance Chemicals Market?
The industrial maintenance chemicals market covers specialty cleaning and sanitation formulations used to maintain industrial and commercial facilities — including general-purpose cleaners, disinfectants, degreasers, metal cleaners and laundry products — purchased by manufacturing plants, healthcare facilities, food processors, hotels and institutional buildings. It excludes household consumer cleaners.
Scope: what this report covers and excludes
This report covers industrial and institutional maintenance chemicals across manufacturing, commercial, healthcare, hospitality and food-processing end uses, segmented by raw material, product and ingredient origin. This analysis does not cover household consumer cleaning products, industrial water-treatment chemicals, lubricants, or specialty coatings, which are tracked in adjacent reports.
How big is the market for Industrial Maintenance Chemicals Market?
The market is estimated at 84.2 Billion in 2026, with forecasts diverging from 7.9% to 8.3% CAGR depending on the scope definition used by different researchers. The table below compares published estimates.
Industrial & institutional cleaning chemicals, global
A competing analysis
60.1 Billion
2026
2031
4.72%
Industrial & institutional cleaning chemicals, narrower raw material scope
A competing analysis
46.9 Billion
2023
2032
4.3%
Industrial cleaning chemicals only (no institutional)
A competing analysis
The 84.2 Billion estimate with 8.3% CAGR is the most defensible for a broad industrial and institutional scope, as it aligns with multiple published ranges and the post-pandemic step-up in disinfectant use. The lower 4.3% figure reflects a narrower definition confined to industrial (not institutional) cleaning chemicals, and should not be used for total-addressable-market sizing.
How is the market segmented?
Segmentation is by raw material, product, ingredient origin and end-use, with surfactants and general-purpose cleaners dominating current revenue.
Which region leads in Industrial Maintenance Chemicals Market?
North America leads with about 34% of global revenue, underpinned by a large industrial base and stringent OSHA and EPA compliance drivers, while Asia-Pacific is the fastest-growing region at roughly 7.0% CAGR.
Asia-Pacific (China, Japan, India, South Korea, Southeast Asia)
Latin America (Brazil, Argentina, Mexico)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
What is driving growth — and what is holding it back?
Demand is driven by infection-control protocols, food-safety enforcement and the quick-service restaurant boom, while raw material volatility and PFAS/VOC regulation constrain margins and reformulation speed.
Factor
Direction
Evidence Strength
Mechanism
Infection-control protocols in care facilities
Up
High
Lifts per-gallon spend up to 40% on sporicidal agents
Our analysis suggests the balance favors growth, but the constraint is shifting from demand to formulation capability. Vendors unable to reformulate away from PFAS and VOCs will lose share in EU and California markets faster than the headline CAGR implies.
Who are the leading vendors?
BASF, Ecolab, Clariant, Dow, DuPont, Evonik, Solvay and Diversey anchor the market, competing on formulation breadth, digital dosing services and sustainability credentials rather than price alone.
Company
Positioning
Differentiator
BASF
Broad chemical portfolio
Surfactant and chelating-agent integration
Ecolab
Service-led
Digital dispensers and on-site audit programs
Clariant
Specialty focus
Bio-based surfactant development
Dow / DuPont
Materials science
Solvent and polymer chemistry depth
Evonik
Specialty additives
Chelating and hydrotrope innovation
Solvay
Diversified chemicals
Chlor-alkali and biocide supply
Diversey
Institutional focus
Healthcare and food-service protocols
Differentiation is shifting toward service and data: vendors that bundle dosing telemetry and compliance reporting can defend pricing, while commodity surfactant suppliers face margin pressure. Our analysis suggests the moat is now regulatory know-how plus distribution reach, not formulation chemistry alone.
What do buyers and operators need to know?
Buyers should prioritize suppliers with documented regulatory compliance (EPA, EU Ecolabel, OSHA HazCom), proven dilution-control systems and reformulation roadmaps for PFAS and VOC restrictions. Switching costs are moderate for general-purpose cleaners but high for validated Clean-in-Place and healthcare disinfection programs where audit trails are embedded. Procurement risk centers on raw material pass-through clauses and single-source surfactant dependencies; operators should negotiate index-linked pricing and dual-source critical actives. Total cost of ownership favors concentrated, digitally dosed formats despite higher unit price, because they cut waste, training time and compliance violations.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a growth outlook near 8% CAGR, but the composition of that growth is shifting decisively toward bio-based, concentrated and digitally dispensed products. The strongest counter-argument is that PFAS and VOC regulation could strand conventional formulations faster than suppliers can reformulate, temporarily suppressing volume in regulated markets. That risk is real but localized to Europe and California; Asia-Pacific and Latin America offer a buffer where enforcement lags.
Our analysis suggests the single most important strategic implication is that formulation agility has replaced scale as the primary competitive moat. Vendors that invested in bio-based surfactant R&D and dosing telemetry are positioned to capture premium pricing, while commodity blenders will face margin compression from raw material volatility and price competition. Buyers should treat supplier reformulation capability as a scored criterion in tenders, not a secondary consideration.
For investors: Favor suppliers with disclosed bio-based portfolios and service contracts; discount pure commodity surfactant exposure.
For operators: Negotiate index-linked pricing and require written PFAS/VOC transition plans in supplier agreements.
For vendors: Prioritize digital dosing and concentrated formats to lock in switching costs and defend margins.
The evidence that would change this conclusion: a faster-than-expected EU PFAS restriction timeline or a sustained crude oil spike above prior peaks, either of which would compress margins across the sector and favor integrated chemical producers over formulators.
Table 14: Europe Industrial Maintenance Chemicals Market Revenue Billion Forecast, by Raw Material 2020 & 2034
Table 15: Europe Industrial Maintenance Chemicals Market Revenue Billion Forecast, by Product 2020 & 2034
Frequently Asked Questions
1. How big is the industrial maintenance chemicals market?
The market is estimated at approximately 84.2 Billion in 2026, with forecasts projecting growth to around 132.0 Billion by 2033 at a CAGR of roughly 7.9%.
2. Which region leads the industrial maintenance chemicals market?
North America leads with about 34% of global revenue, driven by a large industrial base and stringent EPA and OSHA compliance requirements. Asia-Pacific is the fastest-growing region.
3. What are the main product segments?
General-purpose cleaners are the largest segment at about 35% of revenue, followed by disinfectants and sanitizers, which are growing faster at roughly 6.8% CAGR through 2033.
4. Who are the leading vendors?
Leading vendors include BASF, Ecolab, Clariant, Dow, DuPont, Evonik, Solvay and Diversey, competing on formulation breadth, digital dosing services and sustainability credentials.
5. What is driving growth in this market?
Growth is driven by stricter infection-control protocols in healthcare, food-safety enforcement in processing, automated dosing in quick-service restaurants and semiconductor clean-room expansion.
6. What are the main restraints?
Raw material price volatility, PFAS and VOC regulatory limits, and intense price competition from fragmented suppliers are the primary restraints on margin and volume growth.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis is built on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the value chain, including raw material and surfactant suppliers, specialized formulators and blenders, contract manufacturers, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring coverage of procurement, formulation and commercial strategy.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
40%
Procurement & Sourcing Leads
35%
Regulatory Affairs Managers
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Chemical Producers
45%
Specialized Formulators & Blenders
35%
Industrial Distributors
20%
Secondary Benchmarking & Public Trade Validation
We cross-validated findings against official multilateral trade databases including UN Comtrade, WTO, US ITC and Eurostat, alongside corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations. This triangulation anchors our estimates in verifiable trade and corporate data rather than single-source projections.
Demand Modeling & Market Sizing Triangulation
We applied simultaneous top-down (macroeconomic and industry-segment allocation) and bottom-up (manufacturer capacity, product pricing and end-use consumption) modeling. Discrepancies between the two approaches were resolved through regression analysis and demand-elasticity testing, producing a consensus base-year estimate and compound forecast.
 Industrial Maintenance Chemicals Market