 Fiber Laser Market
 Outlook 2026: Size, CAGR & Trends
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 242

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Fiber Laser Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2024 | 6.870 B |
| 2025 | 7.640 B |
| 2026 | 8.480 B |
| 2027 | 9.420 B |
| 2028 | 10.47 B |
| 2029 | 11.63 B |
| 2030 | 12.92 B |

The fiber laser market covers the manufacture and sale of rare-earth-doped optical-fiber gain-medium laser sources and the integrated cutting, welding, marking, and micromachining systems built around them. It spans infrared, ultrafast, ultraviolet, and visible architectures, sold as standalone resonators or embedded in automated production cells.
This analysis covers global fiber laser source and system revenue across laser type, power output, operation mode, and end-use industry. It includes both component-level resonators and integrated processing systems where the laser is the primary value driver. This analysis does not cover CO₂ or Nd:YAG legacy laser categories, directed-energy weapons programs, fiber-optic telecommunications transceivers, or general laser-diode components sold without fiber-laser integration.
Published estimates diverge materially — from USD 3.9 billion to USD 6.9 billion for 2024 — because definitions differ on whether system-level integration and aftermarket service revenue are counted. The following table reconciles the leading published estimates.
| Estimate (Base Yr) | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|
| USD 6.87 B (2024) | 2033 | 11.1% | Full source + integrated system revenue | One published estimate |
| USD 3.90 B (2025) | 2035 | 7.3% | Source-level resonators, narrower scope | Competing analysis |
| USD 4.94 B (2024) | 2035 | 12.2% | Type-segmented source and system revenue | Alternative published estimate |
Our analysis: the USD 6.87 billion figure is the most defensible for strategic planning because it captures integrated system value, which is where capital spending actually occurs. The narrower USD 3.9 billion figure better reflects the source-only TAM and explains much of the apparent CAGR gap — 7.3% versus 11.1%. Buyers budgeting system-level procurement should anchor to the higher figure.
The market segments along four non-geographic axes that materially change pricing, competitive dynamics, and buyer requirements.
| Parent Segment | Children | 2024 Share / Growth Signal |
|---|---|---|
| By Laser Type | Infrared, Ultrafast, Ultraviolet, Visible | Infrared ~42–59%; Ultrafast fastest (~13.7% CAGR) |
| By Power Output | Low (<100 W), Medium (100 W–1 kW), High (≥1 kW) | High power ~48% of revenue |
| By Operation Mode | Continuous Wave (CW), Pulsed, QCW | CW ~51% |
| By End Use | Automotive & E-Mobility, Electronics & Semiconductor, Metal Processing, Medical, Aerospace & Defense | Automotive highest-growth end-use |
So what: segment mix dictates margin. Standard CW in mid-power ranges is price-compressed; high-power, ultrafast, and application-engineered solutions retain pricing power.
Asia-Pacific leads the global fiber laser market with roughly 45% of 2024 revenue, driven by China's dominance in laser cutting equipment production and rapid industrial automation adoption across India and Southeast Asia.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.45% |
| North America | 0.27% |
| Europe | 0.21% |
| South America | 0.04% |
| Middle East & Africa | 0.03% |
North America's strength lies in precision and aerospace-grade applications; Europe leads in high-end automotive and industrial automation. Latin America and MEA are fastest-growing from a small base as high-power cutting systems penetrate industrializing markets.
Growth is anchored by EV and battery manufacturing, semiconductor fab capex, and technology displacement of CO₂ and Nd:YAG platforms — offset by Chinese price pressure and the capital intensity of high-power systems.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| EV & battery production | Driver | High | Battery tab welding, hairpin stators, busbars require stable high-power CW/QCW |
| Semiconductor fab capex | Driver | High | Ultrafast sources for wafer dicing, microvia drilling, advanced packaging |
| CO₂ / solid-state displacement | Driver | High | Superior wall-plug efficiency and sealed-resonator maintenance economics |
| Chinese price competition | Restraint | High | Margin compression in commodity CW; Raycus revenue fell 13.11% in 2024 despite unit growth |
| Capital cost of ≥10 kW systems | Restraint | Medium | USD 200,000+ per installation limits adoption in cost-sensitive markets |
| Thermal / nonlinear limits | Restraint | Medium | Stimulated Brillouin scattering caps beam-quality scaling above ~10 kW CW |
Balance of evidence: the structural drivers — EV, semiconductors, and legacy displacement — are durable and multi-year. Price pressure is concentrated in standard product classes and, crucially, does not afflict high-power and ultrafast where engineering differentiation holds. The net trajectory is strong volume growth with bifurcated margins.
The top five suppliers hold roughly 50% of global revenue, with IPG Photonics leading at approximately 20.5% share in 2025.
| Vendor | HQ | Position / Moat |
|---|---|---|
| IPG Photonics | USA | Vertical integration in fiber components; ~20.5% share |
| Raycus Fiber Laser | China | Cost leadership; domestic component ecosystem |
| Coherent Corp | USA | Broad portfolio; 20 kW dual-ring beam innovation (ARM FL20D) |
| Maxphotonics | China | Volume CW and mid-power positioning |
| TRUMPF | Germany | High-end system integration and automation |
| Han's Laser | China | Integrated cutting systems and regional distribution |
Differentiation: Western vendors compete on beam quality, application engineering, and after-sales service; Chinese vendors compete on price and supply scale. Regional distribution partnerships — such as Eagle Lasers and Cuttech in India — are emerging as a competitive lever in growth markets.
Selection decisions hinge on more than source price. Buyers should evaluate wall-plug efficiency, beam-parameter-product stability at operating power, thermal-management headroom, and integration compatibility with robotic and CNC cells. For EV and semiconductor applications, process repeatability and weld consistency outweigh initial source cost.
Procurement risk concentrates in commodity CW and mid-power nanosecond segments, where rapid price erosion can strand existing installed bases and complicate residual-value assumptions. Switching costs are moderate at the source level but high at the system-integration level due to optics, cooling, safety controls, and factory-acceptance testing. Buyers should favor vendors with regional service infrastructure.
Regulatory compliance — laser safety classes, CE/IEC 60825, and regional machine directives — is non-negotiable and should be validated during tender, not post-installation. Total cost of ownership modeling over a 7–10 year horizon, not sticker price, is the correct basis for comparison.
The balance of evidence favors a bifurcated market thesis: aggregate growth remains robust at high single to low double digits, but value is migrating rapidly from commodity CW sources toward high-power, ultrafast, and application-engineered systems. Vendors anchored purely in mid-power standard products face structural margin compression; those with differentiated beam shaping, ultrafast capability, or deep application engineering retain pricing power.
The strongest counter-argument is that Chinese manufacturers will rapidly climb the value chain, replicating high-power and ultrafast capability at lower cost and compressing margins across the board. This is plausible — Raycus and Maxphotonics already ship high-power sources — but the engineering barriers at ultra-high output (SBG, thermal lensing) and the qualification cycles in EV and semiconductor production create durable, if narrowing, moats.
Actionable strategy:
What would change our conclusion: sustained evidence that Chinese suppliers achieve qualified ultrafast performance at scale, or a sharp contraction in EV and semiconductor capex, would materially alter the growth and margin trajectory. Precise sub-segment forecasting requires the full report's bottom-up model.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.1% from 2020-2034 |
| Segmentation |
|
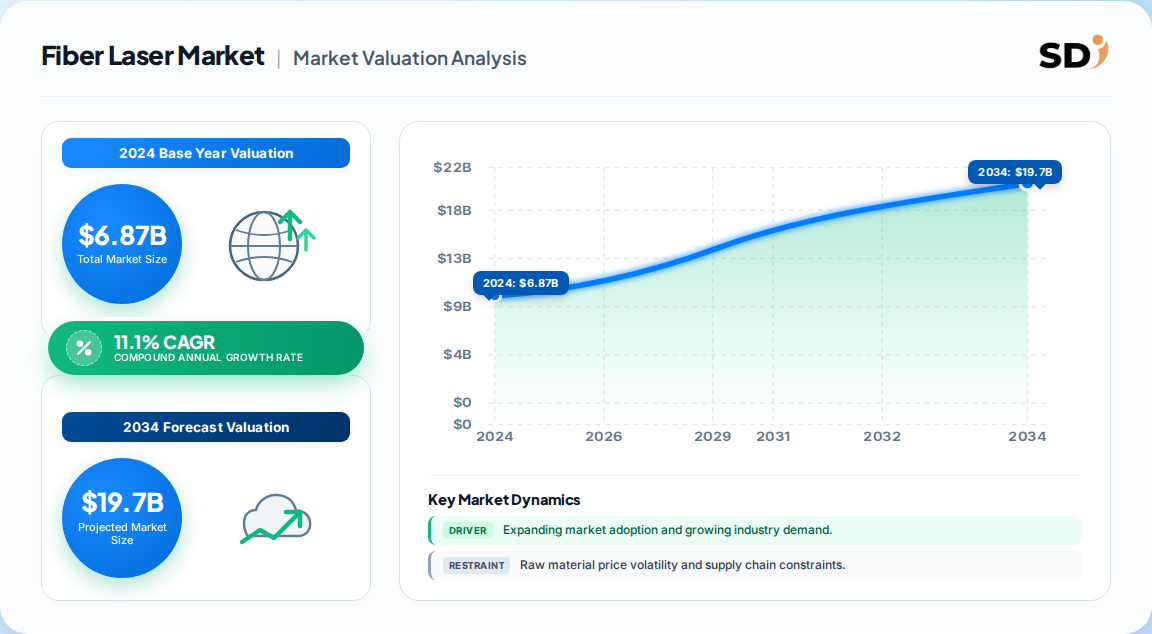
The global fiber laser market was estimated at roughly USD 6.87 billion in 2024, with 2025 estimated near USD 7.6 billion and a projected USD 17.55 billion by 2033 at an 11.1% CAGR. Estimates vary by scope definition.
Asia-Pacific leads with roughly 45% of global revenue, driven by China's laser cutting equipment production and rapid industrial automation. North America and Europe follow on precision-manufacturing and high-end automotive demand.
Ultrafast fiber lasers are the fastest-growing type segment at approximately 13–14% annual growth, driven by semiconductor wafer dicing, microvia drilling, and medical-device micromachining where thermal damage must be minimized.
IPG Photonics leads with roughly 20.5% share, followed by Raycus, Coherent, Maxphotonics, and TRUMPF. Together the top five hold approximately 50% of global revenue.
Intensifying Chinese price competition in standard CW products is compressing margins, while the capital cost of high-power systems and thermal/nonlinear barriers above ~10 kW constrain adoption at the highest-value end.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct stakeholder engagement. In-depth interviews were conducted across the fiber laser value chain — rare-earth-doped fiber and optical component suppliers, specialized laser source producers, integrated cutting and welding system OEMs, and global industrial distributors. Within these organizations we engaged decision-makers including VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads, capturing both technical specification requirements and commercial procurement dynamics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial & Operations Heads | 25% |
| Company Type | Representation (%) |
|---|---|
| Laser Source & Component Producers | 45% |
| Integrated System OEMs | 35% |
| Distributors & Automation Integrators | 20% |
Findings were benchmarked against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies including IEC and ISO laser-safety committees. These sources validated shipment volumes, pricing trajectories, and technology-roadmap signals.
We run simultaneous Top-Down modeling (macroeconomic industrial capex allocation across manufacturing segments) and Bottom-Up modeling (manufacturer capacity, average selling prices, and end-use consumption). Divergences are reconciled through segment-level elasticity analysis, producing a single defensible base-year value and compound forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |