Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Metal Feeler Gauge Market: Size, Trends & Forecast 2025
Metal Feeler Gauge Market: Size, Trends & Forecast 2025
Metal Feeler Gauge Market
Metal Feeler Gauge Market: Size, Trends & Forecast 2025
Metal Feeler Gauge Market by Gauge Type (Flat/Straight Leaf, Round, Tapered, Offset, Go/No-Go), by Material (Carbon Steel, Stainless Steel, Brass, Alloy Steel), by Application (Automotive Maintenance, Industrial Machinery, Aerospace Engineering, Tool & Die, Electronics Assembly, Construction), by Measurement Range (0.001-0.05 mm, 0.05-0.5 mm, 0.5-1 mm, Above 1 mm), by Distribution Channel (Direct Sales, Industrial Distributors, Online Retail), by End User (Professionals, Students, DIY Enthusiasts), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 258
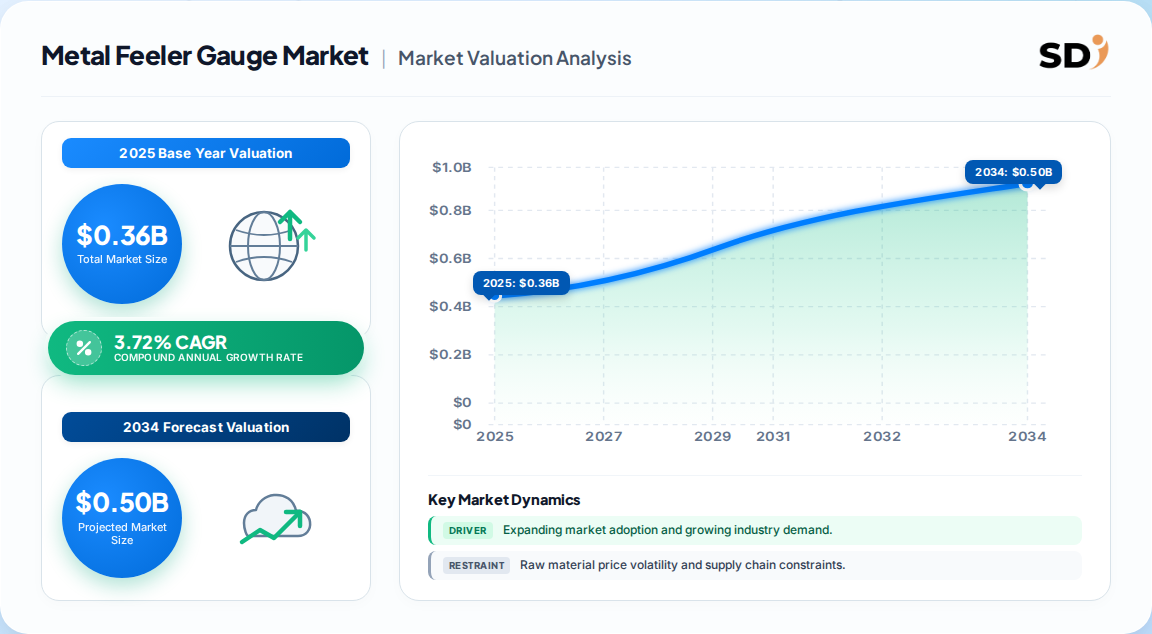
The global metal feeler gauge market was valued at approximately 0.36 Billion in 2025 and is forecast to reach 0.52 Billion by 2035, a steady but modest expansion path.
Consensus growth runs at a 3.72% CAGR (2025–2035); competing estimates cluster between 3.1% and 4.62%, a spread that signals definitional rather than demand divergence.
Flat/straight leaf gauges remain the volume anchor (roughly 43% of product-type revenue), while round and Go/No-Go formats are the fastest-growing variants.
Asia-Pacific leads regional revenue on the back of Chinese, Japanese, Indian and South Korean manufacturing depth; Europe is the fastest-growing region on automotive and machinery investment.
Steel (carbon and stainless) accounts for over 70% of material revenue, with stainless gaining share on corrosion and durability requirements.
Leading vendors include Starrett, Mitutoyo, Brown & Sharpe, FACOM, Baker Gauges, Precision Brand Products, GEDORE and Accu-Tool, alongside a long tail of regional precision-tool makers.
Why this matters for decision-makers: the market is fragmented and low-differentiation, so margin defense depends on moving up the value chain—calibration services, certified gauge sets and digital-hybrid formats—rather than competing on unit price.
Metal Feeler Gauge Market Size (In Million)
500.0M
400.0M
300.0M
200.0M
100.0M
0
350.0 M
2024
360.0 M
2025
370.0 M
2026
380.0 M
2027
400.0 M
2028
410.0 M
2029
430.0 M
2030
Metal Feeler Gauge Market Size (In Million)
Year
Market Size
2024
350.0 M
2025
360.0 M
2026
370.0 M
2027
380.0 M
2028
400.0 M
2029
410.0 M
2030
430.0 M
What is the Metal Feeler Gauge Market?
The metal feeler gauge market covers thin, precision-ground metal strips—mounted in leaf sets or supplied as individual blades—used to measure small gaps and clearances in engines, bearings and mechanical assemblies. Demand is driven by automotive maintenance, industrial machinery, aerospace and electronics inspection, where accurate clearance verification underpins quality and safety compliance.
Scope: what this report covers and excludes
This report covers metal feeler gauges across product type (straight leaf, tapered, offset, round, Go/No-Go), material (carbon steel, stainless steel, brass, alloy steel), application (automotive maintenance, industrial machinery, aerospace, tool and die, electronics assembly) and distribution channel (direct, industrial distributors, online retail). This analysis does not cover digital calipers, micrometers, bore gauges, or plastic/composite feeler gauges as separate markets, though they are referenced as adjacent or substitution threats where relevant.
How big is the market for Metal Feeler Gauge Market?
The most defensible base-year reading is roughly 0.36 Billion in 2025, growing toward 0.52 Billion by 2035 at about 3.72% CAGR—but the published estimates diverge materially on both absolute size and growth rate, so buyers should anchor to the definitional scope before comparing figures.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 0.35 Bn → 0.52 Bn
2024
2035
3.72%
Broad metal feeler gauges, all end users
One published estimate
USD 311.4 Mn → 488.95 Mn
2025
2035
4.62%
Metal strips for gap/clearance, industrial focus
A competing analysis
USD 95.5 Mn (2023) → 118.1 Mn
2023
2030
3.1%
Steel/brass, narrower product definition
A third published estimate
The widest gap—roughly 3x between the low and high absolute figures—is almost entirely a scope artifact, not a demand disagreement. The narrowest estimate appears to exclude lower-volume tapered and offset variants and some aftermarket channels, while the higher figures fold in broader industrial distribution. Our analysis suggests the ~0.36 Billion / 3.72% path is the most balanced anchor for procurement planning, because its definitional breadth matches how buyers actually source these tools: as part of a wider precision-measurement basket rather than a standalone category.
How is the market segmented?
Segmentation is best read along four axes—product type, material, application and measurement range—with the first two doing most of the commercial work in purchasing decisions.
Direct sales, Industrial distributors, Online retail
By End User
Professionals, Students, DIY enthusiasts
Straight-leaf gauges dominate because their parallel blades prevent parts from sliding during measurement—a practical preference among machinists that pricing alone cannot dislodge. The faster-growing round and Go/No-Go formats reflect a second-order shift: as inspection workflows get standardized, buyers prefer pass/fail tools that reduce operator judgment and training burden.
Which region leads in Metal Feeler Gauge Market?
Asia-Pacific generates the largest revenue in the metal feeler gauge market, anchored by China, Japan, India and South Korea's manufacturing depth, while Europe is the fastest-growing region on automotive and precision-engineering investment.
Metal Feeler Gauge Market Regional Market Share
Loading chart...
Metal Feeler Gauge Market Regional Market Share
Region
Market Share (%)
North America
0.24%
Europe
0.23%
Asia-Pacific
0.39%
South America
0.07%
Middle East & Africa
0.07%
Asia-Pacific — China, Japan, India, South Korea (largest revenue base; domestic gauge makers such as Mitutoyo and Kanon)
North America — USA, Canada, Mexico (mature, quality-driven demand; ~24% share)
Europe — Germany, UK, France, Italy (fastest growth; FACOM, GEDORE, Hasberg-Schneider presence)
Latin America — Brazil, Mexico, Argentina (developing industrial demand)
Middle East & Africa — Saudi Arabia, UAE, South Africa (infrastructure-led, smaller base)
The Asia-Pacific lead is structural, not cyclical: it tracks the concentration of automotive and electronics production, which is where feeler gauges are consumed most intensively. Europe's faster growth rate, by contrast, is a quality story—advanced automotive and machinery sectors replacing worn toolkits and tightening inspection standards. This divergence implies vendors should treat Asia-Pacific as a volume game and Europe as a margin game, tailoring product certification and service bundles accordingly.
What is driving growth — and what is holding it back?
Growth is driven by quality-assurance mandates and manufacturing expansion, while restraint comes from product commoditization and substitution by digital measurement tools.
Valve, spark-plug and assembly clearance verification
Stainless-steel durability demand
Driver
Medium
Longer tool life, corrosion resistance in workshops
Digital/hybrid substitution
Restraint
Medium
Calipers and digital gap tools erode simple-use cases
Commoditization & price competition
Restraint
High
Low differentiation compresses unit margins
Maintenance budget cyclicality
Restraint
Medium
Downturns defer tool replacement
The balance of evidence favors steady rather than explosive growth. The strongest drivers—quality assurance and manufacturing expansion—are structural and unlikely to reverse, but they operate on a mature, low-ticket product where growth is inherently incremental. The substitution threat from digital tools is real but bounded: feeler gauges remain the cheapest, fastest way to check a physical gap, and no digital alternative matches that at the price point. Our analysis suggests the net effect is a reliable low-to-mid single-digit CAGR rather than disruption in either direction.
Who are the leading vendors?
The market is fragmented, with a handful of global precision-tool brands competing alongside many regional gauge specialists.
Company
HQ
Positioning
Starrett
US
Broad precision-tool portfolio, brand trust
Mitutoyo
Japan
Metrology leader, deep distribution
Brown & Sharpe
US
Heritage measurement brand
FACOM
France
Professional hand-tool channel strength
GEDORE
Germany
Industrial tooling, European reach
Baker Gauges
India
Regional gauge specialist, cost position
Precision Brand Products
US
Shim and gauge focus
Accu-Tool
US
Niche precision tooling
Differentiation rests less on gauge design—which is largely standardized—and more on three moats: distribution reach (Mitutoyo and FACOM win on channel access), brand trust in regulated inspection (Starrett and Brown & Sharpe), and cost position in regional markets (Baker Gauges). This implies new entrants should compete on service, certification and bundling rather than trying to out-engineer incumbents on the blade itself.
What do buyers and operators need to know?
Buyers should prioritize certification and traceability over unit price. A feeler gauge that lacks documented thickness tolerance is a liability in regulated inspection, and the cost of a failed audit dwarfs the savings from a cheaper set. Procurement teams should request calibration certificates and material grade confirmation as standard.
Switching costs are low at the product level but high at the workflow level. Once a plant standardizes on a gauge format, blade thickness set and inspection protocol, changing suppliers means retraining operators and revalidating procedures—so the real lock-in is procedural, not contractual. Buyers should therefore evaluate suppliers on consistency of supply and documentation, not just initial quote.
Regulatory exposure is moderate but real. Legal metrology frameworks—such as India's Legal Metrology system—and industry quality standards impose accuracy and testing obligations on measuring instruments. Operators in automotive and aerospace supply chains should confirm gauge tolerances align with their customer's inspection requirements before adopting a new vendor. Finally, watch the digital-hybrid frontier: suppliers offering gauges paired with digital readout or calibration apps are positioning for the next procurement cycle, and early adoption may reduce long-run inspection costs.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a quality-and-service differentiation strategy over volume competition. The metal feeler gauge market is growing steadily at ~3.7% and is structurally fragmented, which means price wars are easy to start and hard to win. The vendors that will outperform are those that bundle gauges with calibration, certification and inspection workflow support—capturing the buyer's procedural lock-in rather than fighting over blade margins.
The strongest counter-argument is that digital measurement tools will compress the category faster than expected, making service investment a poor bet. That view has merit at the high end of precision measurement, but it underestimates the durability of the low-cost physical gap check. For the foreseeable forecast horizon, feeler gauges remain the default tool in workshops and service centers, and digital substitution is incremental rather than disruptive.
Actionable strategy:
For suppliers: invest in certified gauge sets and calibration services to escape commoditization and defend margins in Europe and North America.
For distributors: build regional inventory depth in Asia-Pacific to capture volume, while offering premium certified lines in Europe for margin.
For buyers: standardize on stainless-steel gauges with documented tolerances to reduce replacement frequency and audit risk.
What would change this conclusion: a step-change in low-cost digital gap sensors priced below traditional gauge sets, or a sharp contraction in automotive maintenance spending. Absent either, the steady-growth, service-differentiation thesis holds—and the full report provides the segment-level forecasting and vendor benchmarking needed to execute against it.
Metal Feeler Gauge Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Metal Feeler Gauge Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3.72% from 2020-2034
Segmentation
By Gauge Type
Flat/Straight Leaf
Round
Tapered
Offset
Go/No-Go
By Material
Carbon Steel
Stainless Steel
Brass
Alloy Steel
By Application
Automotive Maintenance
Industrial Machinery
Aerospace Engineering
Tool & Die
Electronics Assembly
Construction
By Measurement Range
0.001-0.05 mm
0.05-0.5 mm
0.5-1 mm
Above 1 mm
By Distribution Channel
Direct Sales
Industrial Distributors
Online Retail
By End User
Professionals
Students
DIY Enthusiasts
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Gauge Type
5.1.1. Flat/Straight Leaf
5.1.2. Round
5.1.3. Tapered
5.1.4. Offset
5.1.5. Go/No-Go
5.2. Market Analysis, Insights and Forecast - by Material
5.2.1. Carbon Steel
5.2.2. Stainless Steel
5.2.3. Brass
5.2.4. Alloy Steel
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Automotive Maintenance
5.3.2. Industrial Machinery
5.3.3. Aerospace Engineering
5.3.4. Tool & Die
5.3.5. Electronics Assembly
5.3.6. Construction
5.4. Market Analysis, Insights and Forecast - by Measurement Range
5.4.1. 0.001-0.05 mm
5.4.2. 0.05-0.5 mm
5.4.3. 0.5-1 mm
5.4.4. Above 1 mm
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Direct Sales
5.5.2. Industrial Distributors
5.5.3. Online Retail
5.6. Market Analysis, Insights and Forecast - by End User
5.6.1. Professionals
5.6.2. Students
5.6.3. DIY Enthusiasts
5.7. Market Analysis, Insights and Forecast - by Region
5.7.1. North America
5.7.2. Europe
5.7.3. Asia Pacific
5.7.4. Latin America
5.7.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Gauge Type
6.1.1. Flat/Straight Leaf
6.1.2. Round
6.1.3. Tapered
6.1.4. Offset
6.1.5. Go/No-Go
6.2. Market Analysis, Insights and Forecast - by Material
6.2.1. Carbon Steel
6.2.2. Stainless Steel
6.2.3. Brass
6.2.4. Alloy Steel
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Automotive Maintenance
6.3.2. Industrial Machinery
6.3.3. Aerospace Engineering
6.3.4. Tool & Die
6.3.5. Electronics Assembly
6.3.6. Construction
6.4. Market Analysis, Insights and Forecast - by Measurement Range
6.4.1. 0.001-0.05 mm
6.4.2. 0.05-0.5 mm
6.4.3. 0.5-1 mm
6.4.4. Above 1 mm
6.5. Market Analysis, Insights and Forecast - by Distribution Channel
6.5.1. Direct Sales
6.5.2. Industrial Distributors
6.5.3. Online Retail
6.6. Market Analysis, Insights and Forecast - by End User
6.6.1. Professionals
6.6.2. Students
6.6.3. DIY Enthusiasts
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Gauge Type
7.1.1. Flat/Straight Leaf
7.1.2. Round
7.1.3. Tapered
7.1.4. Offset
7.1.5. Go/No-Go
7.2. Market Analysis, Insights and Forecast - by Material
7.2.1. Carbon Steel
7.2.2. Stainless Steel
7.2.3. Brass
7.2.4. Alloy Steel
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Automotive Maintenance
7.3.2. Industrial Machinery
7.3.3. Aerospace Engineering
7.3.4. Tool & Die
7.3.5. Electronics Assembly
7.3.6. Construction
7.4. Market Analysis, Insights and Forecast - by Measurement Range
7.4.1. 0.001-0.05 mm
7.4.2. 0.05-0.5 mm
7.4.3. 0.5-1 mm
7.4.4. Above 1 mm
7.5. Market Analysis, Insights and Forecast - by Distribution Channel
7.5.1. Direct Sales
7.5.2. Industrial Distributors
7.5.3. Online Retail
7.6. Market Analysis, Insights and Forecast - by End User
7.6.1. Professionals
7.6.2. Students
7.6.3. DIY Enthusiasts
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Gauge Type
8.1.1. Flat/Straight Leaf
8.1.2. Round
8.1.3. Tapered
8.1.4. Offset
8.1.5. Go/No-Go
8.2. Market Analysis, Insights and Forecast - by Material
8.2.1. Carbon Steel
8.2.2. Stainless Steel
8.2.3. Brass
8.2.4. Alloy Steel
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Automotive Maintenance
8.3.2. Industrial Machinery
8.3.3. Aerospace Engineering
8.3.4. Tool & Die
8.3.5. Electronics Assembly
8.3.6. Construction
8.4. Market Analysis, Insights and Forecast - by Measurement Range
8.4.1. 0.001-0.05 mm
8.4.2. 0.05-0.5 mm
8.4.3. 0.5-1 mm
8.4.4. Above 1 mm
8.5. Market Analysis, Insights and Forecast - by Distribution Channel
8.5.1. Direct Sales
8.5.2. Industrial Distributors
8.5.3. Online Retail
8.6. Market Analysis, Insights and Forecast - by End User
8.6.1. Professionals
8.6.2. Students
8.6.3. DIY Enthusiasts
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Gauge Type
9.1.1. Flat/Straight Leaf
9.1.2. Round
9.1.3. Tapered
9.1.4. Offset
9.1.5. Go/No-Go
9.2. Market Analysis, Insights and Forecast - by Material
9.2.1. Carbon Steel
9.2.2. Stainless Steel
9.2.3. Brass
9.2.4. Alloy Steel
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Automotive Maintenance
9.3.2. Industrial Machinery
9.3.3. Aerospace Engineering
9.3.4. Tool & Die
9.3.5. Electronics Assembly
9.3.6. Construction
9.4. Market Analysis, Insights and Forecast - by Measurement Range
9.4.1. 0.001-0.05 mm
9.4.2. 0.05-0.5 mm
9.4.3. 0.5-1 mm
9.4.4. Above 1 mm
9.5. Market Analysis, Insights and Forecast - by Distribution Channel
9.5.1. Direct Sales
9.5.2. Industrial Distributors
9.5.3. Online Retail
9.6. Market Analysis, Insights and Forecast - by End User
9.6.1. Professionals
9.6.2. Students
9.6.3. DIY Enthusiasts
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Gauge Type
10.1.1. Flat/Straight Leaf
10.1.2. Round
10.1.3. Tapered
10.1.4. Offset
10.1.5. Go/No-Go
10.2. Market Analysis, Insights and Forecast - by Material
10.2.1. Carbon Steel
10.2.2. Stainless Steel
10.2.3. Brass
10.2.4. Alloy Steel
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Automotive Maintenance
10.3.2. Industrial Machinery
10.3.3. Aerospace Engineering
10.3.4. Tool & Die
10.3.5. Electronics Assembly
10.3.6. Construction
10.4. Market Analysis, Insights and Forecast - by Measurement Range
10.4.1. 0.001-0.05 mm
10.4.2. 0.05-0.5 mm
10.4.3. 0.5-1 mm
10.4.4. Above 1 mm
10.5. Market Analysis, Insights and Forecast - by Distribution Channel
10.5.1. Direct Sales
10.5.2. Industrial Distributors
10.5.3. Online Retail
10.6. Market Analysis, Insights and Forecast - by End User
10.6.1. Professionals
10.6.2. Students
10.6.3. DIY Enthusiasts
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Metal Feeler Gauge Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Metal Feeler Gauge Market Revenue (Billion), by Gauge Type 2026 & 2034
Figure 3: North America Metal Feeler Gauge Market Revenue Share (%), by Gauge Type 2026 & 2034
Figure 4: North America Metal Feeler Gauge Market Revenue (Billion), by Material 2026 & 2034
Figure 5: North America Metal Feeler Gauge Market Revenue Share (%), by Material 2026 & 2034
Figure 6: North America Metal Feeler Gauge Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Metal Feeler Gauge Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Metal Feeler Gauge Market Revenue (Billion), by Measurement Range 2026 & 2034
Figure 9: North America Metal Feeler Gauge Market Revenue Share (%), by Measurement Range 2026 & 2034
Figure 10: North America Metal Feeler Gauge Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 11: North America Metal Feeler Gauge Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 12: North America Metal Feeler Gauge Market Revenue (Billion), by End User 2026 & 2034
Figure 13: North America Metal Feeler Gauge Market Revenue Share (%), by End User 2026 & 2034
Figure 14: North America Metal Feeler Gauge Market Revenue (Billion), by Country 2026 & 2034
Figure 15: North America Metal Feeler Gauge Market Revenue Share (%), by Country 2026 & 2034
Figure 16: Europe Metal Feeler Gauge Market Revenue (Billion), by Gauge Type 2026 & 2034
List of Tables
Table 1: Metal Feeler Gauge Market Revenue Billion Forecast, by Gauge Type 2020 & 2034
Table 2: Metal Feeler Gauge Market Revenue Billion Forecast, by Material 2020 & 2034
Table 3: Metal Feeler Gauge Market Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Metal Feeler Gauge Market Revenue Billion Forecast, by Measurement Range 2020 & 2034
Table 5: Metal Feeler Gauge Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 6: Metal Feeler Gauge Market Revenue Billion Forecast, by End User 2020 & 2034
Table 7: Metal Feeler Gauge Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: North America Metal Feeler Gauge Market Revenue Billion Forecast, by Gauge Type 2020 & 2034
Table 9: North America Metal Feeler Gauge Market Revenue Billion Forecast, by Material 2020 & 2034
Table 10: North America Metal Feeler Gauge Market Revenue Billion Forecast, by Application 2020 & 2034
Table 11: North America Metal Feeler Gauge Market Revenue Billion Forecast, by Measurement Range 2020 & 2034
Table 12: North America Metal Feeler Gauge Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 13: North America Metal Feeler Gauge Market Revenue Billion Forecast, by End User 2020 & 2034
Table 14: North America Metal Feeler Gauge Market Revenue Billion Forecast, by Country 2020 & 2034
Table 15: USA Metal Feeler Gauge Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Canada Metal Feeler Gauge Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the metal feeler gauge market?
The global metal feeler gauge market was valued at approximately 0.36 Billion in 2025 and is forecast to reach about 0.52 Billion by 2035, growing at roughly 3.72% CAGR over the period.
2. Which region leads the metal feeler gauge market?
Asia-Pacific generates the largest revenue, driven by manufacturing depth in China, Japan, India and South Korea. Europe is the fastest-growing region on automotive and precision-engineering investment.
3. What are the main types of metal feeler gauges?
The main types are flat or straight leaf, round, tapered, offset and Go/No-Go gauges. Straight-leaf gauges hold the largest share, while round and Go/No-Go formats are growing fastest.
4. Who are the leading metal feeler gauge manufacturers?
Leading vendors include Starrett, Mitutoyo, Brown & Sharpe, FACOM, GEDORE, Baker Gauges, Precision Brand Products and Accu-Tool, alongside many regional precision-tool specialists.
5. What is driving demand for metal feeler gauges?
Demand is driven by quality-assurance requirements, manufacturing expansion, automotive and aerospace production, and the need for reliable clearance verification in maintenance and assembly operations.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study follows a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain with raw material suppliers (gauge steel and brass stock), specialized gauge producers, contract manufacturers, and global and regional industrial distributors. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of R&D and product engineering, Technical Directors responsible for inspection standards, and Commercial Operations Leads managing distribution. Interviews focused on capacity, pricing, certification practices, and procurement cycles.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Sourcing & Procurement Leads
35%
R&D & Product Engineering Heads
30%
Technical & Inspection Directors
25%
Commercial Operations Leads
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Gauge Steel & Raw Material Suppliers
25%
Specialized Gauge Producers
40%
Industrial Distributors
25%
Online & Retail Channels
10%
Secondary Benchmarking & Public Trade Validation
Findings were benchmarked against official multilateral trade and standards databases, including UN Comtrade, WTO trade statistics, US ITC data and Eurostat, supplemented by corporate annual filings (10-K and SEC filings), investor presentations, patent databases, and recognized non-profit technical standards and industry associations. No third-party market-research publications were used as source benchmarks.
Demand Modeling & Market Sizing Triangulation
Market sizing combined simultaneous Top-Down allocation (macroeconomic and industry-segment demand) with Bottom-Up modeling of manufacturer capacity, product pricing and end-use consumption. The two approaches were reconciled to produce a single base-year valuation and compound forecast path.
 Metal Feeler Gauge Market