 Glass Reinforced Substrate Market
 Outlook 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 193

Khageshwar Rongkali

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Glass Reinforced Substrate Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2026 | 1.230 B |
| 2027 | 1.280 B |
| 2028 | 1.330 B |
| 2029 | 1.390 B |
| 2030 | 1.440 B |
| 2031 | 1.500 B |
| 2032 | 1.570 B |

The glass reinforced substrate market covers engineered laminates and composite base materials in which woven or non-woven glass fibre fabric is impregnated with a thermoset or thermoplastic resin, then cured, clad or cut into sheets. These sheets form the structural and dielectric foundation of PCBs, IC packages, RF modules and power electronics.
This report covers glass fibre-reinforced organic substrates only: epoxy laminates (including FR-4 and high-Tg grades), BT resin, polyimide, cyanate ester and PTFE laminates, supplied as prepreg, copper-clad laminate or unclad core across all thickness bands. Coverage spans PCB, IC packaging, RF/microwave, automotive module and display applications.
This analysis does not cover bare glass fibre or yarn as a standalone commodity, silicon or ceramic interposers, flexible polyimide film without glass reinforcement, solder mask and photoimageable dielectric chemistries, or finished PCB fabrication services. Adjacent packaging materials are referenced only where they substitute directly for glass-reinforced cores.
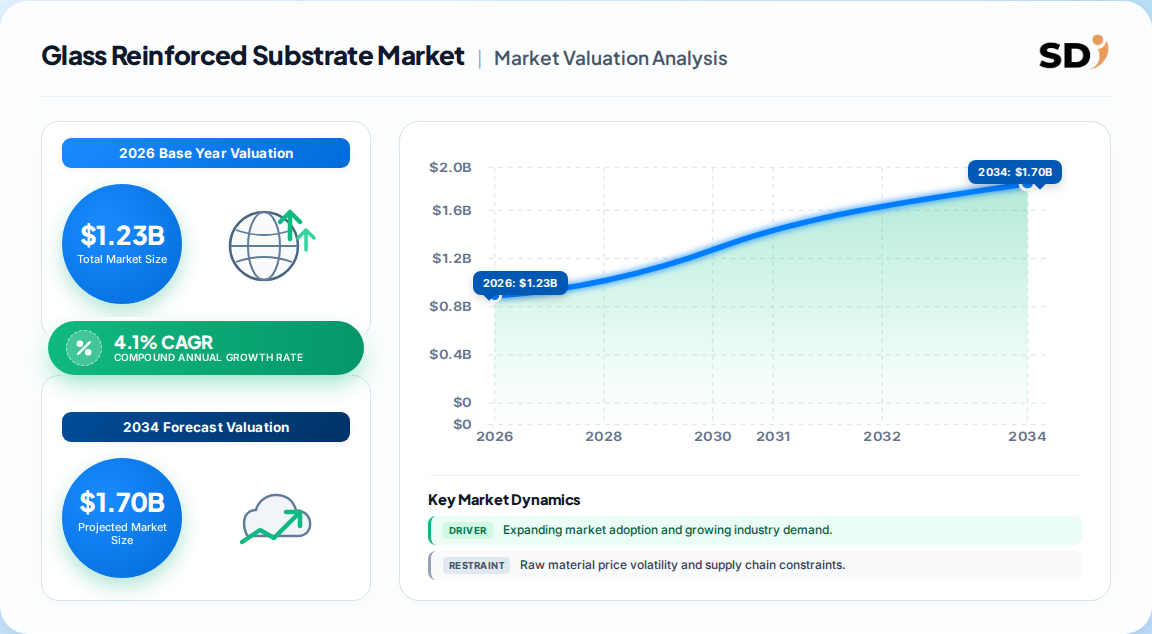
The market was worth roughly USD 1.18 Billion in 2025 and USD 1.23 Billion in 2026, with forecasts converging on USD 1.69–1.74 Billion by 2034–2035 — a consensus CAGR of about 4.0%.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.18 B → USD 1.69 B | 2025 | 2034 | 4.1% | Glass-reinforced laminates and CCL for electronics | One published estimate |
| USD 1.18 B → USD 1.75 B | 2025 | 2032 | 5.8% | Same product scope, shorter window, more bullish demand | A competing analysis |
| USD 1.2 B → USD 1.6 B | 2026 | 2033 | 3.8% | Electronic substrate grades only | A competing analysis |
| USD 1.18 B → USD 1.74 B | 2025 | 2035 | 4.0% | Laminates, prepreg and CCL | A competing analysis |
| USD 4.2 B → USD 7.0 B | 2024 | 2030 | 8.1% | Broad advanced-composites basket, wider than electronic substrates | A competing analysis |
Our analysis suggests the cluster around USD 1.18 Billion in 2025 and 3.8–4.1% CAGR is the defensible range: four independent scopes converge on it. The 8.1% figure is almost certainly measuring a wider composite materials basket and should be treated as an upper-bound outlier. The 5.8% case is directionally credible but leans on an optimistic 5G/EV ramp within a compressed horizon.
Segmentation runs along four non-geographic axes — product chemistry, application, thickness band and end-use industry — and each axis tells a different growth story.
| Parent segment | Children | 2025 position | Growth signal |
|---|---|---|---|
| Product type | Epoxy laminates, BT resin, Polyimide, Cyanate ester, PTFE | Epoxy dominant (~37–45%) | BT fastest (~4.5–5.2%) |
| Application | PCBs, IC packaging substrates, RF & microwave, Automotive modules, Display panels, Industrial electronics | PCBs largest (~46%) | IC packaging fastest |
| Thickness | ≤0.1 mm, 0.1–0.5 mm, 0.5–1 mm, Above 1 mm | 0.1–0.5 mm leads (~46%) | 0.5–1 mm fastest (~4.6%) |
| End-use industry | Consumer electronics, Telecom, Automotive, Aerospace & defence, Industrial, Medical | Consumer electronics ~48.5% | Automotive fastest (~4.6%) |
The implication is that volume leadership and value growth diverge. Consumer-electronics PCBs generate scale but compress margin; BT resin, cyanate ester and 0.5–1 mm cores for automotive power and IC packaging carry the pricing power. Suppliers weighted purely to FR-4 volume face flat-to-negative real pricing.
Asia Pacific leads with roughly 52% of global revenue and the fastest growth at about 5.2% CAGR, reflecting China, Taiwan, Japan and South Korea's concentration of PCB fabrication and packaging capacity.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.52% |
| North America | 0.25% |
| Europe | 0.15% |
| Latin America | 0.05% |
| Middle East & Africa | 0.04% |
| Region | Estimated share | Growth profile | Demand character |
|---|---|---|---|
| Asia Pacific | ~52% | Fastest, ~5.2% CAGR | High-volume PCB and packaging fabrication |
| North America | ~25% | Moderate | Aerospace, defence, advanced packaging |
| Europe | ~15% | Moderate | EV electronics, industrial, compliance-led |
| Latin America | ~4.5% | Emerging | Automotive modules, industrial |
| Middle East & Africa | ~3.5% | Emerging | Infrastructure, import-led |
Note the tension between the two leading regional claims in circulation. One dataset puts North America at 34.7% share; another puts Asia Pacific at 57.8%. Our analysis suggests the divergence is a scope artefact: North America leads if revenue is counted at laminate sale value including premium aerospace pricing, while Asia Pacific dominates on volume and shipped substrate area. Buyers should not treat either as a demand signal without knowing which basis applies.
High-frequency electronics, transport electrification and packaging localisation are the primary demand engines, while capital intensity and long qualification cycles cap how fast supply can respond.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| 5G/6G and high-frequency compute | Driver | Strong | Millimetre-wave modules need dielectric stability commodity organics cannot hold |
| EV and transport electrification | Driver | Strong | Each EV uses ~1.5–2.2x the substrate area of an ICE vehicle |
| Miniaturisation and rigid-flex adoption | Driver | Moderate | Wearables and foldables need thin, warp-resistant cores |
| Supply-chain localisation / packaging funding | Driver | Moderate | CHIPS-style programmes pull capacity closer to end demand |
| Capital intensity of high-performance lines | Restraint | Strong | Long-lead capex and precision scaling bottleneck mid-tier producers |
| Feedstock volatility | Restraint | Moderate | Electronic-grade glass yarn, specialty resin and copper foil are concentrated |
| 12–24 month qualification cycles | Restraint | Strong | Automotive and aerospace qualification delays revenue conversion |
| Ceramic, LCP and polyimide substitution | Threat | Moderate | Alternative chemistries contest high-frequency niches |
The balance favours demand over supply through the forecast window. Our analysis suggests the binding constraint is not order books but qualified capacity — which is precisely why lead times and pricing hold up even as headline volume growth stays in the mid-single digits.
Competition splits into premium performance-laminate specialists, integrated Japanese and Korean material houses, and cost-scaled Asian laminate producers.
| Company | Positioning | Core strength | Strategic thrust |
|---|---|---|---|
| Panasonic Holdings | Integrated materials leader | Thermal stability, signal integrity | Expanded high-Tg laminates for EV and automation (2024) |
| Rogers Corporation | Premium RF/microwave specialist | Low-loss dielectric performance | Next-gen high-frequency laminate for 5G (2024) |
| Isola Group | Broad portfolio, standard to high-frequency | Portfolio breadth, Asian partnerships | Thin lightweight laminates for EV modules (2023) |
| Ventec International | Custom high-frequency and high-power | Application co-development | EV OEM partnership for battery management laminates (2023) |
| Shennan Circuits | Cost-optimised high-volume | Scale and localisation | AI-driven process monitoring for yield (2024) |
| Mitsubishi Gas Chemical | BT resin capability | High-heat resin chemistry | Packaging substrate materials for advanced nodes |
Differentiation rests on qualification, not price. Once a laminate is designed into an automotive or avionics stack, switching costs are high because requalification runs 12–24 months. That creates durable moats for incumbents and a structural barrier for new entrants.
Selection criteria are dominated by dielectric performance (Dk/Df at target frequency), glass transition temperature, coefficient of thermal expansion, warpage behaviour under reflow, and halogen-free compliance for EU and North American buyers. Price is secondary in automotive, aerospace and packaging applications, and primary only in cost-sensitive consumer and industrial boards.
Procurement risk concentrates in three areas. First, electronic-grade glass yarn and specialty resin supply is concentrated among few suppliers, so single-sourcing creates exposure. Second, capacity for high-performance grades is tight, extending lead times. Third, qualification is not transferable between suppliers, meaning a dual-source strategy requires parallel qualification investment well before a disruption occurs.
Operators should also track the shift toward glass cores with through-glass vias as lower-warpage alternatives to silicon interposers. This is an early-stage but structurally important substitution vector for RF, photonics and LiDAR packaging.
The balance of evidence favours the consensus 4.0–4.1% CAGR case. Four independently scoped estimates converge on a ~USD 1.18 Billion 2025 base, and the divergent 8.1% figure is best explained by a wider composite basket rather than genuine substrate demand. Within that envelope, growth is uneven: commodity FR-4 volume stagnates while BT resin, cyanate ester and thin high-Tg cores compound above market.
The strongest counter-argument is that AI-driven advanced packaging could pull glass substrates into the mainstream faster than modelled, particularly if through-glass via adoption accelerates in co-packaged optics. If that happens, the 5.8% case becomes the base case. It is a credible upside scenario, not the central one.
What would change our conclusion: sustained evidence that through-glass via packaging has moved from pilot to volume production, or a step-change in electronic-grade glass yarn capacity that removes the feedstock constraint. Absent either, the mid-single-digit consensus holds.
This overview establishes the strategic frame. Precise sub-segment forecasting — by thickness band, resin chemistry and country-level demand — requires the full report's modelled datasets.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.1% from 2020-2034 |
| Segmentation |
|
The market was valued at approximately USD 1.23 Billion in 2026 and is projected to reach USD 1.69 Billion by 2034, growing at a consensus CAGR of about 4.1% across the forecast period.
Asia Pacific leads with roughly 52% of global revenue and the fastest growth at about 5.2% CAGR, driven by PCB and packaging fabrication in China, Taiwan, Japan and South Korea. North America retains high-value aerospace and defence demand.
Glass-reinforced BT resin is the fastest-growing product chemistry at roughly 4.5–5.2% CAGR, while IC packaging substrates are the fastest-growing major application, driven by chiplet architectures and high-performance computing.
Divergence reflects scope, not error. Estimates near USD 1.18 Billion cover electronic-grade laminates and copper-clad laminates only; the USD 4.2 Billion figure captures a broader advanced-composites basket including non-electronic applications.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the glass reinforced substrate value chain: electronic-grade glass yarn and specialty resin suppliers, laminate and copper-clad laminate producers, contract laminators, and global distributors serving PCB fabricators. Interviewees were drawn from decision-maker designations including VP of Sourcing, Heads of Materials R&D, Technical Directors for packaging and PCB engineering, and Commercial Operations Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 35% |
| Procurement & Sourcing Leads | 35% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Laminate & CCL Producers | 40% |
| Glass Yarn & Resin Suppliers | 30% |
| PCB Fabricators & Packaging Houses | 20% |
| Distributors & Traders | 10% |
Estimates were cross-checked against UN Comtrade and WTO trade flows for glass fibre, resin and copper-clad laminate; US ITC and Eurostat import/export records; corporate annual filings, 10-K and investor presentations from listed substrate producers; patent databases tracking low-Dk and through-glass-via innovation; and technical standards published by IPC and IEC relevant to laminate performance classification.
Top-down modelling allocated macroeconomic electronics and automotive output to substrate consumption by application. Bottom-up modelling built revenue from manufacturer nameplate capacity, realised utilisation, product mix and price per square metre, then reconciled both against end-use consumption volumes.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |