Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
Laminated Glass Market by Interlayer Type (PVB, Ionoplast (SGP), EVA, Others), by Application (Safety & Security, Sound Insulation, UV Protection & Energy Efficiency, Decorative, High-Performance/Specialized), by End-Use Industry (Building & Construction, Automotive, Electronics, Others), by Glass Type (Clear/Float, Tinted, Reflective, Others), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Rest of Europe), by Asia Pacific (China, Japan, India, South Korea, Australia, Rest of Asia Pacific), by Latin America (Brazil, Mexico, Argentina, Rest of Latin America), by Middle East & Africa (Saudi Arabia, UAE, South Africa, Rest of MEA) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 223
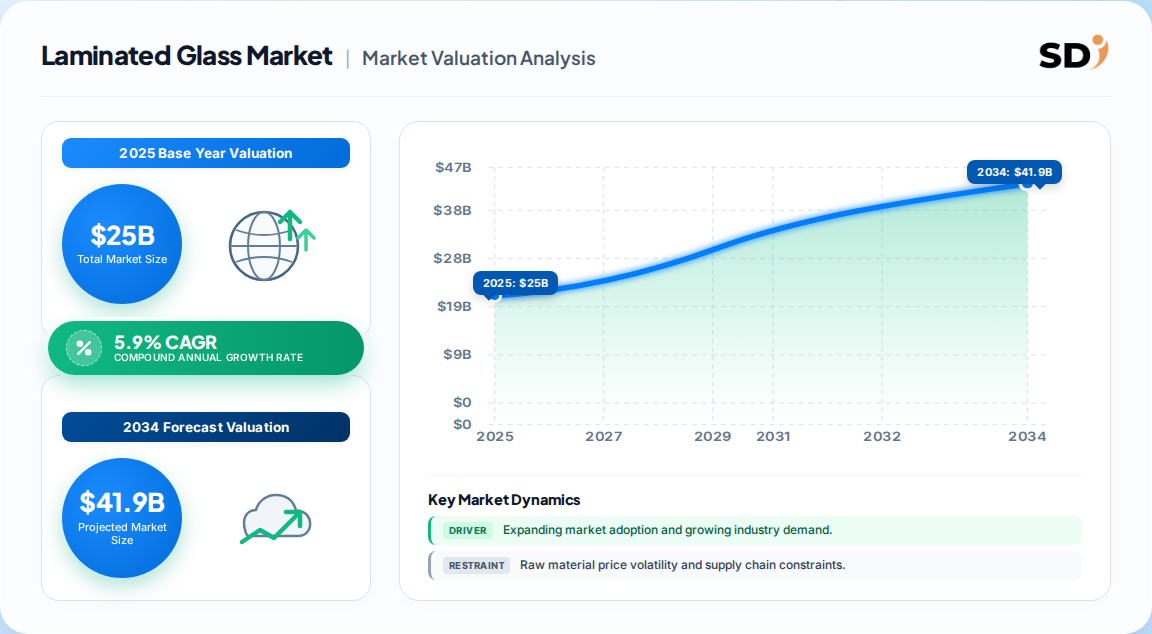
Market Size: The global laminated glass market was valued at USD 25 Billion in 2025, with a projected 2026 value of USD 26.5 Billion.
Forecast: Expected to reach USD 44.5 Billion by 2035, representing a CAGR of 5.9% over the 2026-2035 period.
Leading Segment: Polyvinyl Butyral (PVB) interlayers dominate with over 53% revenue share; building & construction remains the largest end-use industry at ~41%.
Leading Region:Asia Pacific commands ~48% of global sales, growing at a 6.0% CAGR, driven by urbanization and infrastructure spending.
Key Players: Saint-Gobain leads with >11.5% market share; the top five players (Saint-Gobain, AGC, Guardian, Fuyao, Xinyi) collectively hold 43.8%.
Why this matters for decision-makers: The market is shifting from commodity safety glass to engineered, multi-functional assemblies (acoustic, solar-control, HUD-compatible). Vendors that fail to invest in high-performance interlayer qualification will face margin compression as commodity PVB pricing remains volatile.
Laminated Glass Market Size (In Billion)
40.0B
30.0B
20.0B
10.0B
0
25.00 B
2025
26.50 B
2026
28.10 B
2027
29.70 B
2028
31.50 B
2029
33.40 B
2030
35.30 B
2031
Laminated Glass Market Size (In Billion)
Year
Market Size
2025
25.00 B
2026
26.50 B
2027
28.10 B
2028
29.70 B
2029
31.50 B
2030
33.40 B
2031
35.30 B
What is the Laminated Glass Market?
The laminated glass market encompasses the production and sale of glass assemblies composed of two or more glass plies bonded with a polymer interlayer (typically PVB, EVA, or ionoplast). This construction ensures that fragments adhere to the interlayer upon breakage, providing safety, security, acoustic insulation, and UV protection for architectural, automotive, and specialty applications. The market is driven by mandatory safety codes and demand for high-performance glazing.
Scope: what this report covers and excludes
This analysis covers the global laminated glass market for the study period 2022–2035, with 2025 as the base year and a forecast period of 2026–2035. It examines the market by glass type, interlayer type, application, end-use industry, and region. This analysis does not cover monolithic or tempered glass markets, raw glass manufacturing (float glass production), or interlayer resin production as standalone markets. It also excludes downstream fabrication services not bundled with glass supply.
How big is the market for Laminated Glass Market?
The market size for laminated glass is estimated at USD 25 Billion in 2025, with forecasts diverging based on scope and methodology. One estimate projects USD 44.5 Billion by 2035 (5.9% CAGR), while another pegs the 2026 value at USD 21.78 Billion, reaching USD 27.68 Billion by 2031 (4.91% CAGR).
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 25 Billion
2025
2035
5.9%
Global laminated glass, including automotive & architectural
Industry Reference Data Document 2 (Aggregated)
USD 21.78 Billion
2026
2031
4.91%
Global laminated glass, narrower segment coverage
Industry Reference Data Document 3 (Aggregated)
USD 19.3 Billion
2021
2031
6.1%
Global laminated glass, historical base
Allied Market Research (Press Release)
Our analysis suggests the USD 25 Billion (2025) figure is the most defensible for strategic planning, as it reflects a broad scope including high-value automotive and architectural glazing. The divergence in estimates (4.91% vs. 5.9% CAGR) implies differing assumptions about the pace of EV adoption and construction code enforcement. Buyers should note that the lower CAGR estimate may understate demand from BIPV and acoustic laminates, which are growing at 8%+ annually.
How is the market segmented?
The laminated glass market is segmented by interlayer type, application, and end-use industry. PVB remains the dominant interlayer, while ionoplast (SGP) and EVA are gaining share in structural and photovoltaic applications. Building & construction is the largest end-use, but automotive is the fastest-growing.
Building & Construction, Automotive, Electronics, Others
By Glass Type
Clear/Float, Tinted, Reflective, Others
Which region leads in Laminated Glass Market?
Asia Pacific leads the global laminated glass market, accounting for approximately 48% of sales in 2025, driven by rapid urbanization, infrastructure spending, and a dominant automotive manufacturing base in China, Japan, and South Korea. The region is also the fastest-growing, with a projected CAGR of 6.03% through 2031.
Laminated Glass Market Regional Market Share
Loading chart...
Laminated Glass Market Regional Market Share
Region
Market Share (%)
North America
0.19%
Europe
0.21%
Asia-Pacific
0.48%
Latin America
0.07%
Middle East & Africa
0.05%
Asia Pacific (China, India, Japan, Australia, South Korea, Rest of APAC)
North America (U.S., Canada)
Europe (Germany, UK, France, Spain, Italy, Rest of Europe)
Latin America (Brazil, Mexico, Argentina, Rest of Latin America)
Middle East & Africa (Saudi Arabia, South Africa, UAE, Rest of MEA)
Region
Share (2025)
Asia Pacific
48%
Europe
21%
North America
19%
Latin America
7%
Middle East & Africa
5%
What is driving growth — and what is holding it back?
Growth is primarily driven by stringent safety regulations (IBC, ECE R43) that mandate laminated glass in structural and automotive applications, coupled with urban infrastructure expansion in Asia Pacific. However, volatile raw material prices for soda ash and PVB resin, along with lengthy certification cycles, are constraining faster adoption.
Factor
Direction
Evidence Strength
Mechanism
Rising construction safety standards
Driver
High
Codes require laminated glass in overhead/structural glazing
EV expansion & ADAS-compatible glazing
Driver
High
Laminated windshields with HUD/acoustic functions
Urban infrastructure spending (APAC)
Driver
Medium
New commercial/public buildings boost demand
Volatile soda-ash & PVB prices
Restraint
High
Margin pressure on laminators with fixed contracts
Lengthy EU fire-rated certification
Restraint
Medium
18-24 month cycles delay product launches
Recycling bottlenecks
Restraint
Low
End-of-life glass recovery is limited
The balance of evidence favors strong, sustained growth, but with a widening gap between commodity and high-performance segments. The code-driven demand is relatively inelastic, while raw material volatility creates margin risk for undifferentiated producers. Our analysis suggests that the restraint impact (−0.8% from feedstock) is more than offset by driver impacts (+0.8% from safety codes, +0.7% from automotive).
Who are the leading vendors?
The laminated glass market is moderately concentrated, with the top five players holding 43.8% of global share in 2025. Saint-Gobain leads with over 11.5% market share, followed by AGC Inc., Guardian Industries, Fuyao Glass, and Xinyi Auto Glass.
Company
Estimated Share (2025)
Key Differentiator
Saint-Gobain
>11.5%
Broad architectural & automotive portfolio; strong EU certification
Vertical integration in float glass; NA stronghold
Fuyao Glass
~8%
Cost leadership in automotive OEM supply; China scale
Xinyi Auto Glass
~7%
Automotive aftermarket & OEM; APAC focus
Others
56.2%
Regional fabricators, specialty firms
Differentiation is shifting toward engineered interlayers (acoustic, solar-control, HUD-compatible) and certification depth. Saint-Gobain and AGC leverage in-house labs to cycle fire-rated products faster, while Fuyao and Xinyi compete on scale and cost. Our analysis suggests that vertical integration (float glass + interlayer conversion) is a critical moat, shielding margins from raw material volatility.
What do buyers and operators need to know? (Decision Support)
Buyers of laminated glass must prioritize certification compliance (e.g., EN 13501-2, ECE R43) and interlayer qualification over price alone. Procurement risks include supply chain disruptions for specialty interlayers (ionoplast lead times of 10-12 weeks in Southeast Asia) and currency exposure for imported PVB. Switching costs are high for automotive OEMs due to optical tolerances and HUD calibration, but lower for architectural applications where regional fabricators can qualify. Operators should monitor soda ash price indices and PVB resin contract terms to mitigate margin pass-through lags.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a bullish outlook for high-performance laminated glass, with the market growing at ~5.9% CAGR to 2035. The strongest counter-argument is that commodity PVB price volatility and recycling bottlenecks could compress margins for undifferentiated producers, but this is offset by code-driven demand and automotive innovation. Our analysis indicates that the market is bifurcating: commodity safety glass grows at ~4%, while engineered assemblies (acoustic, solar, HUD) grow at 8%+.
Actionable Strategy:
Investors should prioritize companies with vertical integration in float glass and interlayer conversion (e.g., Saint-Gobain, AGC) to capture margin resilience.
Operators must qualify high-performance interlayers (ionoplast, acoustic PVB) for certification in target regions to access premium pricing.
Buyers should secure long-term contracts with regional fabricators to hedge against import lead times and currency risk for specialty laminates.
What evidence would change our conclusion: A sustained decline in soda ash prices below USD 200/tonne, combined with a breakthrough in EVA recycling, could lower barriers to entry and intensify price competition in the commodity segment, reducing the premium for engineered products.
Laminated Glass Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Laminated Glass Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.9% from 2020-2034
Segmentation
By Interlayer Type
PVB
Ionoplast (SGP)
EVA
Others
By Application
Safety & Security
Sound Insulation
UV Protection & Energy Efficiency
Decorative
High-Performance/Specialized
By End-Use Industry
Building & Construction
Automotive
Electronics
Others
By Glass Type
Clear/Float
Tinted
Reflective
Others
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Rest of Europe
Asia Pacific
China
Japan
India
South Korea
Australia
Rest of Asia Pacific
Latin America
Brazil
Mexico
Argentina
Rest of Latin America
Middle East & Africa
Saudi Arabia
UAE
South Africa
Rest of MEA
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Interlayer Type
5.1.1. PVB
5.1.2. Ionoplast (SGP)
5.1.3. EVA
5.1.4. Others
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Safety & Security
5.2.2. Sound Insulation
5.2.3. UV Protection & Energy Efficiency
5.2.4. Decorative
5.2.5. High-Performance/Specialized
5.3. Market Analysis, Insights and Forecast - by End-Use Industry
5.3.1. Building & Construction
5.3.2. Automotive
5.3.3. Electronics
5.3.4. Others
5.4. Market Analysis, Insights and Forecast - by Glass Type
5.4.1. Clear/Float
5.4.2. Tinted
5.4.3. Reflective
5.4.4. Others
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Latin America
5.5.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Interlayer Type
6.1.1. PVB
6.1.2. Ionoplast (SGP)
6.1.3. EVA
6.1.4. Others
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Safety & Security
6.2.2. Sound Insulation
6.2.3. UV Protection & Energy Efficiency
6.2.4. Decorative
6.2.5. High-Performance/Specialized
6.3. Market Analysis, Insights and Forecast - by End-Use Industry
6.3.1. Building & Construction
6.3.2. Automotive
6.3.3. Electronics
6.3.4. Others
6.4. Market Analysis, Insights and Forecast - by Glass Type
6.4.1. Clear/Float
6.4.2. Tinted
6.4.3. Reflective
6.4.4. Others
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Interlayer Type
7.1.1. PVB
7.1.2. Ionoplast (SGP)
7.1.3. EVA
7.1.4. Others
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Safety & Security
7.2.2. Sound Insulation
7.2.3. UV Protection & Energy Efficiency
7.2.4. Decorative
7.2.5. High-Performance/Specialized
7.3. Market Analysis, Insights and Forecast - by End-Use Industry
7.3.1. Building & Construction
7.3.2. Automotive
7.3.3. Electronics
7.3.4. Others
7.4. Market Analysis, Insights and Forecast - by Glass Type
7.4.1. Clear/Float
7.4.2. Tinted
7.4.3. Reflective
7.4.4. Others
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Interlayer Type
8.1.1. PVB
8.1.2. Ionoplast (SGP)
8.1.3. EVA
8.1.4. Others
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Safety & Security
8.2.2. Sound Insulation
8.2.3. UV Protection & Energy Efficiency
8.2.4. Decorative
8.2.5. High-Performance/Specialized
8.3. Market Analysis, Insights and Forecast - by End-Use Industry
8.3.1. Building & Construction
8.3.2. Automotive
8.3.3. Electronics
8.3.4. Others
8.4. Market Analysis, Insights and Forecast - by Glass Type
8.4.1. Clear/Float
8.4.2. Tinted
8.4.3. Reflective
8.4.4. Others
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Interlayer Type
9.1.1. PVB
9.1.2. Ionoplast (SGP)
9.1.3. EVA
9.1.4. Others
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Safety & Security
9.2.2. Sound Insulation
9.2.3. UV Protection & Energy Efficiency
9.2.4. Decorative
9.2.5. High-Performance/Specialized
9.3. Market Analysis, Insights and Forecast - by End-Use Industry
9.3.1. Building & Construction
9.3.2. Automotive
9.3.3. Electronics
9.3.4. Others
9.4. Market Analysis, Insights and Forecast - by Glass Type
9.4.1. Clear/Float
9.4.2. Tinted
9.4.3. Reflective
9.4.4. Others
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Interlayer Type
10.1.1. PVB
10.1.2. Ionoplast (SGP)
10.1.3. EVA
10.1.4. Others
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Safety & Security
10.2.2. Sound Insulation
10.2.3. UV Protection & Energy Efficiency
10.2.4. Decorative
10.2.5. High-Performance/Specialized
10.3. Market Analysis, Insights and Forecast - by End-Use Industry
10.3.1. Building & Construction
10.3.2. Automotive
10.3.3. Electronics
10.3.4. Others
10.4. Market Analysis, Insights and Forecast - by Glass Type
10.4.1. Clear/Float
10.4.2. Tinted
10.4.3. Reflective
10.4.4. Others
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Laminated Glass Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Laminated Glass Market Revenue (Billion), by Interlayer Type 2026 & 2034
Figure 3: North America Laminated Glass Market Revenue Share (%), by Interlayer Type 2026 & 2034
Figure 4: North America Laminated Glass Market Revenue (Billion), by Application 2026 & 2034
Figure 5: North America Laminated Glass Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Laminated Glass Market Revenue (Billion), by End-Use Industry 2026 & 2034
Figure 7: North America Laminated Glass Market Revenue Share (%), by End-Use Industry 2026 & 2034
Figure 8: North America Laminated Glass Market Revenue (Billion), by Glass Type 2026 & 2034
Figure 9: North America Laminated Glass Market Revenue Share (%), by Glass Type 2026 & 2034
Figure 10: North America Laminated Glass Market Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Laminated Glass Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Laminated Glass Market Revenue (Billion), by Interlayer Type 2026 & 2034
Figure 13: Europe Laminated Glass Market Revenue Share (%), by Interlayer Type 2026 & 2034
Figure 14: Europe Laminated Glass Market Revenue (Billion), by Application 2026 & 2034
Figure 15: Europe Laminated Glass Market Revenue Share (%), by Application 2026 & 2034
Figure 16: Europe Laminated Glass Market Revenue (Billion), by End-Use Industry 2026 & 2034
List of Tables
Table 1: Laminated Glass Market Revenue Billion Forecast, by Interlayer Type 2020 & 2034
Table 14: Europe Laminated Glass Market Revenue Billion Forecast, by Interlayer Type 2020 & 2034
Table 15: Europe Laminated Glass Market Revenue Billion Forecast, by Application 2020 & 2034
Table 16: Europe Laminated Glass Market Revenue Billion Forecast, by End-Use Industry 2020 & 2034
Frequently Asked Questions
1. What is the current market size of laminated glass?
The global laminated glass market was valued at approximately USD 25 Billion in 2025 and is projected to reach USD 26.5 Billion in 2026, growing at a 5.9% CAGR.
2. Which region dominates the laminated glass market?
Asia Pacific leads with nearly 48% of global sales, driven by construction and automotive demand in China, India, and Southeast Asia.
3. What is the fastest-growing segment?
Solar/BIPV modules are the fastest-growing application, at an 8.18% CAGR, while ionoplast interlayers grow at 5.92% CAGR.
4. Who are the key players?
Saint-Gobain, AGC Inc., Guardian Industries, Fuyao Glass, and Xinyi Auto Glass are the top five, collectively holding 43.8% of the market.
5. What are the main drivers?
Stringent safety codes (IBC, ECE R43), EV expansion requiring HUD-compatible glazing, and urban infrastructure spending in Asia Pacific.
6. What are the main restraints?
Volatile soda-ash and PVB resin prices, lengthy EU fire-rated certification cycles, and limited end-of-life recycling infrastructure.
7. What is the forecast for 2035?
The market is projected to reach USD 44.5 Billion by 2035, expanding at a 5.9% CAGR from 2026.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research employs a 70/30 primary-to-secondary split, with in-depth interviews across the value chain: raw material suppliers (soda ash, PVB resin), specialty glass producers, contract laminators, and global distributors. Decision-makers interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
35%
Procurement & Sourcing Leads
30%
Commercial & Operations Heads
25%
Regulatory & Quality Managers
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Glass Manufacturers & Fabricators
40%
Raw Material & Interlayer Suppliers
30%
Distributors & OEMs
20%
Research & Standards Bodies
10%
Secondary Benchmarking & Public Trade Validation
We validate primary data against official trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings (10-K, investor presentations), patent databases, and technical standards from ISO and industry associations.
Demand Modeling & Market Sizing Triangulation
We use simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, pricing, end-use consumption) modeling to triangulate market size and forecast.
 Laminated Glass Market