 Spray Paints Market
 Size, Share & Forecast 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 270

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Spray Paints Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 11.00 B |
| 2026 | 11.50 B |
| 2027 | 12.10 B |
| 2028 | 12.80 B |
| 2029 | 13.50 B |
| 2030 | 14.30 B |
| 2031 | 15.10 B |

The spray paints market covers ready-to-use aerosol coatings and spray-applied coating systems used for decorative finishing, surface protection and maintenance across metal, wood, plastic and glass substrates. It spans consumer touch-up aerosols through industrial spray formulations, with value driven by application speed, finish consistency and substrate compatibility.
This analysis covers global spray paints across aerosol and spray-applied formats, segmented by resin, technology, end use and distribution channel, with a 2025 base year and forecast to 2033. This analysis does not cover liquid architectural paints sold in cans, powder coating equipment, paint spray guns as standalone hardware, or raw pigment and resin commodity markets.
Estimates diverge sharply because publishers define the boundary differently — some count only aerosol cans, others include all spray-applied coatings. The table below reconciles the published figures.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 11.0 Billion | 2025 | 2033 | 5.6% | Full spray paints incl. aerosol and industrial spray systems | One published estimate |
| 11.5 Billion | 2026 | 2033 | 5.6% | Same broad definition, forward base year | One published estimate |
| 9.5 Billion | 2026 | 2035 | 6.1% | Broad spray paints, alternative sizing | A competing analysis |
| 1.24 Billion | 2026 | 2031 | 5.32% | Aerosol paints only (pressurised cans) | A competing analysis |
Our analysis suggests the 11.0–11.5 Billion band is the most defensible for total spray paints, because it captures industrial spray demand that aerosol-only studies systematically exclude. The 1.24 Billion figure is internally consistent but roughly an order of magnitude smaller — it measures cans, not coatings. Buyers comparing vendors must confirm which boundary a supplier's revenue actually sits inside.
Segmentation matters because growth rates diverge by technology and end use far more than by resin. Water-based lines are expanding faster than the solvent base they are displacing.
| Parent | Children |
|---|---|
| By Product / Resin | Acrylic, Alkyd, Epoxy, Polyurethane, Others |
| By Technology | Water-based, Solvent-based, Powder Coatings |
| By End Use | Automotive & Transportation, Building & Construction, Consumer Goods, Furniture & Woodworking, Industrial Manufacturing, DIY |
| By Distribution Channel | Retail, E-commerce, Direct / Industrial Supply |
Acrylic's ~31% share reflects its versatility across substrates; solvent-based's ~70% technology share reflects performance rather than preference. This divergence implies the incumbent revenue base is concentrated in the segment facing the heaviest regulatory pressure — a structural risk to mix, not to volume.
Asia Pacific leads the global spray paints market with roughly 32.5% revenue share in 2025, with China the single largest country market, supported by construction, automotive and furniture manufacturing density.
| Region | Market Share (%) |
|---|---|
| Asia Pacific | 0.35% |
| North America | 0.24% |
| Europe | 0.22% |
| Latin America | 0.09% |
| Middle East & Africa | 0.1% |
| Region | 2025 share |
|---|---|
| Asia Pacific | 32.5% |
| North America | 24% |
| Europe | 22% |
| Latin America | 9% |
| Middle East & Africa | 12.5% |
Note that aerosol-only studies report Asia Pacific shares closer to 45%, confirming that industrial spray demand is concentrated in Western refinishing and manufacturing. The implication: Asia Pacific's lead is volume-led and price-sensitive, while North America and Europe remain the margin pools for premium and compliant formulations.
Growth is being pulled by application-speed economics in construction and refinishing, and pushed back by VOC limits and propellant regulation that raise reformulation and compliance costs.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Convenient, fast-drying surface finishing | Driver | High | Labour-hour savings on touch-up and trim work |
| Automotive refinishing and customization | Driver | High | Collision repair and consumer touch-up demand |
| Construction and renovation activity | Driver | High | Global construction spend near 17.5 Trillion by 2030 |
| Water-based / low-VOC reformulation | Opportunity | Medium-High | Compliance-driven substitution of solvent lines |
| Stringent VOC-content regulations | Restraint | High | Limits on solvent flat finishes in EPA, EU, CARB jurisdictions |
| HFC propellant phase-down (Kigali) | Restraint | Medium | Aerosol cost and reformulation pressure from 2029 |
Our analysis suggests the regulatory constraint is mispriced by much of the market. VOC limits act as a short-term drag — one impact assessment attributes roughly -1.1% to CAGR — but they simultaneously create a defensible switching moat for suppliers who complete water-based qualification first. The balance of evidence favours compliant suppliers growing share faster than the headline 5.6% CAGR implies.
Competitive intensity is moderate: the top ten suppliers hold roughly half of global capacity, with regional brands surviving on localized colour palettes and fire-code storage advantages.
| Company | Portfolio strength | Notable positioning |
|---|---|---|
| AkzoNobel N.V. | Broad decorative and refinish | Global scale in premium coatings |
| PPG Industries | Glidden Max Flex, fast-dry aerosols | Consumer and DIY channel depth |
| The Sherwin-Williams Company | Collision Core dispensing systems | Body-shop workflow integration |
| Nippon Paint Holdings | Asia Pacific architectural | Regional volume leadership |
| RPM International | Rust-Oleum spray technology | Aerosol innovation and retail reach |
Differentiation increasingly rests on application systems rather than chemistry alone. Rust-Oleum's multi-pattern nozzle and Sherwin-Williams' precision dispensers shift competition toward workflow ownership — a moat that regional price competitors cannot replicate quickly.
Selection criteria begin with substrate compatibility and cure performance, not unit price. Buyers in regulated jurisdictions must verify VOC content against local limits before qualification, since a compliant label in one jurisdiction may fail another.
Procurement risk concentrates in three areas: solvent supply volatility, propellant availability under the Kigali phase-down, and fire-code storage limits on pressurised inventory. Each raises carrying cost and constrains distributor stocking density.
Switching costs are moderate but asymmetric. Moving from solvent to water-based typically requires substrate prep changes, drying-time rework and re-qualification of finish quality — often 8–12 weeks of internal effort. Operators should model total applied cost per square metre rather than per can, and lock multi-year supply agreements ahead of 2029 propellant transitions.
The balance of evidence favours a compliant-supply strategy over a volume-share strategy. Growth is capped near 5.6%, so incremental revenue must come from mix migration, not market expansion. The strongest counter-argument is that water-based formulations still underperform solvent on year-round adhesion and dry time, meaning substitution will be slower than regulation implies — which genuinely protects solvent incumbents through the medium term.
Our judgement is that this protection is a window, not a moat. Reformulation chemistry, nozzle systems and low-VOC performance have advanced enough that the performance gap is closing in architectural, furniture and consumer applications, while automotive refinishing remains the last solvent stronghold. Vendors who wait for enforcement will buy compliance at the peak of its cost curve.
What would change this conclusion: evidence of a durable multi-year performance gap in water-based adhesion under cold or high-humidity conditions, or a regulatory delay beyond 2030 in major jurisdictions. Absent that, mix migration is the dominant value lever — and precise sub-segment forecasting by resin, technology and country is where execution risk actually sits.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.6% from 2020-2034 |
| Segmentation |
|
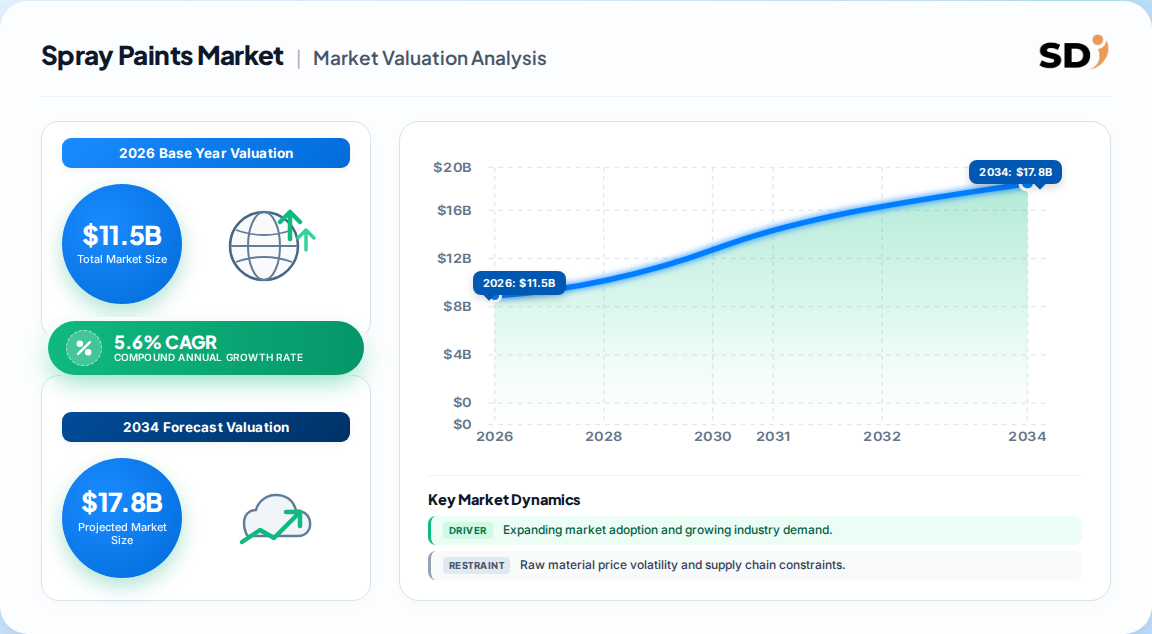
The global spray paints market is estimated at 11.5 Billion in 2026, growing to 16.9 Billion by 2033 at a 5.6% CAGR. Broader definitions including industrial spray systems sit in this range, while aerosol-only studies report far smaller figures.
Water-based and low-VOC formulations are growing fastest, driven by VOC regulation in North America and Europe. Solvent-based still holds roughly 70% of revenue but faces the heaviest compliance pressure, making water-based the primary mix-shift opportunity.
Asia Pacific leads with about 32.5% revenue share in 2025, led by China, India and Southeast Asian construction and furniture output. North America and Europe remain the higher-margin pools for premium and compliant formulations.
AkzoNobel, PPG Industries, Sherwin-Williams, Nippon Paint and RPM International lead, with the top ten suppliers controlling roughly half of global capacity. Regional brands persist through localized colour palettes and fire-code storage advantages.
VOC-content regulations and the HFC propellant phase-down under the Kigali Amendment are the main restraints, raising reformulation and compliance costs. Fire-code restrictions on pressurised storage also constrain distributor stocking and add carrying cost.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the value chain with raw material and resin suppliers, specialized aerosol producers, contract formulators, and global distributors. Within these organizations we engaged VP-level Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads to capture both formulation economics and channel behaviour.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Regulatory Affairs Managers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Resin & Raw Material Suppliers | 30% |
| Aerosol & Spray Producers | 35% |
| Contract Formulators | 20% |
| Distributors & Retailers | 15% |
Secondary validation draws on UN Comtrade and WTO trade flows, US ITC and Eurostat shipment data, corporate 10-K and annual investor filings, patent databases, and recognised technical standards bodies. Regulatory parameters were cross-checked against EPA and CARB VOC limits, EU Directive 2004/42/EC, and Kigali Amendment propellant schedules.
Top-down allocation from macroeconomic construction and automotive output runs simultaneously with bottom-up modeling of manufacturer capacity, aerosol can fill volumes, product pricing, and end-use consumption. Divergences between the two models are resolved through segment-level reconciliation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow & consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & filings | High |