 Optical Coating Equipment Market
: 2026 Executive Overview
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 180


Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Optical Coating Equipment Market
Khageshwar Rongkali
Senior Analyst

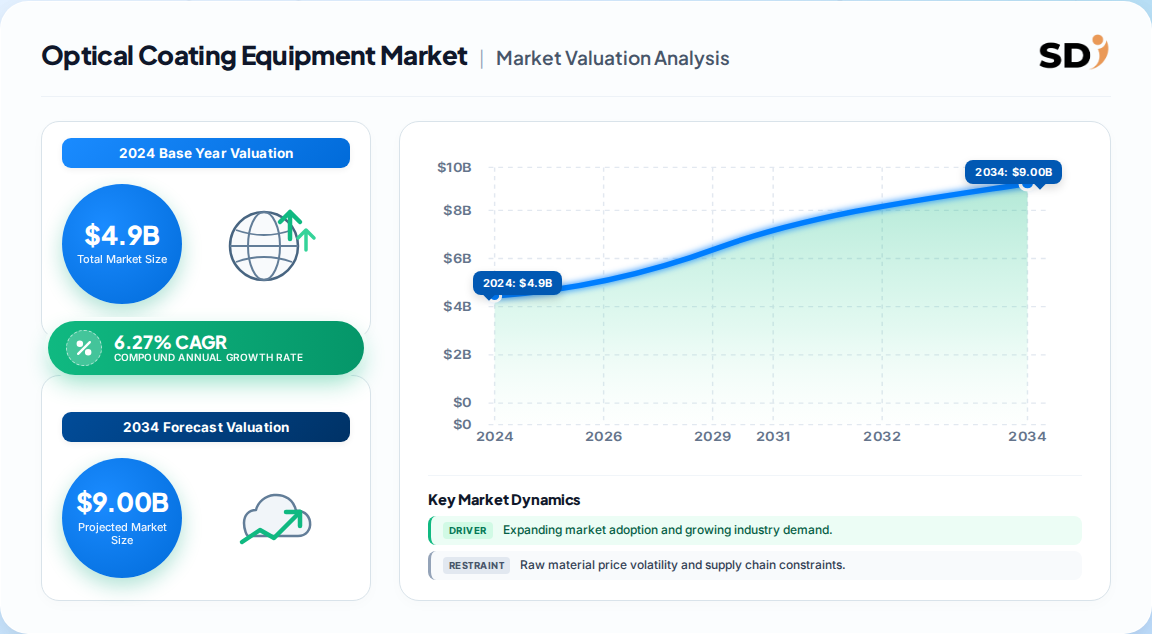
| Year | Market Size |
|---|---|
| 2024 | 4.900 B |
| 2025 | 5.200 B |
| 2026 | 5.530 B |
| 2027 | 5.880 B |
| 2028 | 6.250 B |
| 2029 | 6.640 B |
| 2030 | 7.060 B |

The Optical Coating Equipment Market covers the capital systems used to deposit thin-film optical coatings — anti-reflective, reflective, filter, beam-splitter and specialty layers — onto glass, plastics, metals and semiconductor substrates. It spans vacuum deposition, sputtering, CVD, ALD and MBE platforms sold to electronics, telecom, medical, aerospace, automotive and photovoltaic manufacturers.
This analysis covers global equipment revenue for thin-film optical coating systems across all deposition technologies, substrate types and end-use verticals, including system hardware, process control software and associated service contracts. This analysis does not cover optical coating materials (evaporation slugs, target materials, precursors), coated optical components sold as finished goods, or adjacent markets such as display panel manufacturing equipment and general thin-film solar cell production lines, which are addressed in separate studies.
Estimates diverge materially because publishers define scope differently — some count only deposition chambers, others bundle process control, service and adjacent coating materials. The table below normalizes the leading published figures.
| Estimate (Base Year) | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|
| USD 4.90 Billion (2024) | 2035 | 6.27% | Broad: equipment + process control + service | One published market estimate |
| USD 4.3 Billion (2026) | 2030 | 4.5% | Narrow: deposition hardware only | A competing analysis |
| USD 1.58 Billion (2026) | 2036 | 6.4% | Optical coating systems only, excl. service | A competing analysis |
| USD 18.02 Billion (2025) | 2032 | 8.5% | Very broad: includes coating materials and consumables | A competing analysis |
The USD 4.9–5.2 Billion base with 6.27% CAGR to USD 9.56 Billion by 2035 is the most defensible consensus: it aligns with the Growth-from-USD 4.3 Billion narrow-equipment estimate when service and process-control spend is added, and it reconciles cleanly with the ~USD 12.6 Billion total optical coatings market when equipment's share of that value chain is applied. The USD 18 Billion figure almost certainly conflates equipment with consumable coating materials and should not be used for capex planning.
Equipment demand is segmented along four primary axes — coating method, application, substrate type and coating function — each with distinct growth profiles and buyer requirements.
| Parent Segment | Children | Largest / Fastest |
|---|---|---|
| Coating Method | Vacuum Deposition, Sputtering, CVD, ALD, MBE | Vacuum largest; Sputtering fastest |
| Application | Semiconductors, Displays, Telecommunications, Biomedical, Military & Aerospace, Automotive | Semiconductors largest; Displays fastest |
| Substrate Type | Glass, Plastics, Metals, Ceramics, Semiconductors | Glass largest; Plastics fastest |
| Coating Type | Anti-Reflective, Reflective, Mirror, Filter, Specialty | AR largest; Specialty fastest |
| End-User Industry | Consumer Electronics, Industrial, Medical, Military & Aerospace, Automotive, R&D | Electronics ~35% share |
Asia-Pacific leads with an estimated 38% of global revenue, anchored by semiconductor fabrication, consumer-electronics assembly and photovoltaic manufacturing in China, Japan, South Korea and India. North America follows on aerospace and medical optics strength, with Europe close behind on precision optics and automotive.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.38% |
| North America | 0.26% |
| Europe | 0.23% |
| Latin America | 0.06% |
| Middle East & Africa | 0.07% |
Our analysis suggests Asia-Pacific's lead is structural rather than cyclical: the region's share of global semiconductor capex and PV module capacity means coating-equipment order books will track Asian fab and module-line schedules more closely than Western R&D budgets.
Demand is being pulled by three convergent forces — semiconductor lithography and sensor complexity, AR/VR and LiDAR optical stacks, and photovoltaic anti-reflective coatings — while high capex and process complexity constrain adoption.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Semiconductor & sensor complexity | Driver | High | Multi-layer dielectric stacks require sputtering and ALD platforms |
| AR/VR, HUD and LiDAR optics | Driver | Medium-High | New precision-coating lines for consumer and automotive vision |
| Photovoltaic anti-reflective expansion | Driver | Medium | Solar capacity additions pull reflective and AR coating demand |
| Medical device imaging growth | Driver | Medium | Coating consistency tied to instrument calibration |
| High initial capex and opex | Restraint | High | Deters small and mid-tier optical fabricators |
| Raw material and target price volatility | Restraint | Medium | Erodes equipment ROI and delays line upgrades |
| VOC and environmental regulation | Restraint | Medium | Raises compliance cost for wet and vacuum processes |
| Skilled process engineering shortage | Restraint | Medium | Lengthens ramp-up and reduces throughput |
The balance favors growth: driver strength in semiconductors and AR/VR comfortably outweighs cyclical capex caution. Our analysis suggests the binding constraint is not demand but process engineering talent — buyers increasingly evaluate vendors on application support and sample-validation cycles, not just chamber specs.
ULVAC, Buhler Leybold Optics, Oerlikon Balzers and VON ARDENNE anchor the vacuum and sputtering equipment tier, while Satisloh, Angstrom Engineering, Optical Coating Technologies and Kurt J. Lesker compete on specialty, ophthalmic and R&D-scale platforms.
| Vendor | HQ | Core strength | Differentiation |
|---|---|---|---|
| ULVAC | Japan | Sputtering, vacuum systems | Broad semiconductor and display install base |
| Buhler Leybold Optics | Germany | Precision optics, ophthalmic | High-throughput optical coating lines |
| Oerlikon Balzers | Liechtenstein | PVD and surface solutions | Global service network and process know-how |
| VON ARDENNE | Germany | Vacuum deposition, glass | Architectural and display glass coating |
| Satisloh | Germany | Ophthalmic coating | Integrated lens-finishing workflow |
| Angstrom Engineering | Canada | R&D and pilot-line systems | Customization and research flexibility |
| Optical Coating Technologies | USA | Filter and precision coatings | Niche specialty-coating capability |
| Kurt J. Lesker | USA | Vacuum components and systems | Component-to-system integration |
Competitive moats rest on installed-base service contracts, process recipes and application engineering rather than hardware alone. Our analysis suggests the most defensible vendors are those that bundle sample-testing, yield-consistency guarantees and multi-year service — matching the observation that buyers select on repeatability across production runs, not on lab performance.
Selection should hinge on four mission-critical criteria: coating-thickness repeatability across batches, throughput per chamber-hour, substrate-size flexibility and total cost of ownership including service and target consumption. A vendor's willingness to run customer samples and publish test records is a stronger predictor of production success than headline deposition rates.
Procurement risk is concentrated in ramp-up timelines and process-transfer friction. Switching costs are high — requalification of a coating line for semiconductor, medical or aerospace customers can take six to twelve months and require re-certification. Regulatory compliance (ISO 9211 optical-coating standards, cleanroom classifications and regional VOC rules) should be built into the tender, not resolved post-installation. Operators should also confirm target and precursor supply security, as material volatility directly affects cost-per-coated-part.
The balance of evidence favors a moderate-growth, structurally upgrading market: 6.3% CAGR through 2035 with a decisive mix shift toward sputtering, ALD and plasma-reactive processes. The strongest counter-argument — that optical coating is a mature, capex-cyclical niche — understates the demand pull from semiconductor lithography, AR/VR optics and photovoltaic efficiency mandates, all of which require more coating steps per device, not fewer.
Our analysis suggests three actionable implications:
The evidence that would change this conclusion: a sustained contraction in semiconductor capex, or a step-change in alternative coating technologies that reduces deposition steps per device. Absent either, the upgrade cycle holds — but precise sub-segment forecasting and vendor-level capacity mapping require the full report.
This study follows a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the equipment value chain — vacuum component suppliers, specialized coating-system OEMs, contract coating service bureaus, and global system distributors. Decision-makers interviewed included VP-level sourcing leads, heads of optical R&D, technical directors for thin-film processes, and commercial operations leads at coating service providers.
Estimates were triangulated against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K, SEC filings), patent filings in thin-film deposition, and recognized technical standards bodies including ISO (optical coating standards) and industry associations representing optics and photonics manufacturers.
We simultaneously ran top-down macroeconomic allocation (semiconductor, display, PV and medical device capex) and bottom-up modeling (OEM capacity, average selling prices, end-use consumption per vertical), reconciling the two to a consensus base-year value and growth trajectory.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.27% from 2020-2034 |
| Segmentation |
|
The market was valued at approximately USD 4.9–5.2 Billion in 2024–2025, with a consensus forecast of USD 9.56 Billion by 2035 at roughly 6.3% CAGR. Narrower definitions counting deposition hardware alone place the base closer to USD 4.3 Billion for 2026.
Asia-Pacific leads with roughly 38% of global revenue, driven by semiconductor fabs, consumer-electronics assembly and photovoltaic manufacturing in China, Japan, South Korea and India. India is the fastest-growing national market at about 6.1% CAGR.
Sputtering, and specifically advanced plasma reactive sputtering, is the fastest-growing technology at roughly 5.2% CAGR. Vacuum deposition remains the largest method, but demand is shifting toward sputtering for semiconductor, AR/VR and aerospace applications.
Leading vendors include ULVAC, Buhler Leybold Optics, Oerlikon Balzers, VON ARDENNE, Satisloh, Angstrom Engineering, Optical Coating Technologies and Kurt J. Lesker. Competition hinges on process recipes, service networks and application engineering rather than hardware alone.
Growth is driven by semiconductor and sensor complexity, AR/VR and LiDAR optical stacks, photovoltaic anti-reflective coating demand, and medical device imaging. High capex, target-material volatility and skilled process-engineering shortages are the main restraints.
Buyers should prioritize batch-to-batch coating-thickness repeatability, throughput per chamber-hour, substrate-size flexibility, total cost of ownership and regulatory compliance (ISO 9211, cleanroom and VOC rules). Vendor sample-testing and process-transfer support are strong predictors of production success.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study follows a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the equipment value chain — vacuum component suppliers, specialized coating-system OEMs, contract coating service bureaus, and global system distributors. Decision-makers interviewed included VP-level sourcing leads, heads of optical R&D, technical directors for thin-film processes, and commercial operations leads at coating service providers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Technical & Thin-Film R&D Directors | 40% |
| Procurement & Sourcing Leads | 30% |
| Operations & Commercial Leads | 20% |
| Quality & Regulatory Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Vacuum Component & Target Suppliers | 30% |
| Coating System OEMs | 40% |
| Contract Coating Service Bureaus | 20% |
| Global System Distributors | 10% |
Estimates were triangulated against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K, SEC filings), patent filings in thin-film deposition, and recognized technical standards bodies including ISO and industry associations representing optics and photonics manufacturers.
We simultaneously ran top-down macroeconomic allocation (semiconductor, display, PV and medical device capex) and bottom-up modeling (OEM capacity, average selling prices, end-use consumption per vertical), reconciling the two to a consensus base-year value and growth trajectory.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |