 Middle East Engineering Plastics Market
 Outlook 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 279

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East Engineering Plastics Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 3.000 M |
| 2026 | 3.000 M |
| 2027 | 3.000 M |
| 2028 | 3.000 M |
| 2029 | 3.000 M |
| 2030 | 3.000 M |
| 2031 | 4.000 M |

The Middle East engineering plastics market covers high-performance thermoplastic resins — polyamide, polycarbonate, PBT, PEEK, LCP, fluoropolymers and PET — produced, compounded and consumed across GCC and wider Middle East economies for automotive, electronics, construction, aerospace and packaging applications. Volume is measured in tons of resin sold into downstream conversion.
This analysis covers resin-type and end-user segmentation plus geography across Saudi Arabia, the UAE and the Rest of the Middle East, forecast to 2031 in volume terms. This analysis does not cover commodity polyolefins, thermoset resins, masterbatch additives as a standalone category, or recycled-plastic trading flows.
Two published benchmarks diverge sharply — one values regional volume near 2.84 million tons for 2026, another sizes the global category in the hundreds of billions of dollars. The table below reconciles them.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 2.70M tons → 3.66M tons | 2025 | 2031 | 5.18% | Middle East resin volume, engineering grades only | One published estimate (regional) |
| USD 158.3B → 288.6B | 2025 | 2033 | 7.8% | Global revenue, broader resin basket incl. ABS/SAN | A competing analysis (global) |
| ~USD 8–10B implied | 2026 | 2031 | ~5% | Middle East revenue equivalent at regional price bands | Our analysis, derived |
The volume-based regional figure is the most defensible for Middle East procurement planning: it is internally consistent with stated base and forecast years and aligns with announced GCC capacity additions. The global revenue estimate is broader in definition and roughly double the regional CAGR, which our analysis attributes to ABS/SAN inclusion and Asia-Pacific demand intensity rather than any Middle East acceleration.
Segmentation follows two non-geographic axes — resin chemistry and end-user industry — and chemistry determines both pricing power and qualification difficulty.
| Parent | Children |
|---|---|
| Resin Type | Fluoropolymer, Liquid Crystal Polymer, Polyamide, Polybutylene Terephthalate, Polycarbonate, Polyether Ether Ketone, PET, Others |
| End-User Industry | Aerospace, Automotive, Building & Construction, Electrical & Electronics, Packaging, Industrial Machinery, Others |
PET's 67.70% share reflects packaging's dominance, but the margin pool sits in PA, PC and PEEK, where specification barriers are higher. Our analysis suggests the revenue-to-volume ratio will shift toward specialty resins faster than headline tonnage implies.
Saudi Arabia is the growth engine at 5.62% CAGR, but the Rest of Middle East & Africa still holds the single largest volume block at 40.55% of 2025 demand.
| Region | Market Share (%) |
|---|---|
| Saudi Arabia | 0.32% |
| Rest of Middle East & Africa | 0.41% |
| UAE | 0.18% |
| Qatar | 0.05% |
| Kuwait | 0.03% |
| Oman | 0.01% |
| Parent | Children |
|---|---|
| Middle East | Saudi Arabia, UAE, Qatar, Kuwait, Oman, Rest of Middle East & Africa |
| Sub-region | 2025 volume share |
|---|---|
| Rest of Middle East & Africa | 40.55% |
| Saudi Arabia | 32.00% |
| UAE | 18.00% |
| Qatar | 5.00% |
| Kuwait | 3.00% |
| Oman | 1.45% |
The divergence is instructive: the largest current block grows slowest, while Saudi Arabia converts NEOM, Red Sea Global and CAFE-driven automotive demand into the fastest compounding. This implies share will migrate toward the Kingdom through 2031.
Downstream capacity expansion and mega-project specifications are the strongest drivers, together contributing roughly 2.2 percentage points of the 5.18% CAGR; feedstock volatility is the largest single drag.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Downstream conversion capacity (+1.2%) | Driver | High | Ras Laffan, Liwa, PRIZe secure resin availability |
| FR-rated PC & PA mega-projects (+1.0%) | Driver | High | NEOM, SBC codes lock V-0 specifications |
| Automotive lightweighting (+0.8%) | Driver | Medium | Saudi CAFE, UAE EV roadmap |
| Sovereign specialty polymer push (+0.7%) | Driver | Medium | ADNOC-Borouge, PIF compounding |
| Additive manufacturing hubs (+0.6%) | Driver | Medium | Dubai 3D Printing Strategy to 2030 |
| Naphtha/condensate volatility (−0.9%) | Restraint | High | Feedstock cost pass-through |
| Certified recycling shortage (−0.6%) | Restraint | Medium | Limits circular-content grades |
| Precision moulding skills gap (−0.4%) | Restraint | Medium | Constrains local conversion quality |
The balance favors growth: net driver impact exceeds restraint impact by roughly 2.4 percentage points. Our analysis suggests the binding constraint is not resin supply but qualified conversion capacity — a nuance that changes where value accrues.
Five players anchor the competitive landscape, spanning integrated feedstock majors and global specialty compounders, in a market the source classifies as medium concentration.
| Company | Position | Structural advantage |
|---|---|---|
| SABIC | Regional leader | Integrated feedstock, broad PC/PA portfolio |
| Petro Rabigh | Integrated refiner-producer | Cost-advantaged feedstock integration |
| Sipchem | Specialty chemicals | Downstream acetyls and polymer integration |
| BASF | Global specialty | High-performance PA, PPA, technical service |
| Celanese | Global engineered materials | LCP and high-temperature resin depth |
Moat logic differs by tier. GCC integrated producers compete on ethane-based cost advantage and supply security; global specialists compete on qualification, certification and application engineering. Our analysis suggests the two tiers will increasingly partner rather than collide, with local compounding as the contested middle ground.
Selection criteria in this market are increasingly regulatory, not purely commercial. Flame retardancy to V-0, UV stability and thermal-shock thresholds under Saudi Building Codes SBC 201, 501 and 601 determine whether a grade is even eligible for giga-project supply. Buyers should request part-level compliance evidence, not generic datasheets.
Procurement risk concentrates in feedstock-linked pricing and lead times. Volatile naphtha and condensate costs pass through with a lag, so index-linked contracts with quarterly reset windows transfer risk more fairly than fixed annual pricing. Counterparty risk also matters: new GCC capacity is project-financed and commissioning delays are common.
Switching costs rise steeply after specification. Re-qualifying a resin in a fire-rated conduit or an automotive intake manifold typically takes 6–12 months and requires re-testing, so buyers should negotiate dual-source qualification before design freeze. Skills shortages in precision injection moulding mean converter selection deserves the same diligence as resin selection.
The balance of evidence favors a supply-secure, specification-led strategy over a pure price strategy. Volume growth of 5.18% is modest, but the margin pool is migrating toward FR-rated PC, PA and high-temperature resins where certification, not tonnage, sets pricing. Players who treat this as a commodity PET market will under-earn the cycle.
The strongest counter-argument is that feedstock cost advantage could commoditize specialty grades as new GCC capacity floods the region — a genuine risk in PET and commodity PA. But the certification bottleneck and 6–12 month requalification cycles suggest price competition will be muted in regulated applications through 2031.
Actionable strategy:
What would change our conclusion: a sustained naphtha spike above the −0.9% modelled drag, or accelerated recycling-certification infrastructure that erodes virgin specialty premiums. While this overview covers headline volume, precise sub-segment forecasting by resin grade and country requires the full report's granular model.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.18% from 2020-2034 |
| Segmentation |
|
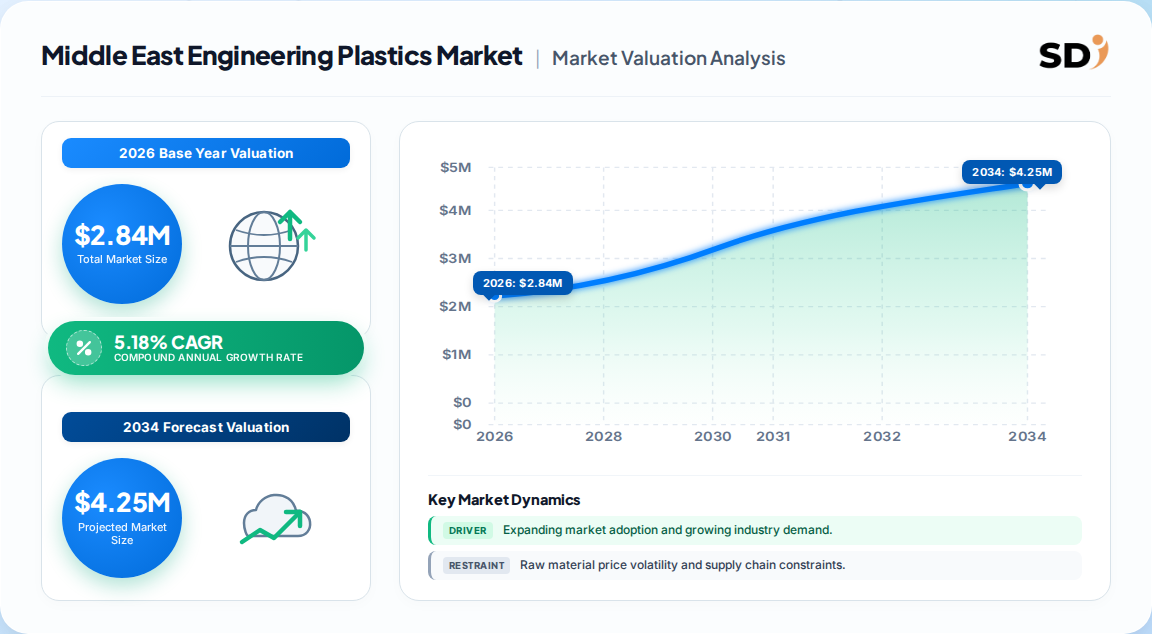
The market is sized at 2.84 million tons in 2026, up from 2.70 million tons in 2025, and is forecast to reach 3.66 million tons by 2031 at a 5.18% CAGR.
Polyethylene terephthalate held 67.70% of 2025 volume share, driven by packaging demand. Liquid crystal polymer is the fastest-growing resin at 6.72% CAGR through 2031.
Saudi Arabia is forecast to lead at a 5.62% CAGR, supported by NEOM, Red Sea Global and CAFE automotive standards. The Rest of Middle East & Africa holds the largest 2025 share at 40.55%.
Electrical and electronics is set to expand at an 8.25% CAGR to 2031, although packaging dominated 2025 demand with a 67.40% share of regional volume.
SABIC, Petro Rabigh, Sipchem Company, BASF and Celanese Corporation are the major players, spanning integrated GCC feedstock producers and global specialty compounders.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain: feedstock and resin producers, specialty compounders, contract formulators, precision moulders and regional distributors. Decision-makers interviewed include VP-level sourcing leads, heads of R&D, technical directors and commercial operations managers, ensuring both specification and procurement perspectives are captured.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Directors | 35% |
| R&D & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Resin & Feedstock Producers | 40% |
| Specialty Compounders & Formulators | 30% |
| Precision Moulders & Converters | 20% |
| Distributors & Traders | 10% |
Secondary validation draws on UN Comtrade and WTO trade flows, national statistics offices, corporate annual filings and investor presentations, patent databases, and recognised technical standards bodies including ISO and ASTM. No competitor market-research publications are cited as primary evidence.
We run simultaneous top-down allocation (macroeconomic output, sector GDP and end-use intensity) and bottom-up modeling (nameplate capacity, utilisation, pricing and per-application consumption). Divergences between the two are reconciled against trade data before any figure is published.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Volume in tons, base year | Bottom-up production & consumption triangulation | High |
| Forecast Horizon | Compound projection to 2031 | Historical CAGR, regression, demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow and consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, filings | High |