 Wax Emulsion Market
 Size, Share & Growth Forecast 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 222

Khageshwar Rongkali

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Wax Emulsion Market
Khageshwar Rongkali
Senior Analyst

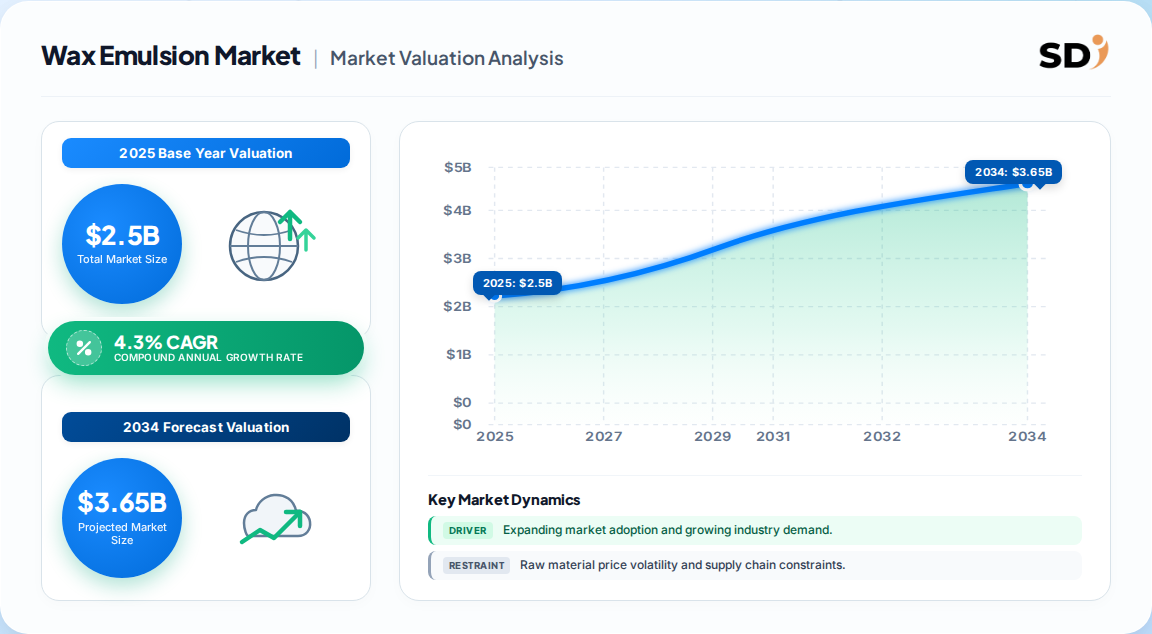
| Year | Market Size |
|---|---|
| 2025 | 2.500 B |
| 2026 | 2.610 B |
| 2027 | 2.720 B |
| 2028 | 2.840 B |
| 2029 | 2.960 B |
| 2030 | 3.090 B |
| 2031 | 3.220 B |

A wax emulsion is a stable, water-based dispersion of one or more waxes (paraffin, carnauba, polyethylene, etc.) created with the help of surfactants. The Wax Emulsion Market covers the industrial production, distribution, and application of these dispersions, which deliver surface protection, water repellency, gloss control, and slip enhancement across paints, coatings, adhesives, textiles, cosmetics, and packaging.
This report analyzes the global production and demand for wax emulsions, segmented by source (synthetic, natural), type (paraffin, carnauba, polyethylene, etc.), application, end-use industry, and geographic region.
In scope: Industrial-grade wax emulsions used as additives in paints, coatings, adhesives, sealants, textiles, leather finishing, paper, packaging, cosmetics, and industrial lubricants.
Excludes: This analysis does not cover dry wax flakes or beads unless used as raw material inputs, nor does it cover generic emulsion polymers (e.g., acrylic or styrene-butadiene emulsions) outside their wax-modified forms. Adjacent markets such as hot-melt adhesives, solvent-based coatings, and pure silicone emulsions are outside scope.
One published estimate pegs global Wax Emulsion Market revenue at USD 2.5 Billion in 2025, growing to USD 3.7 Billion by 2035. However, several competing analyses diverge sharply on both base-year values and forward trajectories, as summarized below.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 2.50 Billion | 2025 | 2035 | 4.3% | Broad end-use, synthetic & natural | One published estimate |
| USD 2.47 Billion | 2026 | 2036 | 4.5% | Source/type/application, ex-regional | Another published analysis |
| USD 2.71 Billion | 2024 | 2035 | 3.67% | Paints, adhesives, cosmetics focus | A competing benchmark |
| USD 706 Million | 2025 | 2032 | 6.3% | Narrow scope (excl. major wood coatings) | Alternative industry sizing |
The USD 2.5 Billion (2025) and USD 2.47 Billion (2026) figures are the most defensible, as they bracket a broadly consistent growth corridor (4.3–4.5%). The extreme low estimate (~USD 706 Million) likely reflects a narrower product definition excluding synthetic waxes or certain end-uses. Our analysis suggests the ~4% CAGR consensus is realistic: it aligns with global paints and construction growth but notably lags GDP in developing Asia, implying structural share gains remain untapped.
Wax emulsions are segmented along four axes—source, product type, application, and end-use industry—each of which reveals distinct demand dynamics and value pools.
| Parent Segment | Children |
|---|---|
| By Source | Synthetic, Natural (animal, vegetable, mineral) |
| By Type | Paraffin, Carnauba, Polyethylene, Polypropylene, PTFE, Fischer-Tropsch, Others |
| By Application | Wood Coatings, Adhesive & Sealants, Printing Inks, Fiberglass Insulation, Metal Polish, Lubricants, Textile Finishing, Cosmetics |
| By End-Use Industry | Paints & Coatings, Building & Construction, Textile & Leather, Pulp & Paper, Cosmetics & Personal Care, Automotive, Packaging, Wood Processing |
Synthetic wax emulsions dominate (~68% share), driven by their consistency, customizable hardness, and superior abrasion resistance in industrial formulations. Natural wax emulsions—especially carnauba—are the fastest-growing niche, favored in cosmetics and eco-certified coatings. The key implication: buyers should not treat "wax emulsion" as a monolith; the synthetic-to-natural trade-off is where the most significant cost and performance decisions lie.
Asia Pacific leads the global Wax Emulsion Market, capturing approximately 45% of total revenue in 2025, underpinned by its concentration of coatings, packaging, and construction activity. North America follows at ~24%, with Europe at ~19%.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.45% |
| North America | 0.24% |
| Europe | 0.19% |
| Latin America | 0.06% |
| Middle East & Africa | 0.06% |
The geographic distribution is as follows:
| Region | Estimated Share | Key Demand Drivers |
|---|---|---|
| Asia Pacific | 44.8% | Construction, packaging, automotive |
| North America | 24.1% | Eco-friendly coatings, renovation |
| Europe | 18.6% | Regulatory compliance, sustainability |
| Latin America | 6.2% | Infrastructure, industrial expansion |
| Middle East & Africa | 6.3% | Construction, oil & gas, textiles |
Our analysis suggests the Asia Pacific dominance is not merely a volume story—it reflects a structural shift where regional producers are moving up the value chain into specialty emulsions, threatening the premium currently commanded by Western suppliers. Buyers sourcing from Asia Pacific should scrutinize quality consistency and regulatory equivalence, not just price.
The Wax Emulsion Market is propelled by a structural shift toward water-based, low-VOC formulations, alongside steady demand from construction and automotive coatings. However, raw-material price volatility and limited shelf life constrain faster adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Shift to water-based, low-VOC coatings | Driver | High | Regulatory pressure + consumer preference |
| Construction & automotive growth | Driver | High | Volume demand for protective coatings & sealants |
| Sustainability / bio-based formulations | Driver | Medium | Premium pricing for natural wax emulsions |
| Raw material price volatility | Restraint | High | Margin compression, formulation cost unpredictability |
| Limited shelf life | Restraint | Medium | Logistical constraints, inventory carrying costs |
| Substitute products (solvent-based, silicone) | Restraint | Medium | Performance trade-offs in niche applications |
The balance of evidence suggests demand-side drivers currently outweigh supply-side restraints. However, the shelf-life constraint is underappreciated: it effectively caps the addressable market for distant or low-turnover buyers, favoring regional producers with short distribution chains. This is a structural advantage for Asia Pacific and North American suppliers serving proximate customers.
The Wax Emulsion Market is moderately concentrated, with global chemical majors competing alongside specialized formulators. Differentiation rests on formulation expertise, application-specific technical support, and regulatory certifications rather than raw scale alone.
| Company | Headquarters | Strategic Focus | Notable Differentiation |
|---|---|---|---|
| BASF SE | Germany | Broad chemical portfolio, dispersion technologies | Integration with coatings & construction |
| Dow Inc. | USA | Performance materials, water-based systems | Strong R&D in acrylic & hybrid emulsions |
| Michelman, Inc. | USA | Surface modification, wax emulsions | Application-specific technical service |
| Lubrizol Corporation | USA | Additives & specialty chemicals | Deep formulation know-how |
| Clariant AG | Switzerland | Specialty chemicals, sustainable additives | Bio-based & eco-certified range |
| Wacker Chemie AG | Germany | Silicone & polymer emulsions | Hybrid silicone-wax systems |
| Sasol Limited | South Africa | Paraffin & FT wax derivatives | Raw-material backward integration |
| ExxonMobil | USA | Petrochemical waxes | Scale & feedstock access |
Competitive moats in this market are built on two pillars: (1) application-specific formulation libraries that reduce customer trial-and-error, and (2) regulatory certifications (e.g., food-contact compliance, low-VOC verification). Our analysis suggests the strongest strategic position belongs to firms that combine backward integration into wax feedstock with forward integration into technical service—a combination that smaller formulators cannot easily replicate.
Procurement in the Wax Emulsion Market is not a commodity-buying exercise. Buyers must evaluate suppliers on five mission-critical criteria: (1) formulation consistency—batch-to-batch variance directly affects coating performance; (2) regulatory compliance—food-contact, low-VOC, and regional chemical inventories (e.g., REACH, TSCA) are non-negotiable; (3) shelf-life and logistics—emulsions degrade, so supplier proximity and inventory management are cost drivers; (4) technical support depth—the ability to co-formulate for specific substrates is a genuine switching cost; and (5) sustainability credentials—bio-based content and biodegradability are increasingly specified in tender documents.
Switching costs are moderate-to-high: reformulating a coating or adhesive to accommodate a new wax emulsion typically requires 3–6 months of testing and may trigger re-certification. This creates stickiness but also risk—buyers should dual-source critical grades. Regulatory compliance is the single largest hidden cost; non-compliant suppliers in one jurisdiction may be excluded entirely from another. Operators should prioritize suppliers who can demonstrate both formulation flexibility and documented compliance across their target markets.
The balance of evidence favors a cautiously optimistic outlook: the Wax Emulsion Market will grow at ~4% annually, roughly in line with global industrial production, but this average masks significant divergence. The strongest counter-argument is that substitution by silicone and solvent-based systems could erode share faster than expected in high-performance niches—but this is unlikely to offset the regulatory tailwind behind water-based formulations.
Our analysis suggests the most significant strategic shift is the bifurcation of the market into (a) a high-volume, price-sensitive segment dominated by paraffin and polyethylene emulsions, and (b) a high-margin, specialty segment driven by bio-based and application-specific formulations. Suppliers straddling both will face margin compression; those committing to one will outperform.
Actionable Strategy:
What would change this conclusion: A faster-than-expected regulatory ban on certain synthetic waxes, or a breakthrough in shelf-life extension technology, would materially alter the competitive landscape. Absent those, the 4% growth corridor and the bifurcation thesis hold.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.3% from 2020-2034 |
| Segmentation |
|
The global Wax Emulsion Market was valued at approximately USD 2.50 Billion in 2025 and is projected to reach USD 3.70 Billion by 2035, growing at a 4.3% CAGR, according to consensus industry estimates.
Demand is driven by the shift toward water-based, low-VOC coatings, growth in construction and automotive sectors, and rising consumer preference for sustainable, bio-based formulations across paints, adhesives, and packaging.
Asia Pacific leads with approximately 45% of global revenue, fueled by rapid industrialization, construction growth, and packaging demand. North America and Europe follow with roughly 24% and 19% shares respectively.
Key challenges include raw-material price volatility (particularly for waxes and emulsifiers), the limited shelf life of emulsions restricting distant distribution, and competition from solvent-based and silicone substitute products.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
We maintain a disciplined 70/30 primary-to-secondary research split. Our analysts conducted in-depth interviews with stakeholders across the wax emulsion value chain, including raw material suppliers (wax producers, emulsifier manufacturers), specialized producers, contract formulators and blenders, and global distributors. Respondents were screened to include decision-maker designations such as VP of Sourcing, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, ensuring that both technical and commercial perspectives informed our demand estimates.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory & Commercial Operations | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Wax Producers | 40% |
| Specialized Formulators & Blenders | 35% |
| Global Distributors & Traders | 25% |
Our secondary research leverages official multilateral trade databases—UN Comtrade, WTO, US ITC, and Eurostat—to validate cross-border flow patterns and regional consumption. Corporate annual filings (10-K, SEC filings, investor presentations) from leading producers provide capacity and revenue benchmarks. Patent databases and recognized non-profit technical standards and industry associations (such as ISO committees and national chemical councils) support our technology and compliance assessments. No competitor market-research firm data is used in our validation.
We triangulate market size using simultaneous top-down and bottom-up approaches. The top-down model allocates macroeconomic and industry-segment output data to wax emulsion consumption, while the bottom-up model builds from manufacturer capacity, product pricing, and validated end-use consumption. Discrepancies are reconciled through sensitivity analysis before finalizing base-year values and compound projections.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |