 Carbon Credit Validation Verification Certification Market
 2025
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 267

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Carbon Credit Validation Verification Certification Market
Khageshwar Rongkali
Senior Analyst
| Year | Market Size |
|---|---|
| 2025 | 367.0 M |
| 2026 | 455.0 M |
| 2027 | 565.0 M |
| 2028 | 702.0 M |
| 2029 | 872.0 M |
| 2030 | 1.080 B |
| 2031 | 1.340 B |

The carbon credit validation verification certification market covers independent third-party services that assess, monitor, and certify carbon offset and removal projects against recognized standards (VCS, Gold Standard, ISO 14064) to ensure credits are real, additional, measurable, and permanent.
This analysis covers third-party validation, verification, and certification services for compliance and voluntary carbon markets globally, segmented by service, type, sector, and region. It excludes the underlying carbon credit trading volumes, registry platform software, and in-house MRV technology hardware. This analysis does not cover carbon exchange operations or credit origination financing.
Published estimates diverge by an order of magnitude, reflecting definitional differences in what constitutes a "validation and verification" service versus the broader carbon project services envelope.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 366.6M → USD 2,069.2M | 2025 | 2033 | 24.2% | Third-party VVB and certification service revenue only | One published estimate |
| USD 4.45B → USD 18.22B | 2024 | 2035 | 13.67% | Broader carbon project validation, verification, certification, and registry-adjacent services | A competing analysis |
Our analysis suggests the narrower USD 366.6M base is the more defensible figure for pure-play validation and verification bodies, because the larger estimate appears to fold in registry fees, methodology development, and consultancy. Buyers budgeting for accreditation should anchor to the narrower series; strategists sizing the wider ecosystem should use the broader one.
Segmentation splits primarily by service function, market type, and end-use sector, with verification the dominant revenue engine and voluntary markets the largest demand pool.
| Parent Segment | Children |
|---|---|
| By Service | Validation, Verification, Certification |
| By Type | Compliance, Voluntary |
| By Sector | Agriculture & Forestry, Energy & Utilities, Industrial, Transportation, Waste Management |
Verification's 56.7% share reflects its recurring, project-lifecycle nature; validation is one-time and front-loaded, which caps its revenue ceiling. Energy & utilities at 26.9% signals where verification intensity is highest.
North America leads with 37.7% revenue share in 2025, driven by deep voluntary market infrastructure and US-based registries, while Asia Pacific posts the highest forecast CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.38% |
| Europe | 0.27% |
| Asia-Pacific | 0.23% |
| South America | 0.07% |
| Middle East & Africa | 0.06% |
| Region | 2025 Share |
|---|---|
| North America | 37.7% |
| Europe | 27.1% |
| Asia Pacific | 22.6% |
| Latin America | 7.1% |
| Middle East & Africa | 5.5% |
The Asia Pacific growth premium implies accreditation capacity will migrate eastward; buyers sourcing nature-based credits in Indonesia or India should expect verifier lead times to lengthen before they shorten.
Net-zero commitments, expanding compliance markets, and nature-based project growth drive demand, while cost complexity and standards fragmentation restrain it.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Net-zero corporate commitments | Driver | High | Verified credits needed to substantiate claims |
| Compliance market expansion (cap-and-trade, carbon taxes) | Driver | High | Mandatory verification triggers recurring demand |
| Carbon removal & nature-based projects | Driver | Medium-High | New methodologies require fresh validation |
| Digital MRV (satellite, AI, blockchain) | Driver | Medium | Lowers cost, widens access |
| Complexity and high cost of VVB processes | Restraint | High | Burden falls hardest on SME developers |
| Standards fragmentation across VCM/compliance | Restraint | Medium | Delays approvals, raises admin load |
The balance favors growth: drivers are structural and regulatory, restraints are operational and partially technology-addressable. Our analysis suggests digital MRV will shift, not eliminate, verifier value — toward methodology assurance and data integrity auditing.
The market is semi-concentrated, with standard-setters (Verra, Gold Standard) and accredited verifiers (SGS, DNV, Bureau Veritas) occupying distinct but interdependent roles.
| Company | Role | Differentiator |
|---|---|---|
| Verra | Standard-setter / registry | VCS scale and methodology breadth |
| Gold Standard | Standard-setter | Premium integrity brand, fastest-growing standard |
| Climate Action Reserve | Standard-setter / registry | US compliance-market linkage |
| American Carbon Registry | Standard-setter / registry | US voluntary and compliance bridge |
| SGS | Accredited verifier | Largest global verification footprint |
| DNV | Accredited verifier | Fastest-growing verifier, energy sector depth |
| Bureau Veritas | Accredited verifier | Industrial and transport sector reach |
| South Pole | Project developer / advisory | End-to-end origination plus verification advisory |
Differentiation rests on accreditation breadth and methodology ownership, not price. Verifiers with multi-standard accreditation face lower switching risk; standard-setters with registry lock-in enjoy durable moats.
Buyers should prioritize accredited verifiers with multi-standard coverage, because single-standard accreditation creates switching costs and re-validation risk when projects migrate between VCS, Gold Standard, and Article 6 frameworks. Procurement risk is concentrated in verifier capacity: lead times extend sharply during compliance-market deadline clusters.
Regulatory compliance is the sharpest selection criterion. Buyers operating in jurisdictions with mandatory disclosure (EU CSRD, US SEC climate rules) need verifiers whose certifications withstand audit scrutiny, not just registry acceptance. Our analysis suggests the cost of a failed verification — reputational and financial — dwarfs the fee differential between verifiers.
Operators should also model the cost of standards fragmentation into project economics: budget 10–20% contingency for re-validation where methodology uncertainty is high.
The balance of evidence favors the high-growth, narrow-definition view: validation and verification service revenue compounding near 24% through 2033, not the broader 13.67% envelope. The strongest counter-argument is that digital MRV and in-house monitoring could disintermediate low-complexity verification, compressing fees for commoditized project types.
We judge that risk real but second-order: technology raises the bar for what verification means, shifting value toward assurance and integrity auditing rather than eliminating it. Standard-setters with registry lock-in and verifiers with multi-standard accreditation will capture disproportionate share.
Actionable Strategy:
What would change our conclusion: evidence that in-house MRV achieves regulator acceptance at scale, or that standards harmonization collapses verification fees faster than volume grows.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
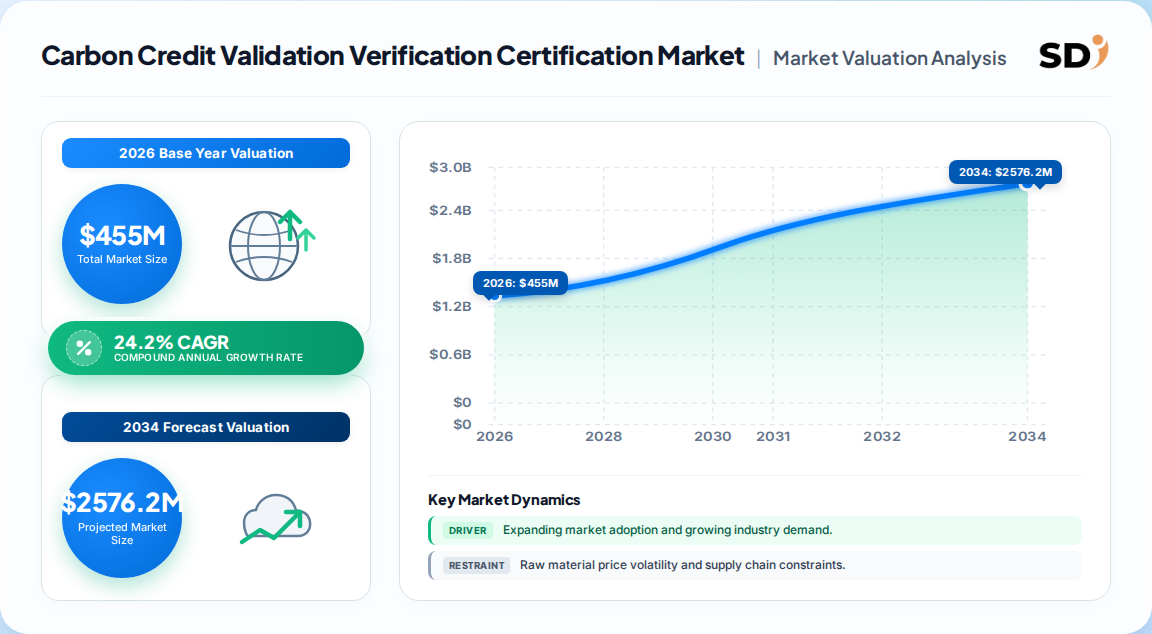
| Growth Rate | CAGR of 24.2% from 2020-2034 |
| Segmentation |
|
The global market was valued at USD 366.6 million in 2025 and is estimated at USD 455.0 million in 2026, projected to reach USD 2,069.2 million by 2033 at a 24.2% CAGR according to one published estimate.
Net-zero corporate commitments and expanding compliance carbon markets are the primary drivers, because both require independent verification to substantiate emissions claims and credit integrity.
North America led with 37.7% revenue share in 2025, supported by deep voluntary market infrastructure and US-based registries, while Asia Pacific is the fastest-growing region.
Leading players include Verra, Gold Standard, Climate Action Reserve, American Carbon Registry, SGS, DNV, Bureau Veritas, and South Pole, spanning standard-setting and accredited verification roles.
Estimates diverge because of definitional scope: narrow figures count pure-play verification service revenue, while broader figures include registry fees, methodology development, and consultancy-adjacent services.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a rigorous 70/30 primary-to-secondary split. In-depth interviews were conducted with stakeholders across the carbon value chain, including project developers, accredited validation and verification bodies, registry and standard-setting organizations, corporate credit buyers, and carbon market advisors. Decision-maker designations interviewed include Heads of Sustainability, Carbon Portfolio Managers, Accreditation Directors, and Commercial Operations Leads, ensuring coverage of both supply-side capacity and demand-side procurement behavior.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sustainability & Carbon Portfolio Leads | 35% |
| Accreditation & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Regulatory Affairs Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Accredited Verification Bodies | 40% |
| Standard-Setters & Registries | 25% |
| Project Developers | 20% |
| Corporate Credit Buyers | 15% |
Findings are cross-validated against official multilateral and standards databases, including UNFCCC registry data, ISO 14064 standards documentation, World Bank carbon pricing records, and national environmental agency filings. Corporate annual reports (10-K, SEC filings, investor presentations) from listed verification bodies and registries are analyzed alongside patent databases and recognized non-profit technical standards associations.
We triangulate simultaneously via a Top-Down allocation (macroeconomic climate policy spend and carbon market value segmented to verification services) and a Bottom-Up model (verifier capacity, accreditation counts, project pipelines, and fee schedules). Divergence between the two is reconciled against historical project verification volumes.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up verifier revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border project flow and registry allocation | High |
| Competitive Landscape | Leading market players | Annual reports and accreditation mapping | High |
