 Architectural Coatings Market
 Outlook 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 235

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Architectural Coatings Market
Khageshwar Rongkali
Senior Analyst
| Year | Market Size |
|---|---|
| 2025 | 89.80 B |
| 2026 | 92.50 B |
| 2027 | 96.00 B |
| 2028 | 99.70 B |
| 2029 | 103.5 B |
| 2030 | 107.4 B |
| 2031 | 111.5 B |

Architectural coatings are paints, primers, stains and protective finishes applied to buildings — interior and exterior walls, floors, roofs and trim — in residential and non-residential construction. They combine decorative function with surface protection against moisture, UV, chemicals and microbial growth, and are sold through dealers, retailers and professional trade channels.
This analysis covers global demand for architectural coatings by resin type, technology and end-use, across five regions and their principal country markets, with vendor and regulatory context. This analysis does not cover industrial OEM coatings, automotive refinish, marine and protective-heavy industrial coatings, powder coatings for appliances, or raw-material supply economics in isolation.
Published base-year estimates for 2025–2026 sit between roughly USD 86.5 billion and USD 100.3 billion, a spread too wide to ignore. The table below normalizes the competing figures so buyers can see exactly what each number measures.
| Estimate (base year) | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 89.8B (2025) | 2025 | 2033 | 3.8% | Full architectural segment, resin/technology/end-use split | One published estimate |
| USD 92.5B (2026) | 2026 | 2033 | 3.8% | Same scope, rolled forward one year | Derived from the above |
| USD 86.5B (2026) | 2026 | 2036 | 5.0% | Architectural coatings, supply-and-demand framing | A competing analysis |
| USD 100.3B (2026) | 2026 | 2031 | 4.33% | Broader resin taxonomy incl. polyester | A competing analysis |
| USD 93.4B (2026) | 2026 | 2034 | 3.0% | Architectural coatings, construction-led framing | A competing analysis |
Our analysis suggests the USD 90–93 billion band for 2026 is the most defensible. The USD 100 billion figure likely embeds a broader resin taxonomy and, possibly, adjacent protective products. The 5.0% CAGR case leans on an optimistic construction cycle; the 3.0% case is credible but assumes muted European renovation. For procurement and capacity planning, 3.5%–4.0% is the prudent planning band — a difference of one percentage point compounds to roughly USD 8–10 billion of annual demand by 2033.
Segmentation is stable across sources: resin chemistry determines performance, technology determines regulatory compliance, and end-use determines purchasing rhythm and channel.
| Parent | Children | Notable share signal |
|---|---|---|
| Resin type | Acrylic, Alkyd, Epoxy, Polyurethane, Polyester, Others | Acrylic 41%–54%; alkyd eroding under solvent limits |
| Technology | Waterborne, Solvent-borne, Others (powder, UV) | Waterborne 52%–55% and rising |
| End-use | Residential, Non-residential (commercial, institutional, infrastructure) | Residential 61%–68% |
| Function | Decorative, Protective/waterproofing, Primers & sealers | Decorative dominant; protective growing faster |
| Channel | Dealer/trade, Retail DIY, Direct-to-consumer e-commerce | E-commerce ~18% of urban volumes in mature metros |
The share divergence on acrylic (41% vs 54%) is a definitional artifact: narrower scopes classify styrene-acrylic hybrids separately, broader ones fold them in. Implication: any vendor benchmarking share must reconcile taxonomy before treating a rival's number as a threat.
Asia-Pacific leads with roughly 43%–46% of global value, driven by urbanization and housing delivery in China, India and ASEAN. China alone represents over 57% of the regional total, making any China slowdown immediately visible in global growth rates.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.44% |
| North America | 0.22% |
| Europe | 0.21% |
| Latin America | 0.07% |
| Middle East & Africa | 0.06% |
| Region | Share of global value |
|---|---|
| Asia-Pacific | 44% |
| North America | 22% |
| Europe | 21% |
| Latin America | 7% |
| Middle East & Africa | 6% |
The geography story is asymmetric. Asia-Pacific supplies volume growth; North America and Europe supply value growth through renovation of post-1970 housing stock, where repaint frequency exceeds new construction. This divergence implies two different commercial playbooks — volume-priced distribution in Asia, premium warranty-backed systems in the West — and vendors running one global pricing model will lose margin in both.
Renovation demand and low-VOC regulation are the two structural drivers; feedstock volatility and skilled-labour scarcity are the binding constraints. The balance currently favors volume stability over price expansion.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Renovation of aging housing stock | Driver | Strong | Repaint cycles recur independent of new-build starts |
| Low-VOC regulation | Driver (for waterborne) | Strong | Reformulation mandates shift mix toward compliant systems |
| Urbanization and housing programmes | Driver | Strong | Adds first-time coated surface area in emerging markets |
| Professional DIFM painter networks | Driver | Moderate | Bulk purchasing plus warranty-backed premium products |
| TiO₂ and epoxy feedstock volatility | Restraint | Moderate | Compresses formulator gross margin, delays price pass-through |
| Skilled painter scarcity | Restraint | Moderate | Extends project lead times to 8–12 weeks, deferring volume |
| Solvent-phase-out compliance cost | Restraint | Strong | Retooling costs fall disproportionately on small producers |
The critical second-order effect: regulation is not merely a cost — it is a competitive filter. Large producers amortize reformulation across global volume; small regional firms either license technology at 3%–5% of sales or exit premium segments. Our analysis suggests consolidation pressure will be most acute in mid-tier European and South Asian formulators over the next three to four years.
The competitive field is moderately concentrated, with global brands competing on formulation breadth and distribution reach against regional players competing on price, service and contractor loyalty.
| Vendor | Primary strength | Strategic posture |
|---|---|---|
| The Sherwin-Williams Company | Company-owned store network; trade loyalty | Channel control and DIFM services |
| AkzoNobel N.V. | Global decorative brands; sustainability positioning | Waterborne and bio-based reformulation |
| PPG Industries | Broad architectural portfolio; EMEA sustainability programme | Portfolio pruning toward premium segments |
| Nippon Paint Holdings | Asia-Pacific depth, especially China and Japan | Regional scale and JV structures |
| Asian Paints Ltd. | Emerging-market distribution density | Volume leadership in South Asia |
| Kansai Paint, BASF, Helios Group | Regional and specialty positions | Niche performance and industrial adjacency |
Differentiation increasingly rests on batch consistency, digital ordering and next-day delivery rather than colour range alone. Moats are distribution-based, not patent-based; proprietary colour-visualization and AR coverage tools reduce returns and over-ordering, quietly raising switching costs for dealers.
Procurement decisions should be anchored in compliance headroom, not unit price. With VOC ceilings tightening in California, the EU and Chinese Tier-3 cities, a product that meets today's limit may be unsaleable within one reformulation cycle. Buyers should contract for documented VOC and biocide profiles, not marketing claims.
Switching costs are asymmetric. For a formulator, changing resin systems requires re-validation of adhesion, durability and colour retention across substrates and climates — a multi-quarter exercise. For a contractor, switching brands risks batch mismatch on large façade jobs, which is why warranty-backed trade programmes retain loyalty even at a premium.
Key procurement risks: TiO₂ and epoxy feedstock spikes that trigger mid-project price revisions; skilled-applicator scarcity extending lead times; and dealer channel fragmentation as e-commerce takes share in dense urban markets. Buyers should build dual-source qualification and index-linked pricing into agreements, and should stress-test suppliers on reformulation capacity rather than catalogue breadth.
The balance of evidence favors a moderate-growth, mix-shift story rather than a volume story. Three of five published estimates converge near 3.5%–4.0% CAGR, and the segment data is unusually consistent: residential, acrylic and waterborne dominate across every source. The disagreement is about magnitude, not direction — which is exactly the condition in which mix positioning beats capacity expansion.
The strongest counter-argument is that Asian construction stimulus could re-accelerate volume faster than consensus assumes, validating the 5.0% case. That is plausible, but it is a policy bet, not a structural one; and it would not change the regulatory trajectory in Europe or North America, where solvent-based economics deteriorate regardless of demand.
What would change this conclusion: a sustained rebound in Chinese new-build starts above trend, or a regulatory pause on VOC ceilings in the EU, would both justify revisiting the growth band upward. Absent those, plan on 3.5%–4.0%. While this overview establishes the strategic frame, precise sub-segment forecasting, country-level share and vendor capacity mapping require the full report.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.8% from 2020-2034 |
| Segmentation |
|
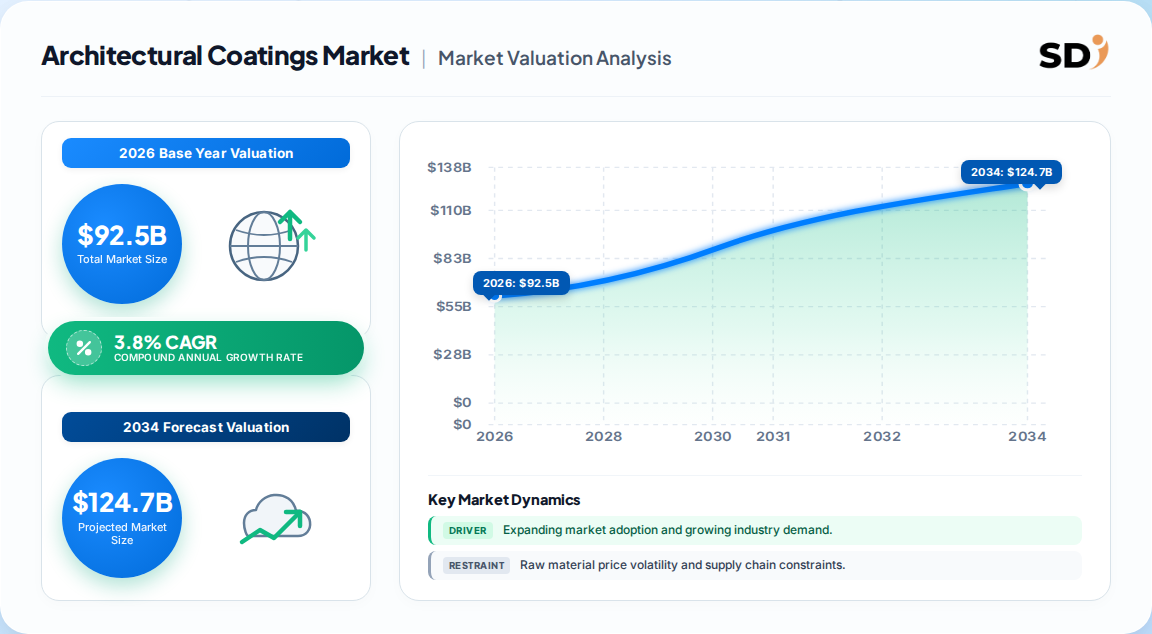
The global architectural coatings market was valued at approximately USD 89.8 billion in 2025 and is estimated near USD 92.5 billion in 2026. Published estimates range from USD 86.5 billion to USD 100.3 billion depending on whether adjacent protective coatings and broader resin categories are included.
Consensus forecasts sit between 3.0% and 5.0% CAGR through the early 2030s, with the most defensible planning band at 3.5%–4.0%. Faster cases assume Asian construction stimulus; slower cases assume muted European renovation activity.
Acrylic resins lead, accounting for roughly 41% to 54% of market value depending on taxonomy. Acrylics offer UV resistance, colour retention and compatibility with waterborne formulations, aligning with tightening emission rules and humid-climate performance requirements.
Asia-Pacific leads with approximately 44% of global value, and China alone represents over 57% of the regional total. North America and Europe follow, with growth driven mainly by renovation of post-1970 housing stock rather than new construction.
VOC ceilings in California, the EU and Chinese Tier-3 cities have effectively retired many solvent-rich formulations. Waterborne systems now hold just over half of global demand, and reformulation costs are pushing smaller producers toward licensing or exit.
Major players include The Sherwin-Williams Company, AkzoNobel, PPG Industries, Nippon Paint Holdings, Asian Paints, Kansai Paint, BASF and Helios Group. Competition centres on distribution reach, trade loyalty and reformulation capacity rather than patents.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Structured depth interviews were conducted across the value chain with five company types: titanium dioxide and resin suppliers, specialized architectural coatings producers, contract formulators and private-label blenders, national distributors and dealer networks, and large-scale painting contractors. Within these organizations we engaged decision-makers holding VP of Sourcing, Head of R&D and Formulation, Technical Director, and Commercial Operations Lead designations. Interviews captured formulation constraints, channel economics, reformulation timelines and compliant-product substitution behaviour.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 35% |
| Procurement & Sourcing Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Resin & TiO₂ Suppliers | 25% |
| Architectural Coatings Producers | 35% |
| Contract Formulators & Blenders | 22% |
| Distributors & Dealer Networks | 18% |
Secondary validation draws on UN Comtrade and Eurostat trade flows for paints, varnishes and pigment inputs; US ITC and national customs records; corporate 10-K and annual investor filings for capacity and segment disclosure; patent databases for waterborne and bio-based formulation activity; and recognized technical standards bodies and industry associations covering VOC limits and coating performance. No third-party market research publisher is used as a validation source.
Top-down allocation uses macroeconomic construction and renovation expenditure, split by residential and non-residential segment, then crossed with regional coating intensity per square metre. Bottom-up modeling aggregates manufacturer capacity, realized pricing per litre and end-use consumption by channel. The two are reconciled at regional level before global aggregation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
