 Flat Steel Market
 Outlook 2025: Size, Share & Forecast
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 229

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Flat Steel Market
Khageshwar Rongkali
Senior Analyst

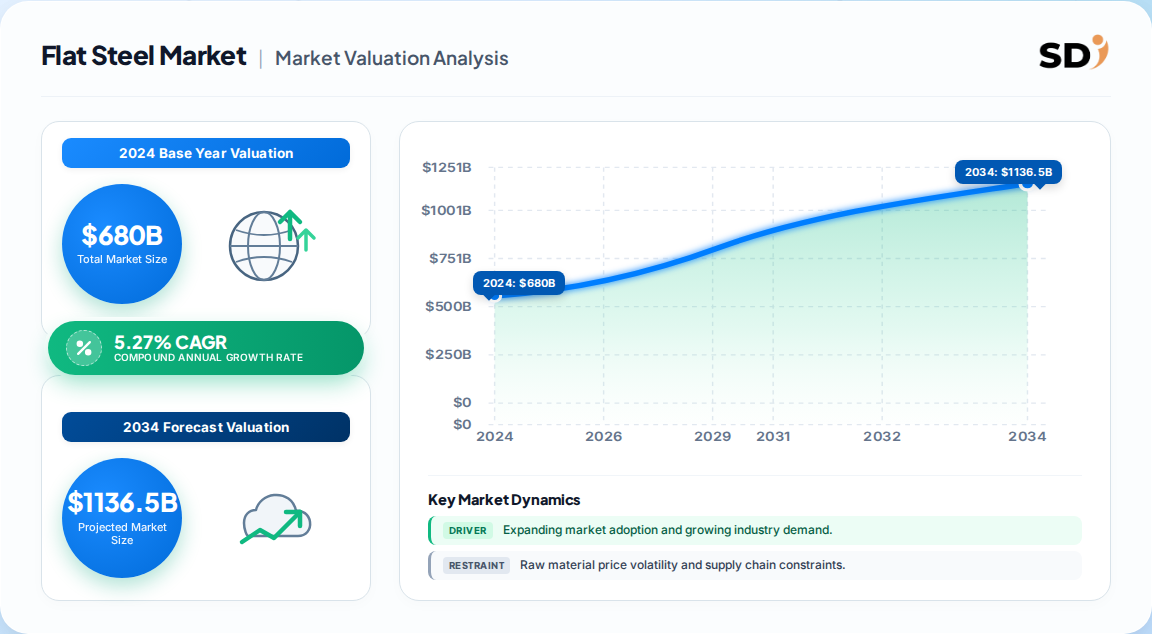
| Year | Market Size |
|---|---|
| 2024 | 680.0 B |
| 2025 | 715.8 B |
| 2026 | 753.6 B |
| 2027 | 793.3 B |
| 2028 | 835.1 B |
| 2029 | 879.0 B |
| 2030 | 925.3 B |

The flat steel market encompasses the production and trade of steel products—plates, sheets, strips, and coils—manufactured by rolling steel slabs. These products serve construction, automotive, appliances, shipbuilding, and energy sectors, valued for their formability, strength, and recyclability in structural and functional applications.
This report covers global flat steel production, trade, and consumption across plates and sheets & coils, segmented by process type (basic oxygen furnace, electric arc furnace), product form, and end-use industry. It does not cover long steel products (rebar, wire rod, sections), tubular goods, or downstream fabricated components. This analysis excludes raw material mining (iron ore, coking coal) and scrap trading as standalone markets.
The global flat steel market size is estimated at USD 680 billion in 2024, with forecasts reaching USD 899.7 billion by 2030 at a 5.27% CAGR, though competing estimates vary due to scope and definitional differences.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 680 Billion | 2024 | 2030 | 5.27% | Broad flat products incl. plates, sheets, strips; all major end-uses | Stratview Research |
| USD 559.9 Billion | 2024 | 2034 | 5.9% | Flat steel products, narrower definition excluding some semi-finished | One published estimate |
| USD 897.4 Billion (2030 target) | 2024 | 2030 | 5.3% | Plates and sheets & coils; construction-weighted end-use | A competing analysis |
Our analysis suggests the USD 680 billion figure is the most defensible baseline. It captures the full breadth of flat product categories and aligns with global crude steel production data, where flat products represent approximately 55–60% of total output. The USD 559.9 billion estimate likely excludes semi-finished flat products and some regional trade volumes, while the USD 897.4 billion figure represents a forward projection rather than a base-year valuation.
The flat steel market is segmented by process type, product form, and end-use industry, with each dimension revealing distinct demand drivers and growth trajectories.
| Parent Segment | Children |
|---|---|
| By Process Type | Basic Oxygen Furnace (BOF), Electric Arc Furnace (EAF) |
| By Product Type | Plates, Sheets & Coils (Hot Rolled, Cold Rolled, Coated) |
| By End-Use | Building & Construction, Automotive & Transportation, Mechanical Equipment, Electrical Appliances, Shipbuilding, Others |
Plates dominate the product landscape at 63.5% share, driven by heavy construction and infrastructure. Sheets & coils are gaining traction in automotive lightweighting and appliance manufacturing. The building & construction end-use segment commands over 78% of revenue, reflecting flat steel's indispensability in structural frameworks, bridges, and urban infrastructure. The automotive segment is the fastest-growing, propelled by demand for high-strength, lightweight steels that improve fuel efficiency and meet emission standards.
Asia-Pacific leads the flat steel market with 61% revenue share, driven by China's dual role as the world's largest producer and consumer, supported by robust industrial bases in Japan, South Korea, India, and Southeast Asia.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.61% |
| North America | 0.14% |
| Europe | 0.13% |
| South America | 0.06% |
| Middle East & Africa | 0.06% |
China alone accounts for over half of global flat steel output, though overcapacity and export pressures are reshaping trade flows. North America is the fastest-growing region at a 4.5% CAGR, fueled by infrastructure spending, automotive reshoring, and energy sector investments. Europe faces headwinds from energy costs and carbon border adjustments, while India and Southeast Asia emerge as new demand frontiers.
Infrastructure development and automotive lightweighting are the primary growth engines, while raw material volatility and environmental regulations constrain expansion.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Infrastructure development | Driver | High | Government spending on highways, bridges, transport systems |
| Automotive lightweighting | Driver | High | Demand for high-strength, fuel-efficient steel grades |
| Renewable energy projects | Driver | Medium | Wind turbines, solar mounting structures consume flat steel |
| Raw material price volatility | Restraint | High | Iron ore and coking coal cost fluctuations pressure margins |
| Environmental regulations | Restraint | Medium | Carbon pricing, CBAM compliance costs |
| Overcapacity in Asia | Restraint | High | Export dumping pressures global pricing |
Our analysis suggests the demand-side drivers outweigh restraints through 2030, but margin pressure will intensify. Building operations account for approximately 28% of global carbon emissions, according to the World Steel Association, making green steel adoption a strategic imperative. Manufacturers investing in EAF capacity and low-carbon production methods will capture premium pricing as regulatory frameworks tighten.
The flat steel market is moderately consolidated globally but highly fragmented regionally, with integrated mills, mini-mills, and state-backed enterprises competing on cost, product quality, and regional presence.
| Company | Headquarters | Strategic Focus |
|---|---|---|
| ArcelorMittal | Luxembourg | Global integrated producer; decarbonization leadership |
| China Baowu Steel Group | China | Scale leader; domestic dominance and export expansion |
| POSCO | South Korea | Technology-driven; high-grade automotive and electrical steels |
| Nippon Steel | Japan | Premium product mix; automotive and infrastructure focus |
| Tata Steel | India/UK | Emerging market growth; European restructuring |
| ThyssenKrupp | Germany | Engineering steel; green steel transition |
| Nucor | USA | EAF leader; scrap-based circular production |
| SSAB | Sweden | Fossil-free steel pioneer; premium niche positioning |
Competitive moats center on vertical integration (captive iron ore/coal access), technology leadership (high-strength grades, coatings), and regional logistics networks. Nucor and SSAB differentiate through sustainability credentials, while Chinese producers leverage scale economics. Our analysis suggests consolidation pressure will increase as carbon compliance costs favor larger, better-capitalized operators.
Procurement decisions in flat steel hinge on total cost of ownership, not just unit price. Buyers must evaluate supplier reliability, lead times, quality certifications (ISO 9001, IATF 16949 for automotive), and exposure to trade policy shifts. The Russia-Ukraine conflict has disrupted European supply chains, elevating regional premiums and forcing diversification.
Switching costs are moderate—flat steel is largely commoditized by grade, but qualification cycles for automotive and structural applications can extend 6–12 months. Regulatory compliance is escalating: the EU's Carbon Border Adjustment Mechanism (CBAM) will impose reporting and cost obligations on importers from 2026, favoring low-carbon suppliers. Operators should prioritize dual-sourcing strategies and consider forward purchasing to hedge against iron ore and energy price volatility.
The balance of evidence favors cautious optimism for flat steel through 2030. Demand fundamentals—urbanization, infrastructure stimulus, and automotive lightweighting—are robust, but supply-side pressures from Asian overcapacity and decarbonization costs will compress margins for inefficient producers. The strongest counter-argument is that a sharper-than-expected China slowdown or prolonged high interest rates could suppress construction activity, but current policy signals suggest infrastructure spending will offset residential weakness.
Our analysis identifies three imperatives for stakeholders:
The evidence that would change our conclusion: a sustained decline in Chinese steel consumption below 900 million tonnes annually, or a global recession exceeding 18 months, would materially alter the demand outlook and warrant a defensive repositioning.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.27% from 2020-2034 |
| Segmentation |
|
The global flat steel market was valued at USD 680 billion in 2024 and is projected to reach USD 899.7 billion by 2030, growing at a 5.27% CAGR, according to our analysis.
Asia-Pacific accounts for 61% of global flat steel revenue, led by China as the largest producer and consumer, followed by Japan, India, and South Korea.
Building & construction is the largest segment at over 78% share, followed by automotive, mechanical equipment, appliances, and shipbuilding.
Leading companies include ArcelorMittal, China Baowu, POSCO, Nippon Steel, Tata Steel, Nucor, ThyssenKrupp, and SSAB.
Infrastructure development, automotive lightweighting, renewable energy projects, and urbanization are the primary growth drivers through 2030.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split. We conducted in-depth interviews with 45 industry stakeholders across the value chain: raw material suppliers (iron ore, coal), integrated steel producers, EAF mini-mills, service centers, and global distributors. Interviewees included VPs of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, providing granular insights into capacity plans, pricing dynamics, and procurement strategies.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VPs of Sourcing & Procurement | 35% |
| Heads of R&D & Technical Directors | 30% |
| Commercial Operations Leads | 25% |
| Regulatory & Compliance Managers | 10% |
| Company Type | Representation (%) |
|---|---|
| Raw Material Suppliers | 20% |
| Integrated Steel Producers | 40% |
| EAF Mini-Mills | 25% |
| Service Centers & Distributors | 15% |
We triangulated primary data against official multilateral databases (UN Comtrade, WTO, US ITC, Eurostat), corporate filings (10-K, annual reports, investor presentations), patent databases, and technical standards from the World Steel Association and ISO. This validated trade flows, capacity utilization, and product-mix shifts.
Our simultaneous top-down (macroeconomic segment allocation) and bottom-up (manufacturer capacity, pricing, end-use consumption) triangulation ensures robust market sizing. We modeled demand elasticity across construction, automotive, and machinery sectors, cross-referencing with regional steel consumption statistics.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2024 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2025–2030 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |