 North America Blow Molded Plastics Market
 2025
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 188

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 North America Blow Molded Plastics Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2025 | 29.86 B |
| 2026 | 31.95 B |
| 2027 | 34.19 B |
| 2028 | 36.59 B |
| 2029 | 39.16 B |
| 2030 | 41.90 B |
| 2031 | 44.84 B |

The North America blow molded plastics market covers the manufacture and sale of hollow thermoplastic parts—bottles, containers, automotive fuel tanks, ducting, and medical devices—produced via extrusion, injection, stretch, and compound blow molding across the United States, Canada, and Mexico.
This analysis covers blow molded plastic products by technology, resin, and application across the US, Canada, and Mexico, valued at manufacturer-level revenue for 2025–2034. This analysis does not cover injection molded or thermoformed plastics, plastic film and sheet, resin production sold as feedstock, or blow molding machinery and tooling.
Published estimates diverge materially because base years, currency timing, and product definitions differ. The table below reconciles the leading figures cited for this region.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 29.86 Billion | 2025 | 2034 | 7.01% | Regional blow molded plastic products, manufacturer revenue | One published regional forecast |
| 16.66 Billion | 2021 | 2030 | ~4.5% | Regional blow molded plastics, historic COVID-affected base | A competing analysis |
| 31.95 Billion | 2026 | 2034 | 7.01% | Same regional series, one year forward | One published regional forecast |
Our analysis suggests the 2025 figure of USD 29.86 billion is the most defensible base, because it captures post-pandemic demand normalization, e-commerce packaging expansion, and the EV-driven automotive shift. The lower 2021 benchmark reflects supply-chain disruption, not structural weakness. Divergence of this magnitude implies buyers should normalize for base-year effects before benchmarking vendor performance.
Segmentation follows three non-geographic axes—technology, resin product, and application—each with a distinct growth profile that shapes where capital should flow.
| Parent segment | Children | Leading position |
|---|---|---|
| By Technology | Extrusion, Injection, Stretch, Compound blow molding | Extrusion at 55.1% share (2025) |
| By Product | Polyethylene, PET, Polypropylene, Polystyrene, ABS, PVC, Polyamide, Others | Polyethylene at 45.6% share (2025) |
| By Application | Packaging, Automotive & Transport, Building & Construction, Medical, Consumables & Electronics, Others | Packaging at 40.8% share (2025) |
Extrusion's dominance reflects low tooling cost and scalable hollow-part output. Stretch blow molding's 6.2% CAGR signals a shift toward high-clarity PET beverage and personal care formats, a trend that will pressure extrusion's share modestly by 2034.
The United States leads decisively, accounting for 75.7% of regional revenue in 2025, supported by dense industrial manufacturing, e-commerce logistics, and a mature packaging converter base.
North America
United States — 75.7% share (2025)
Canada — single-use plastics ban reshaping resin choices
Mexico — automotive lightweighting and cross-border trade hub
United States: 75.7%
Canada: ~14.8%
Mexico: ~9.5%
Canada's regulatory posture—its 2022 single-use plastics ban—makes it the region's sustainability proving ground. Mexico's automotive corridor and nearshoring inflows give it the highest incremental growth potential, though from a smaller base. The concentration in the US means regional forecasts are effectively US forecasts; buyers should demand country-level granularity to avoid overpaying for exposure they already hold.
Packaging demand and automotive lightweighting are the dominant growth engines, while environmental regulation and resin price volatility are the binding constraints.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Packaging & e-commerce demand | Driver | High | Lightweight durable containers replace glass and metal |
| Automotive lightweighting and EVs | Driver | High | Fuel tanks, air ducts, battery housings, cooling systems |
| Medical single-use devices | Driver | Medium-High | Sterile IV bottles, device housings, aging demographics |
| Single-use plastics regulation | Restraint | High | California SB 54, Canada ban raise compliance cost |
| Resin price volatility | Restraint | Medium | Petroleum-linked PE/PP costs squeeze converter margins |
| Bioplastics and chemical recycling | Opportunity | Medium | PLA, bio-PE, closed-loop monomer recovery |
Our reading of the balance: drivers are structural and demand-led, restraints are regulatory and cost-led. That asymmetry favors converters with recycling infrastructure and long-term resin contracts. The regulatory pressure is not a cyclical headwind—it is a permanent repricing of non-recyclable capacity, which implies margin compression for laggards.
Market structure is highly competitive, with packaging conglomerates and resin specialists competing on sustainability, automation, and circular-economy credentials.
| Company | Primary positioning | Differentiation lever |
|---|---|---|
| Berry Global | Global packaging conglomerate | Recycled-content lightweight containers |
| Amcor plc | Rigid and flexible packaging | Material-reduction design, recyclability |
| Graham Packaging | Custom rigid containers | Customer-specific tooling and design |
| Plastipak Holdings | PET containers and recycling | Vertically integrated recycling |
| AptarGroup | Dispensing and closure systems | Precision and healthcare applications |
| Silgan Holdings | Closures and containers | Scale and cost discipline |
Moats in this sector come from tooling libraries, long-term customer qualification cycles, and recycling feedstock access—not from resin chemistry alone. Berry's and Amcor's 2026 sustainable-packaging expansions indicate that recycled-content capacity is becoming the primary competitive axis. Smaller regional molders without recycling integration face the sharpest margin risk.
Procurement decisions should hinge on four criteria: recyclability compliance, tooling amortization, resin-price pass-through terms, and multi-layer barrier capability. California's SB 54 requires all single-use packaging to be recyclable or compostable by 2032, so contracts extending past that date carry regulatory risk unless suppliers demonstrate compliant resin portfolios.
Switching costs are moderately high. Custom tooling, FDA food-contact qualification, and automotive safety validation create multi-quarter requalification cycles. Operators should also price in resin volatility clauses—PE and PP remain petroleum-linked—and favor suppliers with demonstrated chemical-recycling or bio-resin capability. The practical implication: buyers should negotiate sustainability KPIs into contracts now, while suppliers still need volume commitments to justify recycling capex.
The balance of evidence favors a constructive outlook for the North America blow molded plastics market, with 7.01% CAGR through 2034 being more defensible than the global-average 6.2–6.8% because US e-commerce packaging, EV lightweighting, and medical single-use demand compound simultaneously. The strongest counter-argument is regulatory: if California and Canadian rules tighten faster than recycling capacity scales, volume growth in single-use formats could underperform. That risk is real but concentrated in non-recyclable formats, not the category.
Our analysis suggests the market is undergoing a sustainability-driven repricing rather than a demand slowdown. Vendors that invest in recycled-content and bio-based resins before 2027 will capture qualification advantages that compound over automotive and medical cycles, where requalification is slow and sticky. Lagging converters will face both regulatory exclusion and margin compression.
Evidence that would change this conclusion: a sustained reversal in US e-commerce packaging volumes, or a federal preemption of state plastics rules that removes compliance pressure, would weaken the sustainability-driven thesis.
| Region | Market Share (%) |
|---|---|
| United States | 0.76% |
| Canada | 0.15% |
| Mexico | 0.1% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.01% from 2020-2034 |
| Segmentation |
|
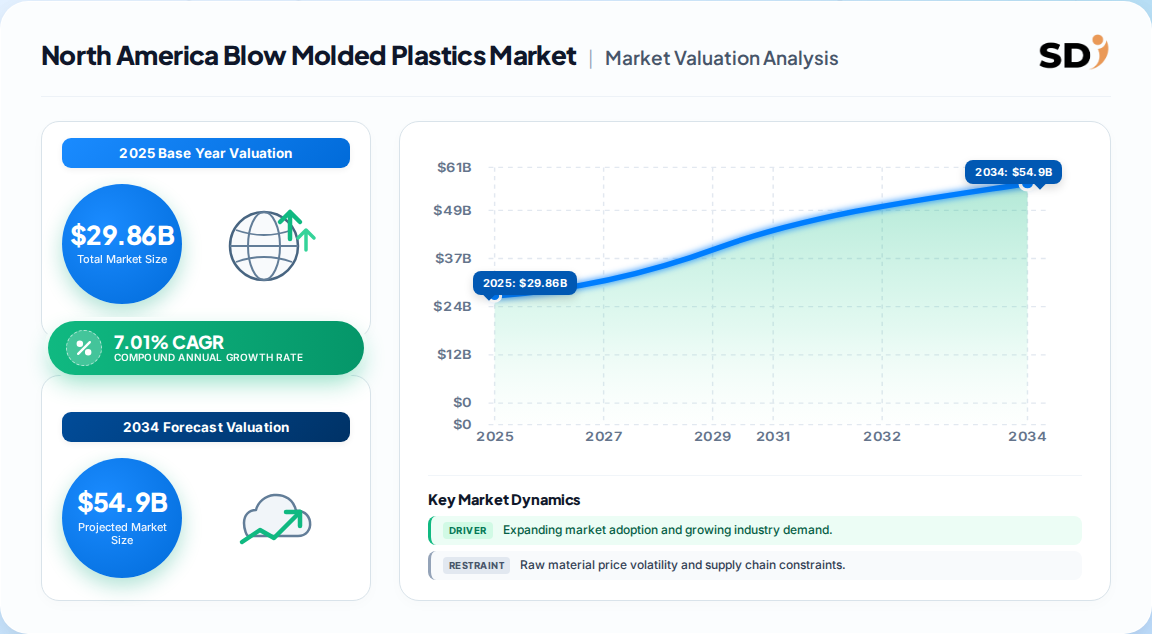
The market was valued at USD 29.86 billion in 2025 and is projected to reach USD 54.94 billion by 2034, growing at 7.01% CAGR from 2026 to 2034.
Extrusion blow molding held 55.1% share in 2025, favored for cost-effective hollow container production. Stretch blow molding is the fastest-growing technology at 6.2% CAGR.
The United States accounted for 75.7% of regional revenue in 2025, supported by dense packaging, automotive, and medical manufacturing and e-commerce logistics.
Medical applications are projected to grow at 6.5% CAGR, propelled by single-use sterile healthcare devices, IV bottles, and aging demographic requirements.
Single-use plastics regulation—including California SB 54 and Canada's 2022 ban—raises compliance costs and forces investment in recyclable and compostable materials.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the blow molded plastics value chain, including resin suppliers, specialized blow molders, contract packaging converters, and regional distributors. Interviewees included VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement, formulation, regulatory, and commercial perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| R&D & Technical Directors | 35% |
| Regulatory & Commercial Operations | 30% |
| Company Type | Representation (%) |
|---|---|
| Resin & Polymer Suppliers | 40% |
| Blow Molders & Converters | 35% |
| Packaging & Automotive OEMs | 25% |
We validated primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and 10-K disclosures, patent databases, and recognized technical standards bodies and industry associations. This triangulation anchors segment sizing and confirms cross-border flow patterns.
We ran simultaneous top-down and bottom-up models. The top-down model allocates macroeconomic and end-use segment demand across packaging, automotive, medical, and construction. The bottom-up model builds manufacturer capacity, product pricing, and end-use consumption into a revenue estimate. Convergence of both models at the base year validates the market size.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2034 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | US, Canada, Mexico share | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |