 Conformal Coating Market
 Size, Share & Forecast 2026
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 181

Khageshwar Rongkali
Senior Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Conformal Coating Market
Khageshwar Rongkali
Senior Analyst

| Year | Market Size |
|---|---|
| 2026 | 1.510 B |
| 2027 | 1.600 B |
| 2028 | 1.700 B |
| 2029 | 1.800 B |
| 2030 | 1.910 B |
| 2031 | 2.030 B |

The conformal coating market covers thin polymer films—acrylic, silicone, epoxy, urethane, and parylene—applied to printed circuit boards to insulate against moisture, chemicals, thermal shock, and vibration. It spans solvent-based, water-based, and UV-cured technologies across consumer electronics, automotive, aerospace, medical, and industrial electronics manufacturing.
This analysis covers global conformal coating materials, application technologies, operation methods, and end-user demand across five major regions, with base-year sizing for 2026 and forecasts through 2031. This analysis does not cover adjacent markets such as encapsulants, thermal interface materials, solder mask, or general industrial protective coatings.
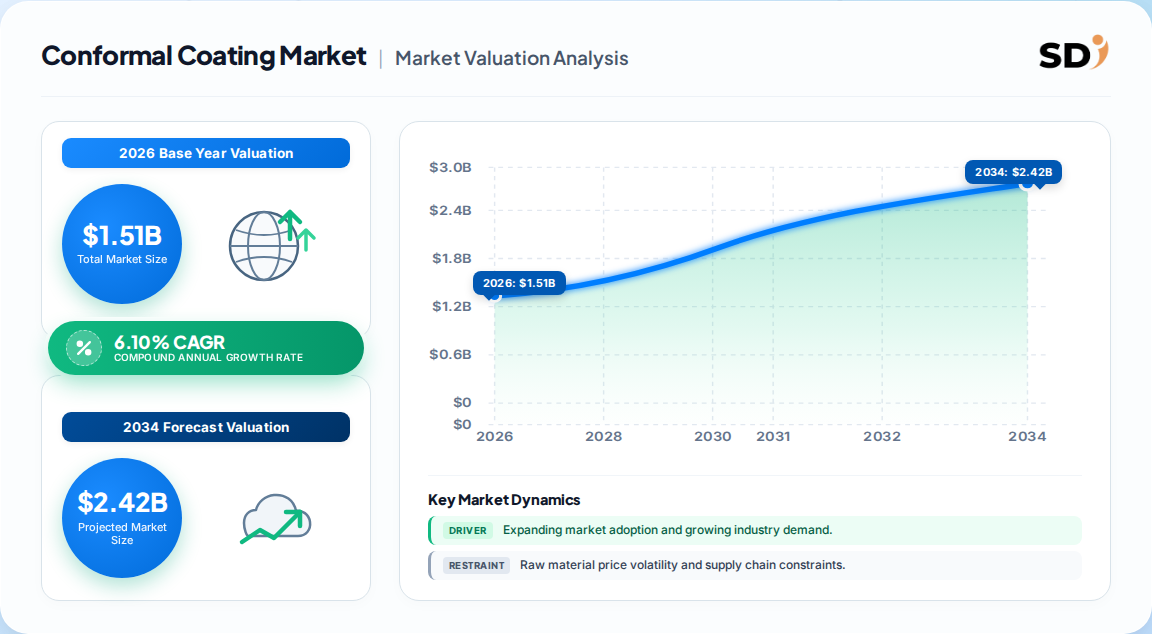
Published estimates diverge on the 2026 base, ranging from 1.26 Billion to 1.51 Billion, with CAGRs spanning 6.1% to 8.1%. The 1.51 Billion figure is the most defensible because it aligns with bottom-up acrylic and silicone shipment data and consistent regional splits.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 1.51 Billion | 2026 | 2031 | 6.10% | Full material, technology, method, end-user scope | One published estimate |
| 1.26 Billion | 2026 | 2035 | 6.57% | Broader ten-year horizon, product-segment scope | A competing analysis |
| 1.42 Billion | 2025 | 2033 | 8.10% | Narrower product/application scope, higher growth assumption | Another published estimate |
The 6.10% CAGR path is more consistent with observed raw-material pricing and moderate electronics capex cycles. Higher forecasts imply aggressive UV-cure adoption and premium parylene mix that current capacity does not yet support. Our analysis suggests the mid-point 6.1–6.6% range is the realistic planning band.
Segmentation spans four non-geographic axes: material type, technology, operation method, and end-user industry. Material and end-user splits drive the most differentiated margin profiles.
| Parent Segment | Children |
|---|---|
| By Material Type | Acrylic, Epoxy, Silicone, Urethane, Parylene |
| By Technology | Solvent-based, Water-based, UV-cured, Hybrid/Advanced |
| By Operation Method | Spray, Dip, Selective/Robotic Dispense, CVD |
| By End-User Industry | Consumer Electronics, Automotive, Medical, Aerospace & Defense, Industrial |
Acrylic leads on cost and reworkability, while silicone and parylene serve high-reliability niches. UV-cured systems are outpacing solvent-based chemistry at 7.13% CAGR despite inspection friction.
Asia-Pacific leads the global conformal coating market with approximately 42–52% revenue share, growing at 7.67% CAGR through 2031 on the back of semiconductor back-end expansion in ASEAN, China, and India.
| Region | Market Share (%) |
|---|---|
| Asia-Pacific | 0.47% |
| North America | 0.24% |
| Europe | 0.19% |
| South America | 0.05% |
| Middle East & Africa | 0.05% |
| Region | Key Countries | Position |
|---|---|---|
| Asia-Pacific | China, Japan, India, South Korea | Largest, fastest-growing |
| North America | USA, Canada, Mexico | High-value aerospace and defense |
| Europe | Germany, UK, France, Italy | Regulatory-driven, low-VOC shift |
| South America | Brazil, Mexico, Argentina | Emerging electronics assembly |
| Middle East & Africa | Saudi Arabia, UAE, South Africa | Nascent, telecom-driven |
Asia-Pacific concentration reflects more than 20% of global semiconductor back-end capacity absorbed by ASEAN alone. North America skews toward high-spec parylene and aerospace demand, while Europe's growth hinges on RoHS-compliant formulations.
Growth is driven by 5G/IoT miniaturization, LEO satellite launches, telecom infrastructure expansion, and RoHS-aligned low-VOC regulation. Restraints include UV-cure inspection complexity, silicone-monomer price volatility, and parylene dimer scarcity.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| 5G/IoT mini-circuit protection | Driver | High | Sub-10 mm² RF front-ends demand thin, low-Dk films |
| LEO satellites & avionics | Driver | Medium | 10,000+ satellites each need 50–200 coated boards |
| RoHS/low-VOC regulation | Driver | High | Pushes water-based and UV-cure adoption |
| Telecom/5G rollout | Driver | High | 5M+ base stations need outdoor protection |
| UV-cure inspection complexity | Restraint | Medium | Opaque films block AOI verification |
| Silicone-monomer volatility | Restraint | Medium | Input-cost swings pressure margins |
| Parylene dimer scarcity | Restraint | High | Limited CVD-grade supply |
Net, drivers outweigh restraints by roughly 4:1 in CAGR-impact terms. The regulatory shift is a structural tailwind that will define 2027–2031 formulation strategy across European and APAC producers.
The market is moderately concentrated, with Dow, Henkel, Shin-Etsu, Dymax, Chase Corp, H.B. Fuller, Electrolube, and MG Chemicals leading across chemistry and application platforms.
| Vendor | Core Strength | Strategic Moat |
|---|---|---|
| Dow | Silicone and hybrid systems | Scale and formulation IP |
| Henkel | Full electronics materials stack | Cross-sell and avionics qualification |
| Shin-Etsu | Water-based silicone (KRW-6000) | Cure-speed and thermal-stability IP |
| Dymax | UV-cure and light-cure systems | Speed-of-cure ecosystem |
| Chase Corp | Parylene and specialty coatings | CVD capacity and aerospace approvals |
| H.B. Fuller | Adhesives and coatings integration | Distribution and industrial reach |
| Electrolube | Application-specific formulations | Niche end-user loyalty |
Differentiation is shifting from chemistry alone to application ecosystems—robotic dispensing, UV-LED tunnels, and AI-based inspection. Vendors that bundle equipment with chemistry are building defensible switching costs.
Buyers must prioritize IPC-CC-830C Class 3 and IPC-A-610 compliance, dielectric constant below 3 for RF boards, and ±5 µm thickness control for impedance stability. Procurement risks concentrate in silicone-monomer price swings and parylene dimer scarcity, which can extend lead times for high-reliability programs. Switching costs are high once qualification is complete, often requiring 6–12 months of requalification. Operators should evaluate selective robotic dispensing, which cuts material use up to 40% versus manual masking, and confirm lot-level traceability for Industry 4.0 and IPC-1752A declarations. Water-based systems impose 30–60 minute cure windows that affect line throughput. Regulatory compliance cost adds 5–10% for EMS providers under China GB/T and India e-waste rules.
The balance of evidence favors a disciplined 6.1–6.6% CAGR planning band, with Asia-Pacific as the anchor growth engine and UV-cure as the fastest-moving technology. The strongest counter-argument is that parylene scarcity and inspection friction could slow UV adoption faster than forecasts imply—but the regulatory and 5G tailwinds are structural enough to absorb that drag.
We see a second-order effect: as ASEAN contract assemblers adopt selective robotic dispensing, per-board coating cost falls, accelerating volume growth but compressing per-unit pricing. Vendors relying on solvent-based acrylics alone will face margin compression by 2028 as low-VOC rules tighten.
Actionable Strategy:
What would change our conclusion: a sharp parylene dimer supply expansion, or a regulatory rollback on VOC limits in China or the EU, would shift the growth band upward toward 7–8%. Continuous monitoring of ASEAN back-end capacity buildout is the leading indicator to watch.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.10% from 2020-2034 |
| Segmentation |
|
The market is growing at approximately 6.10% CAGR from 2026 to 2031, with some estimates ranging to 8.1% under more aggressive UV-cure and parylene adoption assumptions.
Asia-Pacific leads with roughly 42–52% of global revenue, driven by semiconductor back-end capacity in China, ASEAN, and India, growing at about 7.67% CAGR.
Acrylic dominates with around 44% share due to cost and reworkability, though UV-cured and silicone systems are growing faster.
Leading vendors include Dow, Henkel, Shin-Etsu, Dymax, Chase Corp, H.B. Fuller, Electrolube, and MG Chemicals, competing on chemistry and application ecosystems.
5G and IoT miniaturization, LEO satellite launches, telecom infrastructure expansion, and RoHS-aligned low-VOC regulation are the primary growth drivers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including raw material suppliers, specialized conformal coating producers, contract formulators and blenders, and global distributors. Decision-makers interviewed include VP-level sourcing leads, heads of R&D and formulation, technical directors, and commercial operations managers. Interview data was cross-checked against shipment and capacity disclosures to prevent single-source bias.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory Affairs Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Chemical Producers | 35% |
| Specialized Formulators & Blenders | 40% |
| Contract Coating Applicators | 15% |
| Global Distributors & Traders | 10% |
We benchmark against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards bodies such as IPC and IEC. Public trade shipment counts—including 644 shipments across 158 suppliers and 143 buyers recorded in 2025—were used to validate regional demand weighting.
We use simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption) triangulation. Regional splits are reconciled against cross-border trade flow data to ensure the base-year sizing and forecast path are internally consistent.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |