 Us Publishing Market
U.S. Publishing Market Size, Share & Forecast to 2033
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 226

Srinwanti Kar
Senior Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Publishing Market
Srinwanti Kar
Senior Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 64.60 B |
| 2026 | 65.80 B |
| 2027 | 67.40 B |
| 2028 | 69.00 B |
| 2029 | 70.70 B |
| 2030 | 72.40 B |
| 2031 | 74.10 B |

The U.S. publishing market is the revenue generated by creating, editing, producing, and distributing books, newspapers, magazines, journals, articles, and research papers across hard copy, e-book, and audiobook formats. It spans trade, educational, academic, and news publishers operating in the United States.
This analysis covers U.S.-based publishing revenue across book, newspaper, magazine, and academic/journal output in hard copy, e-book, and audiobook formats, including digital-first and self-publishing platforms. Sub-unit revenue is assessed at the state level.
This analysis does not cover printing and binding services, paper manufacturing, book retailing, device manufacturing, or non-U.S. publishing revenue except as comparative context.
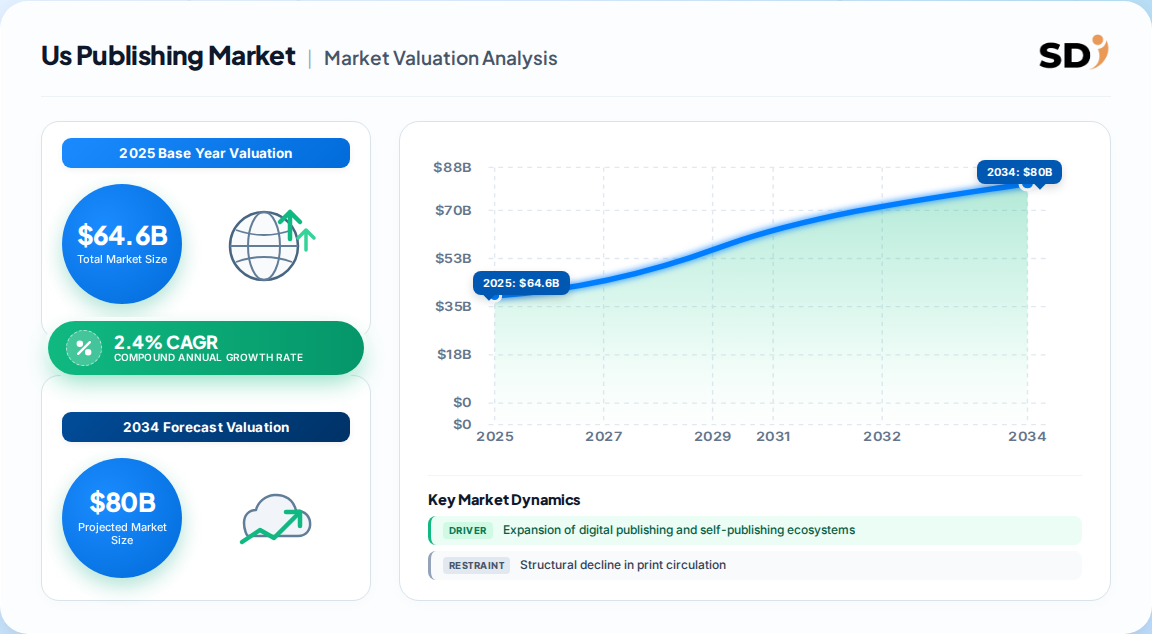
The U.S. publishing market reached USD 64.6 billion in 2025 and is projected to grow from USD 65.8 billion in 2026 to USD 77.9 billion by 2033, a 2.4% CAGR. Two published estimates set the base differently, however, and the gap matters.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 64.6 Billion | 2025 | 2033 | 2.4% | All publishing types, all formats, U.S. only | One published market estimate |
| ~30 Billion | Annual | n/a | n/a | Publisher-reported domestic revenue, trade and educational focus | Association of American Publishers (AAP) |
| 77.9 Billion | 2033 | 2033 | 2.4% | Projected total, same broad scope | Derived from stated base and CAGR |
Our analysis suggests the USD 64.6 billion figure is the more defensible top-line because it consolidates academic journals, research papers, and digital-native platforms that AAP member reporting underrepresents. The ~USD 30 billion trade statistic reflects a narrower member-survey base and should be read as a partial floor, not a market total.
Segmentation follows two axes: content type, which determines revenue concentration, and delivery format, which determines growth trajectory. Book publishing is the largest type; e-books and audiobooks are the fastest-moving formats.
| Parent segment | Children | Analytical note |
|---|---|---|
| By Type | Book Publishing; Newspaper Publishing; Magazine Publishing; Journals, Articles & Research Papers | Books anchor revenue; academic journals carry highest subscription durability |
| By Format | Hard Copy; E-book; Audiobook | E-books hold significant share; audiobooks grow fastest |
The segmentation implies a dual P&L structure. Trade publishers monetize a high-volume, hit-driven catalogue, while academic publishers monetize institutional subscriptions with far lower churn. Our analysis suggests operators should benchmark margin and retention separately across these two models rather than treating publishing as a single economics problem.
New York anchors the U.S. publishing market as the headquarters cluster for major trade houses, while California and the South contribute rapidly growing independent and digital-first output. Exact sub-regional revenue percentages are not publicly disclosed; the geography tree below reflects concentration of publisher operations.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.22% |
| South | 0.31% |
| West | 0.24% |
| Midwest | 0.18% |
| Other U.S. Territories | 0.05% |
Our analysis suggests the Northeast remains the pricing and acquisitions center of gravity, but editorial and revenue growth is increasingly distributed. That divergence creates a talent and cost advantage for operators willing to base production teams outside New York.
Digital publishing, self-publishing platforms, and audiobook consumption are the dominant growth engines, while print circulation decline and advertising migration to digital aggregators constrain legacy revenue. The net effect is slow but durable expansion.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Digital publishing and self-publishing ecosystems | Driver | High | Lowers entry barriers; expands catalogue and revenue participation |
| Audiobook and subscription consumption | Driver | High | Higher attach rates and recurring revenue per reader |
| AI-assisted editing, translation, audio production | Driver | Medium | Compresses production cost and time-to-market |
| Print circulation and print ad decline | Restraint | High | Erodes newspaper and magazine revenue base |
| Content oversaturation and discoverability limits | Restraint | Medium | Raises marketing cost per acquired reader |
Our analysis suggests the driver-restraint balance is asymmetric by segment: trade and digital-first publishers are net beneficiaries, while newspaper and magazine publishers face structural, not cyclical, pressure. The divergence implies portfolio reweighting toward academic subscriptions and audio rights is the highest-conviction strategic move.
Leading vendors differ by sub-market: the Big Five trade houses dominate consumer books, while Elsevier, Wiley, Springer Nature, and Taylor & Francis control academic and research publishing. Newspaper and magazine titles compete on subscription-led digital models.
| Company | Primary strength | Moat |
|---|---|---|
| Penguin Random House | Trade books, global rights | Author portfolio and bestseller acquisition |
| HarperCollins Publishers | Trade and series publishing | Distribution network and franchise IP |
| Simon & Schuster | Trade fiction and nonfiction | Backlist and rights licensing |
| Hachette Book Group | Trade and illustrated | Imprint breadth |
| Macmillan Publishers | Trade and educational | Digital capability |
| Scholastic Corporation | Children's and education | School channel access |
| John Wiley & Sons | Academic and professional | Institutional subscriptions |
| Elsevier | Scientific journals | Journal impact factor and databases |
| The New York Times Company | News subscription | Brand and subscriber base |
| Hearst Communications | Magazines and media | Multi-title portfolio |
Differentiation is increasingly driven by rights ownership and direct subscriber relationships rather than printing capability. Our analysis suggests the strongest moats now sit in subscription data and audiobook rights, not in distribution logistics.
Procurement and partnership decisions in this market hinge on rights scope, format rights granularity, and renewal terms. Buyers licensing content should verify whether e-book and audiobook rights are bundled or separately priced, since unbundled audio rights frequently carry the larger cost escalation.
Switching costs are highest in academic and research publishing, where institutional access integrates with library systems and citation workflows. By contrast, trade content licensing is more contestable, so buyers retain leverage through multi-house bidding.
Regulatory exposure centers on copyright enforcement, AI training-data licensing, and accessibility compliance for digital editions. Operators should treat AI licensing terms as a contract-review priority, because unresolved training-data rights now represent a material commercial and legal risk in any content acquisition.
The balance of evidence favors a modest-growth, structural-shift reading of the U.S. publishing market. A 2.4% CAGR is not a boom thesis; it is a reallocation thesis, in which digital formats, audio, and subscription models absorb share from print circulation and print advertising. The strongest counter-argument is that self-publishing has commoditized catalogue supply and could depress per-title revenue faster than the aggregate headline disguises. Our judgment is that this risk is real at the title level but offset at the market level by pricing power in academic subscriptions and brand-name trade IP.
A second-order effect deserves attention: as AI-assisted production lowers editorial cost, the binding constraint shifts from creation to discoverability. That implies marketing and rights acquisition become the primary margin battlegrounds, while pure production capability becomes a commodity. Operators who still model cost advantage on production efficiency are solving the wrong problem.
What would change this conclusion: a sustained acceleration in digital readership monetization above 5% annually, or regulatory clarity granting publishers enforceable opt-in consent for AI training data, would justify a materially more bullish growth case.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 2.4% from 2020-2034 |
| Segmentation |
|
The U.S. publishing market was valued at USD 64.6 billion in 2025, covering book, newspaper, magazine, and academic publishing across hard copy, e-book, and audiobook formats within the United States.
The market is projected to grow at a 2.4% CAGR from 2026 to 2033, expanding from USD 65.8 billion to USD 77.9 billion, driven mainly by digital formats, audiobooks, and subscription consumption.
Book publishing is the largest type segment, supported by trade, educational, and professional titles. By format, e-books hold significant share while audiobooks are the fastest-growing format in the market.
Major players include Penguin Random House, HarperCollins, Simon & Schuster, Hachette, Macmillan, Scholastic, Wiley, Elsevier, The New York Times Company, and Hearst Communications, spanning trade, academic, and news publishing.
Structural decline in print circulation and the migration of advertising revenue to digital aggregators constrain newspaper and magazine publishers, pressuring legacy business models to restructure toward subscription-led digital revenue.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct verification of revenue, format mix, and rights structures. We conducted in-depth interviews with executives at trade publishing houses, academic and journal publishers, newspaper and magazine groups, digital-first and self-publishing platforms, and audiobook producers. Interviewees included VP-level heads of publishing and editorial, Chief Revenue Officers, Heads of Rights and Licensing, and Commercial Operations Leads, each screened for direct responsibility over content investment or distribution decisions.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Publishing & Editorial Leads | 35% |
| Commercial & Revenue Officers | 30% |
| Rights & Licensing Heads | 20% |
| Digital Product Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| Trade Book Publishers | 38% |
| Academic & Journal Publishers | 27% |
| News & Magazine Publishers | 20% |
| Digital & Self-Publishing Platforms | 15% |
Findings were cross-checked against official multilateral and standards sources, including U.S. Census Bureau and Bureau of Economic Analysis data, U.S. International Trade Commission filings, U.S. Securities and Exchange Commission 10-K and annual investor presentations from listed publishers, the USPTO patent database for AI-assisted publishing tools, and nonprofit industry association statistics covering copyright-sector output and publisher revenue reporting.
We run simultaneous top-down and bottom-up models. The top-down path allocates macro media and copyright-industry output across publishing types and formats. The bottom-up path aggregates publisher-reported revenue, title output, unit pricing, subscription and licensing volumes, and end-consumer reading consumption to reconcile at the base-year total.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |