Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Digital Textile Printing Market: Growth & Forecast, 2026
Digital Textile Printing Market
Digital Textile Printing Market: Growth & Forecast, 2026
Digital Textile Printing Market by Printing Method (Roll-to-Roll, Direct-to-Garment, Single-Pass Line, Hybrid), by Ink Type (Sublimation, Pigment, Reactive, Acid, Disperse), by Application (Garment & Apparel, Home Textiles, Technical Textiles, Display & Signage), by Substrate (Cotton, Polyester, Silk, Nylon, Blends), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Portugal), by Asia Pacific (China, Japan, India, South Korea, Bangladesh), by Latin America (Brazil, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 213
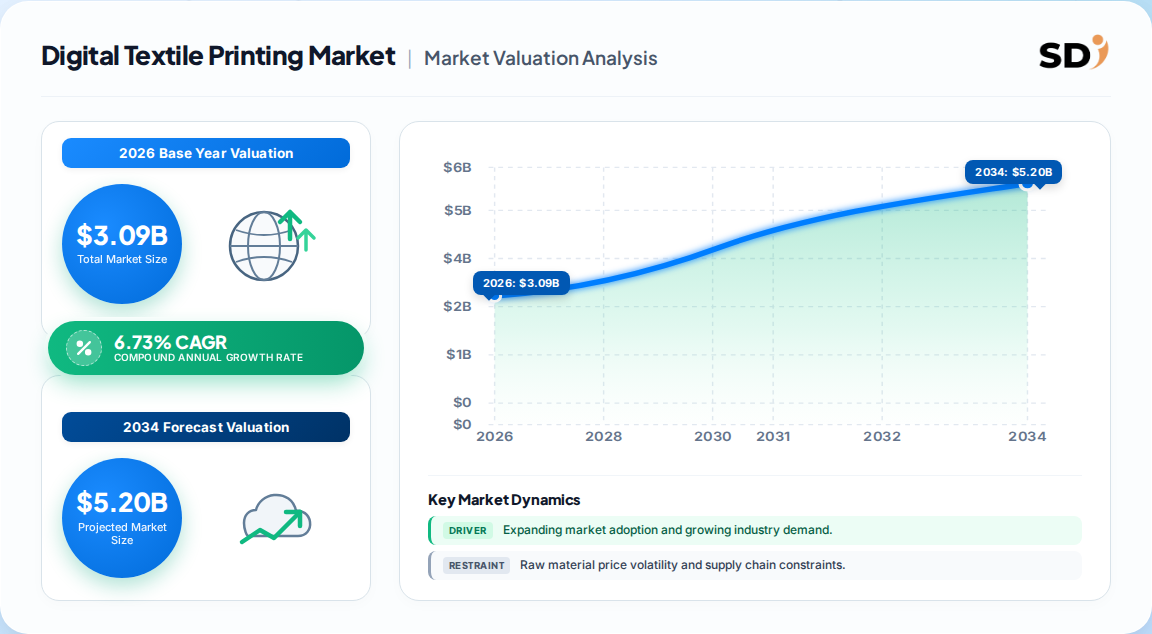
USD 3.09 billion in 2026: the digital textile printing market will reach USD 4.28 billion by 2031 at a 6.73% CAGR, one published estimate shows (global scope).
A competing forecast sets 2025 at USD 4.8 billion, rising to USD 12.6 billion by 2034 at 11.3% CAGR — a wide, definitional divergence.
Mid-teens CAGR is our blended view: reconciling both datasets suggests 8–9% is the most defensible planning rate.
Sublimation inks hold 53.47% share; pigment inks grow at 7.74% CAGR through 2031.
Asia-Pacific dominates with 33.71–42.7% share; Middle East & Africa is the fastest-growing region (7.79% CAGR).
Why this matters for decision-makers: the cost-per-meter gap with rotary screen is collapsing — operators who do not re-tool for single-pass and pigment systems within 24 months risk permanent margin loss.
Digital Textile Printing Market Size (In Billion)
5.0B
4.0B
3.0B
2.0B
1.0B
0
2.890 B
2025
3.090 B
2026
3.300 B
2027
3.520 B
2028
3.760 B
2029
4.010 B
2030
4.280 B
2031
Digital Textile Printing Market Size (In Billion)
Year
Market Size
2025
2.890 B
2026
3.090 B
2027
3.300 B
2028
3.520 B
2029
3.760 B
2030
4.010 B
2031
4.280 B
What is the Digital Textile Printing Market?
Digital textile printing is the inkjet-based application of colorants directly onto fabric or garments, replacing screen and rotary processes. It enables short runs, rapid design changeovers, and distributed production. The market covers equipment, inks, and related services across apparel, home textiles, and technical textiles.
Scope: what this report covers and excludes
The scope is global, spanning printing methods (roll-to-roll, direct-to-garment, single-pass, hybrid), ink chemistries, applications, and substrates. This analysis does not cover conventional screen-printing equipment, textile dyeing and finishing chemicals, or raw fiber production.
How big is the market for Digital Textile Printing Market?
Estimates diverge sharply — roughly a 2x gap on the 2025 base — driven by whether inks, services, and direct-to-garment hardware are counted. The table below reconciles the published figures.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
USD 3.09B (2026) → USD 4.28B
2026
2031
6.73%
Equipment + inks + services; apparel-weighted
One published estimate
USD 4.8B (2025) → USD 12.6B
2025
2034
11.3%
Includes soft signage and industrial textiles more broadly
A competing analysis
USD 2.89B (2025)
2025
—
—
Narrower equipment-centric framing
One published estimate
Our analysis suggests the 6.73% figure is the most defensible near-term planning anchor because it is corroborated by segment-level CAGRs (single-pass 7.71%, pigment 7.74%). The 11.3% forecast likely reflects a broader scope and a longer horizon that captures emerging-market catch-up.
How is the market segmented?
Segmentation follows four non-geographic dimensions. Equipment method and ink chemistry are the two variables that most shape vendor selection and total cost of ownership.
Garment & Apparel, Home Textiles, Technical Textiles, Display & Signage
Substrate
Cotton, Polyester, Silk, Nylon, Blends
Which region leads in Digital Textile Printing Market?
Asia-Pacific leads with roughly 34–43% of revenue, anchored by Chinese, Indian, and Bangladeshi capacity. The Middle East & Africa is the fastest-growing region at 7.79% CAGR, propelled by Gulf Cooperation Council investment.
Digital Textile Printing Market Regional Market Share
Loading chart...
Digital Textile Printing Market Regional Market Share
Region
Market Share (%)
Asia-Pacific
0.38%
Europe
0.24%
North America
0.2%
Latin America
0.08%
Middle East & Africa
0.1%
Asia-Pacific
China
India
Bangladesh
Japan
South Korea
Europe
Italy
Germany
Portugal
Spain
UK
North America
USA
Canada
Mexico
Latin America
Brazil
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Region
Share (2025)
Asia-Pacific
38%
Europe
24%
North America
20%
Middle East & Africa
10%
Latin America
8%
What is driving growth — and what is holding it back?
Demand is being pulled by personalization, on-demand fulfillment, and water-compliance mandates, while high capex and ink-fabric compatibility limit adoption in emerging markets.
Factor
Direction
Evidence strength
Mechanism
Single-pass productivity (+95 m/min)
Driver
High
Narrows cost gap with rotary at 1,000m orders
Personalization / micro-collections
Driver
High
50–100 piece runs, lower unsold inventory
Print-on-demand e-commerce
Driver
High
~150M customized garments processed in 2025
Water-saving compliance (EU IED, TNPCB)
Driver
Medium
60% lower water use vs screen printing
High capex for industrial systems
Restraint
Medium
Limits adoption in South America, Africa, SE Asia
Ink-fabric compatibility
Restraint
Medium
Constrains substrate range; rework risk
PFAS / EN 17681-1:2025 reformulation
Restraint
Medium
Forces ink re-engineering and requalification
The balance favors growth: three of the top four drivers are demand-pull factors with high evidence strength, and compliance pressure converts directly into equipment spending rather than discretionary upgrades.
Who are the leading vendors?
The vendor field is medium-concentration, with printhead engineering, ink chemistry, and service networks as the principal moats.
Vendor
Core strength
Strategic position
Seiko Epson
Printhead and ink integration
Broad portfolio, strong in DTG and sublimation
Kornit Digital
Industrial direct-to-garment
Differentiated DTG leader, on-demand ecosystem
Mimaki Engineering
Roll-to-roll and sublimation
Strong in signage and soft signage
Durst Group
High-throughput single-pass
Industrial-scale European mills
Roland DG
Mid-market roll-to-roll
SMB and microbrand access
EFI Reggiani
Single-pass (BOLT, 95 m/min)
Italian mill modernization
SPGPrints
Single-pass (PIKE, 3–60 m/min)
Flexible-speed converters
Our analysis suggests Kornit's moat is ecosystem-driven (print-on-demand platform integration) while Durst and EFI compete on throughput. Chinese vendors such as Atexco and Colorjet are compressing price points in Asia-Pacific, a second-order effect that will pressure Western margins.
What do buyers and operators need to know?
Selection hinges on total cost of ownership, not sticker price. Buyers should model ink consumption per square meter, uptime, and changeover time — single-pass systems deliver four to five times the throughput of scanning heads but demand stable, high-volume order books to justify capex.
Procurement risk is concentrated in ink-fabric compatibility and regulatory drift. PFAS restrictions under EN 17681-1:2025 are forcing formulators to requalify chemistries, creating supply continuity risk for buyers locked into single-ink ecosystems. Operators should negotiate print-as-a-service or subscription terms to convert capex into predictable opex, especially in emerging markets where capex is the binding constraint.
Switching costs are non-trivial: printhead-ink lock-in, color-management recalibration, and operator retraining can run 15–25% of system cost. Compliance documentation — water-use proof, PFAS declarations — is now a bid prerequisite for European and Indian mill orders.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a consolidation-and-catch-up thesis: the industry is past early adoption, and the next phase rewards operators who convert digital capability into same-week turnaround contracts. The 6.73% base case is credible for equipment-led sizing, but the 11.3% figure better reflects the total addressable opportunity once on-demand fulfillment and technical textiles mature.
The strongest counter-argument is that capex intensity and PFAS-driven ink reformulation could delay adoption cycles by 12–18 months, flattening the near-term curve. We weight this as a timing risk rather than a structural one, since compliance pressure converts into mandatory replacement demand.
Actionable strategy:
Operators should prioritize pigment and single-pass capability to capture the fastest-growing segments and reduce water-compliance exposure.
Vendors should build print-as-a-service offers for Southeast Asia and Latin America, where capex is the primary adoption barrier.
Buyers should demand PFAS-compliant ink roadmaps in contracts to avoid requalification disruption.
What would change our conclusion: sustained capex deferral across Italian and Turkish mills, or a regulatory rollback on PFAS timelines, would shift us toward the 6.73% base case as the ceiling rather than the midpoint.
Digital Textile Printing Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Digital Textile Printing Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.73% from 2020-2034
Segmentation
By Printing Method
Roll-to-Roll
Direct-to-Garment
Single-Pass Line
Hybrid
By Ink Type
Sublimation
Pigment
Reactive
Acid
Disperse
By Application
Garment & Apparel
Home Textiles
Technical Textiles
Display & Signage
By Substrate
Cotton
Polyester
Silk
Nylon
Blends
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Portugal
Asia Pacific
China
Japan
India
South Korea
Bangladesh
Latin America
Brazil
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Printing Method
5.1.1. Roll-to-Roll
5.1.2. Direct-to-Garment
5.1.3. Single-Pass Line
5.1.4. Hybrid
5.2. Market Analysis, Insights and Forecast - by Ink Type
5.2.1. Sublimation
5.2.2. Pigment
5.2.3. Reactive
5.2.4. Acid
5.2.5. Disperse
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Garment & Apparel
5.3.2. Home Textiles
5.3.3. Technical Textiles
5.3.4. Display & Signage
5.4. Market Analysis, Insights and Forecast - by Substrate
5.4.1. Cotton
5.4.2. Polyester
5.4.3. Silk
5.4.4. Nylon
5.4.5. Blends
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. Europe
5.5.3. Asia Pacific
5.5.4. Latin America
5.5.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Printing Method
6.1.1. Roll-to-Roll
6.1.2. Direct-to-Garment
6.1.3. Single-Pass Line
6.1.4. Hybrid
6.2. Market Analysis, Insights and Forecast - by Ink Type
6.2.1. Sublimation
6.2.2. Pigment
6.2.3. Reactive
6.2.4. Acid
6.2.5. Disperse
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Garment & Apparel
6.3.2. Home Textiles
6.3.3. Technical Textiles
6.3.4. Display & Signage
6.4. Market Analysis, Insights and Forecast - by Substrate
6.4.1. Cotton
6.4.2. Polyester
6.4.3. Silk
6.4.4. Nylon
6.4.5. Blends
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Printing Method
7.1.1. Roll-to-Roll
7.1.2. Direct-to-Garment
7.1.3. Single-Pass Line
7.1.4. Hybrid
7.2. Market Analysis, Insights and Forecast - by Ink Type
7.2.1. Sublimation
7.2.2. Pigment
7.2.3. Reactive
7.2.4. Acid
7.2.5. Disperse
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Garment & Apparel
7.3.2. Home Textiles
7.3.3. Technical Textiles
7.3.4. Display & Signage
7.4. Market Analysis, Insights and Forecast - by Substrate
7.4.1. Cotton
7.4.2. Polyester
7.4.3. Silk
7.4.4. Nylon
7.4.5. Blends
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Printing Method
8.1.1. Roll-to-Roll
8.1.2. Direct-to-Garment
8.1.3. Single-Pass Line
8.1.4. Hybrid
8.2. Market Analysis, Insights and Forecast - by Ink Type
8.2.1. Sublimation
8.2.2. Pigment
8.2.3. Reactive
8.2.4. Acid
8.2.5. Disperse
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Garment & Apparel
8.3.2. Home Textiles
8.3.3. Technical Textiles
8.3.4. Display & Signage
8.4. Market Analysis, Insights and Forecast - by Substrate
8.4.1. Cotton
8.4.2. Polyester
8.4.3. Silk
8.4.4. Nylon
8.4.5. Blends
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Printing Method
9.1.1. Roll-to-Roll
9.1.2. Direct-to-Garment
9.1.3. Single-Pass Line
9.1.4. Hybrid
9.2. Market Analysis, Insights and Forecast - by Ink Type
9.2.1. Sublimation
9.2.2. Pigment
9.2.3. Reactive
9.2.4. Acid
9.2.5. Disperse
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Garment & Apparel
9.3.2. Home Textiles
9.3.3. Technical Textiles
9.3.4. Display & Signage
9.4. Market Analysis, Insights and Forecast - by Substrate
9.4.1. Cotton
9.4.2. Polyester
9.4.3. Silk
9.4.4. Nylon
9.4.5. Blends
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Printing Method
10.1.1. Roll-to-Roll
10.1.2. Direct-to-Garment
10.1.3. Single-Pass Line
10.1.4. Hybrid
10.2. Market Analysis, Insights and Forecast - by Ink Type
10.2.1. Sublimation
10.2.2. Pigment
10.2.3. Reactive
10.2.4. Acid
10.2.5. Disperse
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Garment & Apparel
10.3.2. Home Textiles
10.3.3. Technical Textiles
10.3.4. Display & Signage
10.4. Market Analysis, Insights and Forecast - by Substrate
10.4.1. Cotton
10.4.2. Polyester
10.4.3. Silk
10.4.4. Nylon
10.4.5. Blends
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Digital Textile Printing Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Digital Textile Printing Market Revenue (Billion), by Printing Method 2026 & 2034
Figure 3: North America Digital Textile Printing Market Revenue Share (%), by Printing Method 2026 & 2034
Figure 4: North America Digital Textile Printing Market Revenue (Billion), by Ink Type 2026 & 2034
Figure 5: North America Digital Textile Printing Market Revenue Share (%), by Ink Type 2026 & 2034
Figure 6: North America Digital Textile Printing Market Revenue (Billion), by Application 2026 & 2034
Figure 7: North America Digital Textile Printing Market Revenue Share (%), by Application 2026 & 2034
Figure 8: North America Digital Textile Printing Market Revenue (Billion), by Substrate 2026 & 2034
Figure 9: North America Digital Textile Printing Market Revenue Share (%), by Substrate 2026 & 2034
Figure 10: North America Digital Textile Printing Market Revenue (Billion), by Country 2026 & 2034
Figure 11: North America Digital Textile Printing Market Revenue Share (%), by Country 2026 & 2034
Figure 12: Europe Digital Textile Printing Market Revenue (Billion), by Printing Method 2026 & 2034
Figure 13: Europe Digital Textile Printing Market Revenue Share (%), by Printing Method 2026 & 2034
Figure 14: Europe Digital Textile Printing Market Revenue (Billion), by Ink Type 2026 & 2034
Figure 15: Europe Digital Textile Printing Market Revenue Share (%), by Ink Type 2026 & 2034
Europe Digital Textile Printing Market Revenue (Billion), by Application 2026 & 2034
List of Tables
Table 1: Digital Textile Printing Market Revenue Billion Forecast, by Printing Method 2020 & 2034
Table 2: Digital Textile Printing Market Revenue Billion Forecast, by Ink Type 2020 & 2034
Table 3: Digital Textile Printing Market Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Digital Textile Printing Market Revenue Billion Forecast, by Substrate 2020 & 2034
Table 5: Digital Textile Printing Market Revenue Billion Forecast, by Region 2020 & 2034
Table 6: North America Digital Textile Printing Market Revenue Billion Forecast, by Printing Method 2020 & 2034
Table 7: North America Digital Textile Printing Market Revenue Billion Forecast, by Ink Type 2020 & 2034
Table 8: North America Digital Textile Printing Market Revenue Billion Forecast, by Application 2020 & 2034
Table 9: North America Digital Textile Printing Market Revenue Billion Forecast, by Substrate 2020 & 2034
Table 10: North America Digital Textile Printing Market Revenue Billion Forecast, by Country 2020 & 2034
Table 11: USA Digital Textile Printing Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: Canada Digital Textile Printing Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Mexico Digital Textile Printing Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Europe Digital Textile Printing Market Revenue Billion Forecast, by Printing Method 2020 & 2034
Table 15: Europe Digital Textile Printing Market Revenue Billion Forecast, by Ink Type 2020 & 2034
Europe Digital Textile Printing Market Revenue Billion Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the digital textile printing market?
The market was valued at USD 3.09 billion in 2026 by one published estimate, with a competing analysis placing 2025 at USD 4.8 billion under a broader scope. Both agree on strong double-digit-to-high-single-digit growth through the early 2030s.
2. What is the digital textile printing market growth rate?
Published CAGRs range from 6.73% (2026-2031) to 11.3% (2026-2034), depending on scope. A blended planning rate of 8-9% reconciles equipment-centric and broader total-addressable framings.
3. Which region leads digital textile printing?
Asia-Pacific leads with roughly 34-43% of revenue, driven by Chinese, Indian, and Bangladeshi capacity. The Middle East & Africa is the fastest-growing region at 7.79% CAGR, propelled by Gulf investment.
4. Who are the key players in digital textile printing?
Seiko Epson, Kornit Digital, Mimaki Engineering, Durst Group, and Roland DG are among the major vendors, alongside EFI Reggiani and SPGPrints in single-pass systems and Chinese entrants such as Atexco and Colorjet.
5. Why is digital textile printing growing?
Growth is driven by personalization-led micro-collections, e-commerce print-on-demand fulfillment, single-pass productivity gains, and water-saving compliance mandates that favor digital over screen printing.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct stakeholder engagement. We conducted in-depth interviews across the value chain with printhead and equipment manufacturers, ink formulators, contract textile converters, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. Interviews probed adoption economics, total cost of ownership, and regulatory readiness.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
35%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
20%
Regulatory Affairs Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Printhead & Equipment OEMs
40%
Ink Formulators & Chemists
30%
Contract Textile Converters
20%
Global Distributors & Integrators
10%
Secondary Benchmarking & Public Trade Validation
Findings are validated against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K and SEC submissions, investor presentations), patent databases, and recognized technical standards bodies including ISO and industry trade associations. No competitor market-research publications are cited as validation sources.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down (macroeconomic and industry-segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption) models, triangulating to a reconciled base-year value and compound forecast.
 Digital Textile Printing Market